
Cast Steel Shot & Grit Market: Strategic Intelligence for 2026–2032 Decision-Making
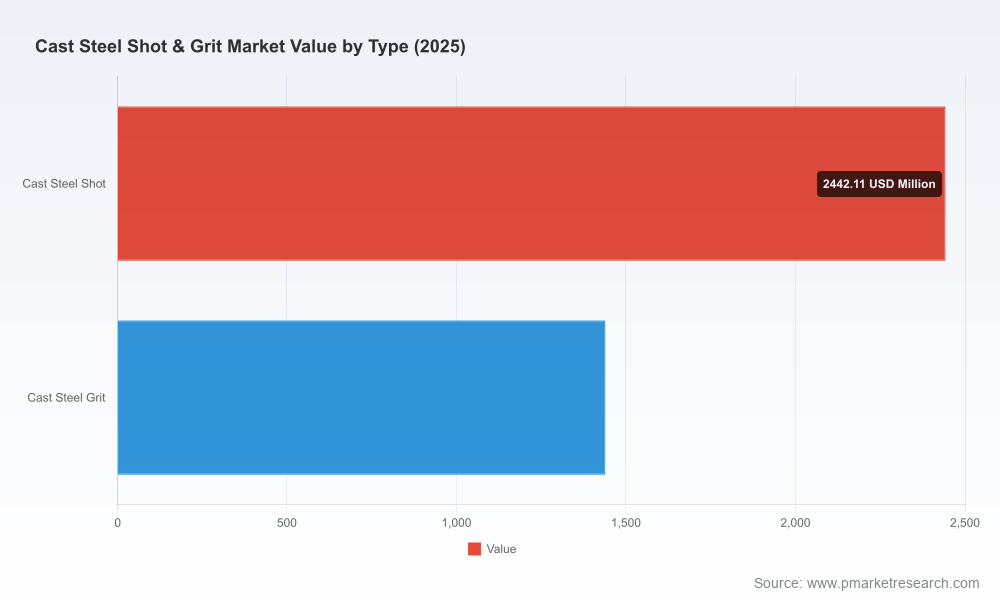
The global cast steel shot and grit market stands at a critical inflection point. With a base year valuation of USD 3,880.82 million in 2025 and a projected compound annual growth rate (CAGR) of 3.7% through 2032, the industry is expected to surpass USD 5 billion by the final forecast year. This steady yet resilient expansion reflects the enduring importance of high-performance abrasives in surface preparation, shot peening, and blast cleaning across multiple heavy industries. As manufacturers face tightening quality standards, rising raw material volatility, and increasing pressure for sustainable operations, strategic clarity has never been more valuable.
Cast Steel Shot & Grit Market
This in-depth market research report, developed by PW Consulting, is designed specifically for C-level executives, strategy directors, and investment professionals who require more than surface-level statistics. It delivers actionable intelligence that translates market complexity into competitive advantage for the pivotal year of 2026 and beyond. Rather than offering generic forecasts, the study uncovers structural shifts, hidden supply-chain vulnerabilities, and technology-driven opportunities that will separate market leaders from followers in the coming decade.
Cast Steel Shot & Grit Market
The Strategic Value of Forward-Looking Market Intelligence
In an industry where capital investment decisions for new abrasive production lines often exceed tens of millions of dollars and carry multi-year payback periods, imprecise market understanding can prove costly. The 2026–2032 forecast window is particularly significant. It coincides with accelerated fleet modernization in aerospace and automotive sectors, large-scale shipbuilding programs in Asia, and continued infrastructure development globally. Companies that align their capacity expansion, product development, and geographic positioning with these underlying demand drivers will secure disproportionate share of the projected growth.
Cast Steel Shot & Grit Market
This report equips decision-makers with the analytical framework necessary to stress-test their current strategies against multiple market scenarios. It examines how raw material price fluctuations, evolving international standards, and shifting competitive dynamics will reshape profitability landscapes. By deliberately withholding granular segmentation details and proprietary modeling outputs in this preview, we invite serious industry stakeholders to access the complete research for the full strategic picture that can inform board-level capital allocation and M&A decisions.
Market Dynamics: Beyond the Headline Numbers
The cast steel shot and grit industry operates at the intersection of raw material economics, regulatory compliance, and technological evolution. Recent movements in steel scrap and pig iron pricing have created margin pressure across the value chain. Brazilian pig iron prices reached $430 per dry metric ton in January 2026, while US shredded scrap and busheling prices climbed 8–14% over the preceding three months. These increases, combined with a global steel benchmark hovering around 3,103 CNY per ton, underscore the need for sophisticated sourcing strategies and pricing power analysis.
Regulatory factors further complicate the operating environment. Manufacturers must consistently meet stringent specifications including SAE J444 for sizing, SAE J1993 for microstructure, hardness, and density, as well as the European standard EN ISO 11124-3:2018, which defines 14 grades of shot and 11 grades of grit for blast-cleaning applications. Aerospace applications face even higher bars, with select producers required to maintain compliance with AMS 2431 specifications. The report examines how these standards are evolving and which companies are best positioned to turn compliance into a competitive moat.
Simultaneously, sustainability has moved from a peripheral concern to a central strategic consideration. The renewal of EcoVadis Silver CSR certification by leading players signals growing customer expectations around environmental performance in abrasive manufacturing. Forward-thinking companies are exploring ways to reduce energy consumption in production while maintaining the durability and cleaning efficiency that end-users demand.
Competitive Landscape: Leaders, Challengers, and Emerging Differentiators
The cast steel shot and grit market exhibits moderate concentration, with the top three players accounting for approximately 42% of global revenue and the top five reaching nearly 58%. This structure creates a dynamic environment where both established multinationals and agile regional specialists continue to innovate.
Ervin Industries remains the only North American manufacturer capable of producing cast steel shot and grit that fully conforms to AMS 2431 aerospace specifications. Its AMASTEEL brand, produced from domestically sourced scrap, has built a reputation for consistency in critical applications such as shot peening for aircraft components. The company’s continued focus on AMS-grade ASR and ASH products positions it strongly as aerospace OEMs increase production rates.
Winoa (operating under the WAbrasives brand) stands as a true global leader with eight production sites worldwide. The French company’s recent renewal of EcoVadis Silver certification reinforces its commitment to responsible manufacturing. Its broad product portfolio of high-carbon cast steel shot and grit serves surface treatment needs across automotive, shipbuilding, and general industrial markets. The scale of its global footprint provides resilience against regional supply disruptions.
Metaltec Steel Abrasive Company has carved a specialized position in the North American market through its focus on low-carbon Bainite cast steel shot meeting SAE J2175 specifications. Its products offer superior durability and controlled wear characteristics without requiring additional tempering steps. The addition of state-of-the-art grit production capacity in 2009 has strengthened its competitive profile in both shot and grit categories.
On the Asian side, Shandong Kaitai Group stands as the region’s largest metal abrasive producer with an annual capacity of 250,000 tons. The company has invested heavily in double quenching and tempering processes to enhance the strength and durability of its cast steel shot and grit. Its scale provides significant cost advantages that have enabled aggressive expansion in both domestic and international markets.
Zibo TAA Metal Technology, recognized as a National Hi-tech Enterprise in China, has established itself among the global top five producers. Its LCB steel shot and standard cast products meet SAE standards and are exported to more than 50 countries. The company’s technical focus has allowed it to penetrate demanding applications in aerospace, automotive, and shipbuilding.
Smaller but technologically innovative players such as Rotocast Industries and JX Abrasives are also reshaping competitive dynamics. Rotocast’s adoption of advanced horizontal and vertical centrifugal casting methods in late 2024 has produced cast steel abrasives with measurably higher strength and density. JX Abrasives has focused on optimizing particle shapes and sizes to achieve superior cleaning efficiency in specific verticals including shipyards and aerospace component manufacturing.
The report provides detailed benchmarking of these companies across production technology, product certification portfolios, geographic reach, and recent strategic moves. It evaluates which competitors are best positioned to capture incremental demand in high-growth applications and which may face margin compression as raw material costs remain elevated.
Comprehensive Scope: What the Full Report Delivers
This PW Consulting study goes far beyond basic market sizing. The complete report includes:
- Granular analysis of demand drivers by end-use sector, including emerging requirements in electric vehicle manufacturing, next-generation shipbuilding techniques, and precision aerospace component processing
- Technology roadmap assessment covering advancements in abrasive microstructure, production process efficiency, and surface preparation automation
- Raw material supply chain mapping with risk assessment for scrap steel, pig iron, and alloying elements
- Pricing trend analysis and margin structure modeling under multiple raw material and energy cost scenarios
- Regulatory impact assessment covering current and forthcoming standards in North America, Europe, and Asia
- Strategic recommendation framework for capacity expansion, product portfolio optimization, and potential M&A targets
- Scenario-based forecasting models that stress-test market growth against geopolitical, economic, and technological variables
Particular attention is given to the shifting balance between cast steel shot and grit applications. While both categories serve overlapping yet distinct purposes in surface preparation, their performance characteristics, consumption patterns, and pricing dynamics differ meaningfully. The report explores these nuances with proprietary data that cannot be adequately summarized in this introduction.
Why 2026 Represents a Strategic Crossroads
The year 2026 marks more than just another annual planning cycle. It represents the point at which many large-scale capital projects initiated during the post-pandemic recovery will reach critical decision gates. Automotive plants transitioning toward electric vehicle platforms, shipyards expanding to accommodate larger vessels, and aerospace manufacturers scaling production for both commercial and defense programs will all require reliable, high-specification surface preparation solutions.
Companies that enter this period with superior market intelligence will be able to optimize their product mix, secure long-term supply agreements with strategic customers, and make targeted investments in production technology that deliver both performance and sustainability advantages. Conversely, those relying on incomplete or outdated information risk misallocating capital in a market where the competitive window for differentiation is narrowing.
The cast steel shot and grit industry, though mature, continues to evolve through material science improvements, process innovation, and changing customer expectations. The difference between merely participating in the market and thriving within it increasingly depends on the depth of strategic insight available to leadership teams.
This PW Consulting market research report is intended to provide exactly that depth. By combining rigorous data collection, sophisticated modeling, and decades of industry experience, it offers a comprehensive strategic framework for navigating the opportunities and challenges that lie ahead through 2032.
For executives seeking to transform market complexity into competitive advantage, the complete study provides the detailed segmentation, proprietary forecasting models, and actionable recommendations necessary for confident decision-making. We invite qualified industry stakeholders to access the full report to gain the complete intelligence picture that will shape successful strategies in the years ahead.
— End of Preview —
The full Cast Steel Shot & Grit Market Research Report (2026–2032) is available exclusively through PW Consulting. Contact our industry analysis team to discuss how this research can support your specific strategic requirements.
For detailed analysis of this topic, please visit the official page:Cast Steel Shot & Grit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek