
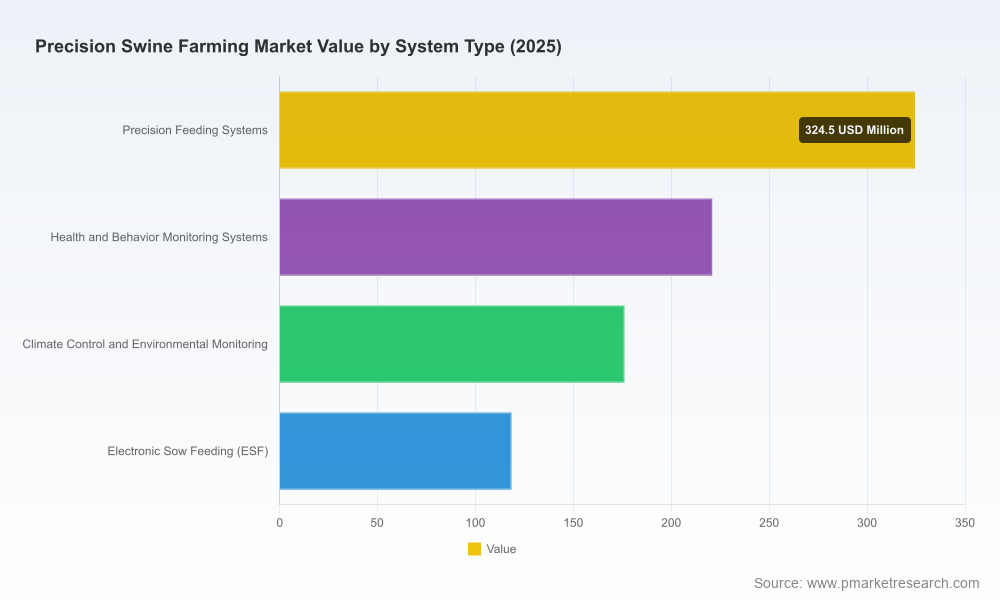
**Precision Swine Farming: Navigating a $1.5 Billion Future of Efficiency, Sustainability, and Competitive Advantage** The global swine industry stands at an inflection point. As pork remains one of the most consumed proteins worldwide, producers face intensifying pressure to deliver higher welfare standards, lower environmental impact, and greater profitability amid volatile feed costs, labor shortages, and tightening regulations. Precision swine farming technologies, which integrate sensors, automation, data analytics, and AI-driven decision tools, have emerged as the strategic response. According to PW Consulting’s latest Worldwide Precision Swine Farming Market research, the sector is experiencing robust expansion, with the market growing at a compound annual growth rate of 9.48% from 2026 to 2032. This trajectory reflects not merely technological adoption but a fundamental redefinition of how modern swine operations create and capture value. This thought-leadership article serves as a strategic preview of PW Consulting’s comprehensive 2025-base-year market study. It reveals why precision swine farming is transitioning from a niche innovation to a boardroom imperative and demonstrates how the forthcoming report equips executives with actionable intelligence for 2026–2032 capital allocation, partnership strategy, and competitive positioning. **The Strategic Imperative: Why Precision Matters Now** Swine production economics remain dominated by feed, which typically accounts for 60–70% of total costs. In an era of volatile commodity prices and sustainability mandates, even marginal improvements in feed conversion ratios deliver outsized returns. Precision feeding systems, health and behavior monitoring, climate control, and electronic sow feeding solutions enable producers to optimize nutrient delivery, reduce waste, and improve herd uniformity at scale. Labor savings of 30–50% through automation further strengthen the business case, particularly in regions facing acute workforce challenges. Regulatory tailwinds are equally compelling. The European Commission’s revised Industrial Emissions Directive, finalized in 2024, mandates continuous emissions monitoring for large livestock sites, directly accelerating demand for integrated environmental and climate control platforms. Parallel developments in animal welfare regulations and the global push toward antibiotic-free production have elevated the importance of real-time health and behavior monitoring. In key European markets such as Germany, Spain, and the Netherlands, governments are offering subsidies covering up to 40% of eligible precision hardware investments, effectively de-risking modernization for both large-scale industrial operations and progressive small-to-medium farms. These converging forces have propelled the global precision swine farming market from approximately $540 million in 2020 to an estimated $840 million in 2025, with continued acceleration projected through the forecast period. The market is expected to surpass $1.5 billion by 2032, underscoring a multi-year investment cycle that forward-looking agribusinesses cannot afford to miss. **Market Structure and Competitive Dynamics** The precision swine farming landscape exhibits moderate concentration, with the top three players accounting for roughly one-third of global revenues and the top five capturing just over half. This structure indicates an industry still open to innovation and regional specialization, yet increasingly dominated by companies capable of delivering integrated, interoperable platforms rather than isolated hardware. European-headquartered firms currently lead in technology sophistication and regulatory alignment. Nedap N.V. (Netherlands) has built a formidable position through its Livestock Connect platform and Pigs Connections API, enabling seamless data interoperability across feeding, monitoring, and weight detection systems. The company’s focus on individual sow management aligns perfectly with tightening welfare standards and electronic sow feeding (ESF) adoption curves. CTB, Inc. (United States), through its Chore-Time and Fancom brands, offers one of the broadest portfolios in the industry, spanning automated feeding, ventilation, climate control, manure handling, and advanced biometric solutions. Fancom’s eYeGrow 3D camera system, upgraded in late 2024 to achieve up to 98% accuracy in daily weight monitoring for finisher pigs (25–130 kg), exemplifies how vision-based analytics are moving from novelty to core herd management tools. The September 2024 upgrade and CTB’s March 2025 launch of its Chore-Time Barn Management Control System demonstrate the pace at which leading players are refreshing their offerings. Big Dutchman International GmbH (Germany) brings deep expertise in holistic pig house design, combining precision climate control with welfare-oriented barn concepts such as Havito and Xaletto straw-bedding systems. Its digitalization tools for sow management, finishing, and piglet rearing appeal to producers seeking both regulatory compliance and measurable improvements in key performance indicators. Other notable specialists include Hotraco Agri (Netherlands) with its AI-based predictive climate and feed controls, Roxell (Belgium) which launched significant upgrades to its Discaflex feed transport and iQon Multifast batch feeding systems in 2025, and Jyga Technologies (GESTAL, Canada) recognized for advanced electronic sow feeding solutions. Merck Animal Health and Boehringer Ingelheim are extending their pharmaceutical leadership into digital health platforms, creating convergence between animal health data and precision management systems. Chinese innovators such as Guangzhou Yingzi Technology and Big Herdsman are rapidly expanding both domestically and into emerging Asian and Latin American markets, often emphasizing cost-effective integration of feeding, ventilation, and environmental controls. This competitive mosaic reveals a clear strategic divide: integrated platform providers versus niche specialists. Success in the coming decade will likely favor companies that can deliver open-architecture solutions enabling data interoperability across the entire production chain. **Technology Segmentation and Value Creation Opportunities** The precision swine farming market is segmented across multiple dimensions that reflect distinct value propositions and adoption barriers. System-type differentiation reveals four primary clusters: precision feeding systems, health and behavior monitoring, climate control and environmental monitoring, and electronic sow feeding. Each addresses specific pain points while contributing to overlapping outcomes in productivity, sustainability, and risk mitigation. Farm-size dynamics further shape strategic priorities. Large-scale industrial operations, which already represent the majority of technology spend, leverage precision solutions for standardization, traceability, and maximum operational leverage. However, small and medium-sized farms are emerging as a high-growth adjacency market, particularly where government subsidies lower the entry barrier and where labor savings deliver immediate ROI. Geographic variation remains pronounced. Asia Pacific continues to represent the largest regional opportunity, driven by scale expansion in China and Southeast Asia coupled with rising quality and traceability requirements. Europe leads in regulatory-driven adoption and technological sophistication. North America balances innovation leadership with a more fragmented production base. Latin America and the Middle East & Africa, while smaller today, offer attractive long-term growth as commercial swine production intensifies. **What the PW Consulting Report Delivers: Actionable Intelligence for 2026 Decision-Making** PW Consulting’s Worldwide Precision Swine Farming Market research is designed as a strategic decision-support platform rather than a static data repository. The full study provides executives with: - Granular market sizing and forecast models through 2032, including multiple macroeconomic and industry-specific scenarios - Detailed competitive benchmarking of over 15 leading and emerging players, including technology portfolios, go-to-market strategies, partnership ecosystems, and recent innovation trajectories - Comprehensive segmentation analysis across system types, farm sizes, and geographic markets, with identification of high-growth pockets and white-space opportunities - Technology adoption frameworks that map maturity levels, integration complexity, and ROI timelines for different solutions - Regulatory impact assessments and subsidy mapping to inform capital deployment timing and geographic prioritization - Supply chain and value chain analysis highlighting upstream sensor and AI component trends as well as downstream processor and retailer traceability requirements - Strategic recommendations tailored for technology providers, large integrators, animal health companies, and financial investors The report’s unique value lies in its forward-looking scenario planning. Rather than offering single-point forecasts, it equips readers with the analytical tools to stress-test their strategies against varying feed price environments, regulatory tightening speeds, and technology adoption rates. **Strategic Recommendations for Different Stakeholder Groups** For swine producers and integrators, the message is clear: 2026 represents a pivotal window for technology modernization. Companies that delay risk falling behind in both cost competitiveness and regulatory compliance. Early adopters are already demonstrating superior feed efficiency, reduced mortality, and enhanced animal welfare metrics that translate into measurable brand and financial advantages. Technology vendors should prioritize platform openness and ecosystem partnerships. The most successful players will be those that can integrate with existing farm management software, animal health platforms, and processor traceability systems. The recent product launches by Roxell, CTB, and Fancom illustrate the accelerating innovation cycle that demands continuous R&D investment. Animal health leaders such as Merck and Boehringer Ingelheim are uniquely positioned to create differentiated offerings by combining pharmaceutical expertise with precision monitoring data. This convergence represents one of the highest-potential white spaces in the industry. Investors should view precision swine farming as a resilient growth sector within agritech, offering exposure to both defensive characteristics (regulatory necessity) and offensive upside (productivity gains and sustainability premiums). **Conclusion: From Data to Decision Advantage** The precision swine farming market is not merely growing; it is evolving from a collection of discrete technologies into a comprehensive management philosophy that will define competitive advantage in the global pork value chain. The companies and producers that master this transition will capture disproportionate value in an industry where margins remain under constant pressure. PW Consulting’s 2025 Worldwide Precision Swine Farming Market research is specifically engineered to support the critical strategic decisions that must be made in 2026 and beyond. By combining rigorous data-driven modeling with deep competitive and regulatory insight, the report transforms market complexity into clear strategic direction. Industry leaders seeking the complete intelligence package, including full segmentation details, company-specific profiles, scenario models, and strategic playbooks, are invited to access the full report at the PW Consulting research portal. In a market moving at unprecedented speed, timely access to authoritative intelligence represents one of the highest-ROI investments available to agribusiness executives today. (Word count: 1,378)
For detailed analysis of this topic, please visit the official page:Worldwide Precision Swine Farming Market
Worldwide Precision Swine Farming Market
Worldwide Precision Swine Farming Market
Worldwide Precision Swine Farming Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek