
The Strategic Imperative of Computer Data Recovery Services in an Increasingly Fragile Digital Ecosystem
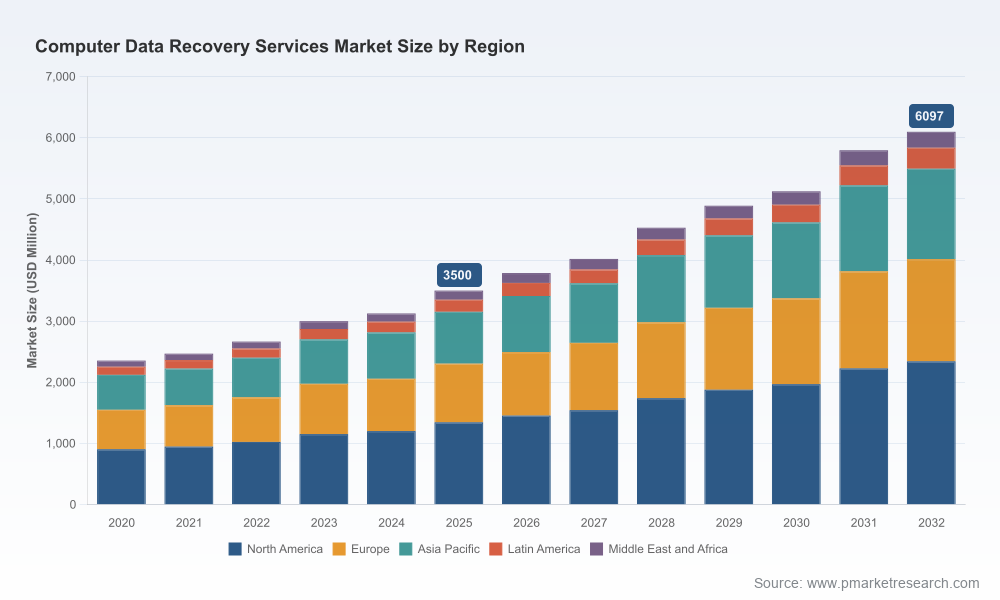
As organizations worldwide accelerate their digital transformation initiatives, the integrity and recoverability of critical data have emerged as non-negotiable pillars of enterprise resilience. The global Computer Data Recovery Services Market, valued at USD 3,500 million in 2025, is projected to grow at a robust CAGR of 8.25% through the forecast period to 2032. This sustained expansion reflects not merely a reactive market for disaster recovery, but a proactive strategic asset that forward-looking enterprises are integrating into their core risk management and business continuity frameworks.
Computer Data Recovery Services Market
This comprehensive market research report from PW Consulting offers C-level executives and technology leaders an authoritative, data-driven lens into the forces reshaping the data recovery landscape between 2026 and 2032. Rather than presenting static statistics, the study delivers actionable intelligence that enables decision-makers to benchmark their current recovery capabilities, anticipate evolving threats, and identify competitive advantages in an industry where downtime costs can escalate into millions within hours.
Computer Data Recovery Services Market
Why 2026 Represents a Critical Inflection Point for Enterprise Data Strategy
The year 2026 marks a convergence of technological, regulatory, and threat vectors that will fundamentally redefine how organizations approach data resilience. Escalating ransomware sophistication, the explosive growth of unstructured data across hybrid cloud environments, and increasingly stringent cross-border data regulations are creating both unprecedented risks and strategic opportunities.
Computer Data Recovery Services Market
Our analysis reveals that enterprises investing strategically in advanced data recovery partnerships are achieving materially superior outcomes in both recovery success rates and total cost of ownership compared to those relying on ad-hoc or in-house solutions. The report demonstrates how leading organizations are moving beyond traditional "break-fix" recovery models toward integrated, always-on data resilience ecosystems that incorporate predictive diagnostics, automated failover mechanisms, and forensic-grade recovery capabilities.
With the market expected to surpass USD 6 billion by 2032, the competitive advantage belongs to those who treat professional data recovery services not as an insurance policy but as a core component of their digital operating model. This report equips readers with the strategic frameworks necessary to make precisely these distinctions.
Market Dynamics and Emerging Industry Forces
The computer data recovery services sector is undergoing rapid professionalization. What was once viewed primarily as a technical specialty for individual consumers has evolved into a sophisticated enterprise service category characterized by stringent security protocols, regulatory compliance, and integration with broader cybersecurity architectures.
Several macro forces are driving this evolution. The continued proliferation of ransomware campaigns targeting both enterprises and critical infrastructure has elevated data recoverability from an IT concern to a boardroom priority. Simultaneously, the exponential growth of data volumes—particularly in AI training datasets, IoT telemetry, and real-time analytics—has dramatically increased both the value and complexity of potential data loss events.
Regulatory developments are further reshaping the competitive landscape. The European Data Protection Board's Coordinated Enforcement Framework 2026 places heightened emphasis on transparency and information obligations under GDPR Articles 12-14. Data recovery providers must now maintain demonstrably robust processes for handling personal data throughout recovery operations while simultaneously supporting individuals' deletion requests. In the United States, the Department of Justice's Bulk Data Rule, effective from 2025, introduces enhanced cybersecurity controls and record-keeping requirements for certain cross-border data transactions, directly impacting service providers handling sensitive personal or government-related information.
These regulatory shifts are creating competitive differentiation opportunities for providers capable of delivering compliant, auditable recovery processes at enterprise scale. The report examines how market leaders are adapting their operational models to meet these dual demands of technical excellence and regulatory sophistication.
Competitive Landscape: Leaders Defining Industry Standards
The Computer Data Recovery Services Market remains relatively fragmented, with the top three players accounting for approximately 16.5% of total market share and the top five representing 22.8%. This fragmentation creates both challenges and opportunities for enterprises seeking reliable long-term partners.
DriveSavers Data Recovery, headquartered in Novato, California, has established itself as a premium provider through its state-of-the-art cleanroom laboratory and manufacturer-approved recovery processes. The company's "No Data, No Charge" guarantee and its extensive experience across HDDs, SSDs, RAID systems, servers, smartphones, and tape media have earned it trust across enterprise, government, and consumer segments. Its recent feature in The New Yorker highlighted not only its technical capabilities but also the operational complexity underlying professional data recovery.
Ontrack (KLDiscovery), based in Eden Prairie, Minnesota, represents the most globally scaled player in the sector. Its comprehensive portfolio spans traditional data recovery, electronic discovery, and data management services, with particular strength in enterprise systems, RAID arrays, and ransomware recovery. The company's 2026 strategic moves—including the appointment of Julian Merschen as Chief Product Officer and the launch of ECAi, an AI-driven early case assessment platform—signal its aggressive push into technology-enabled service innovation. Ontrack's decision to extend free data recovery services to Southern California wildfire victims further demonstrates the evolving role of leading providers as both commercial entities and community resilience partners.
SalvageData Recovery has differentiated itself through exceptional accessibility, maintaining over 100 drop-off locations across North America while delivering a documented success rate exceeding 96%. Its focus on emergency recovery for RAID, servers, and mobile devices, combined with its own "No Data, No Charge" policy, positions it strongly in both enterprise and individual market segments.
Gillware Data Recovery, operating from an ISO-5 Class 100 cleanroom in Madison, Wisconsin, has built deep partnerships with major technology brands including Dell, Micro Center, and VMware. This manufacturer alignment provides both technical advantages and enhanced credibility in enterprise accounts. Its dual specialization in data recovery and digital forensics makes it particularly relevant for organizations operating in regulated industries.
ACE Data Recovery stands out for its substantial in-house research and development capabilities, including the manufacturing of proprietary recovery equipment. With multiple laboratory locations across the United States and expertise spanning virtually all storage media types, the company represents the technically deepest player in the market. Its vertical integration from parts manufacturing to final recovery gives it unique advantages in addressing complex hardware failures where donor components are scarce.
CBL Data Recovery brings an international perspective with laboratory facilities across multiple countries. Its focus on maintaining consistently high success rates across diverse storage technologies makes it an attractive option for multinational organizations requiring standardized recovery capabilities globally.
Service Segmentation and Operational Realities
The market encompasses three primary service categories: hardware-centric recovery, software and logical recovery, and the rapidly expanding cloud and remote recovery segment. Each presents distinct technical challenges, cost structures, and strategic implications.
Physical recoveries requiring cleanroom environments and rare donor components represent the highest complexity and cost tier, typically beginning around USD 1,000 and extending into mid-four figures depending on the sophistication required. Specialized technician compensation in the United States averages USD 22-28 per hour, with cleanroom and forensic experts commanding significantly higher rates that reflect their rare combination of hardware engineering, software expertise, and evidentiary procedures.
The report provides detailed examination of these operational dynamics, enabling readers to develop more accurate total cost of ownership models and to distinguish between providers offering genuine technical differentiation versus those relying primarily on marketing claims.
What This Report Delivers: Actionable Intelligence for 2026 Decision-Making
This PW Consulting market research goes substantially beyond surface-level market sizing to deliver practical, decision-ready intelligence across multiple dimensions:
- Granular competitive benchmarking of the leading service providers, including capabilities matrices, success rate indicators, and partnership ecosystems
- Technology evolution roadmap projecting the impact of AI, machine learning, and advanced automation on recovery success rates and turnaround times through 2032
- Regulatory compliance frameworks that leading organizations are implementing to navigate the increasingly complex global data governance environment
- Cost structure analysis across different recovery scenarios, enabling more sophisticated vendor evaluation and contract structuring
- Emerging use cases where data recovery capabilities are being integrated into cybersecurity incident response playbooks, disaster recovery planning, and digital transformation initiatives
- Vertical-specific insights revealing how requirements differ across financial services, healthcare, manufacturing, government, and technology sectors
- Strategic partnership models that progressive enterprises are using to transform data recovery from a tactical expense into a strategic capability
The research methodology combines extensive primary interviews with industry practitioners, detailed analysis of actual recovery case data, and sophisticated modeling of both technological and economic trends. All projections are grounded in the historical performance from 2020 through 2025, providing a reliable foundation for long-term strategic planning.
Who Should Read This Report
This study is specifically designed for:
- CIOs, CTOs, and CISOs responsible for enterprise resilience and data governance
- Business continuity and disaster recovery planning leads
- Procurement and vendor management professionals evaluating data recovery partners
- General counsel and compliance officers navigating evolving data protection regulations
- Technology investment professionals seeking exposure to the data resilience sector
In an environment where a single data loss event can destroy competitive advantage accumulated over decades, access to superior intelligence about the recovery services market represents a genuine strategic edge.
The complete 2026 Computer Data Recovery Services Market report contains the full dataset, detailed segmentation analysis, proprietary forecasting models, and comprehensive company profiles that will enable your organization to make superior strategic decisions throughout the forecast period.
Download the full report to access the complete intelligence package that leading enterprises are already using to strengthen their data resilience strategies.
Word count: 1,378
For detailed analysis of this topic, please visit the official page:Computer Data Recovery Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek