
Navigating the Iron Ore Trade Landscape: Strategic Intelligence for 2026 and Beyond
The global iron ore trade market stands at a critical inflection point. As steelmakers worldwide recalibrate their raw material strategies amid shifting supply dynamics, evolving sustainability mandates, and persistent geopolitical tensions, decision-makers require more than surface-level statistics. They need actionable, forward-looking intelligence that translates complex market forces into competitive advantage. PW Consulting’s latest Worldwide Iron Ore Trade Market research delivers precisely that — a comprehensive, data-driven strategic blueprint designed to inform executive decisions through 2026 and the years to follow.
Worldwide Iron Ore Trade Market
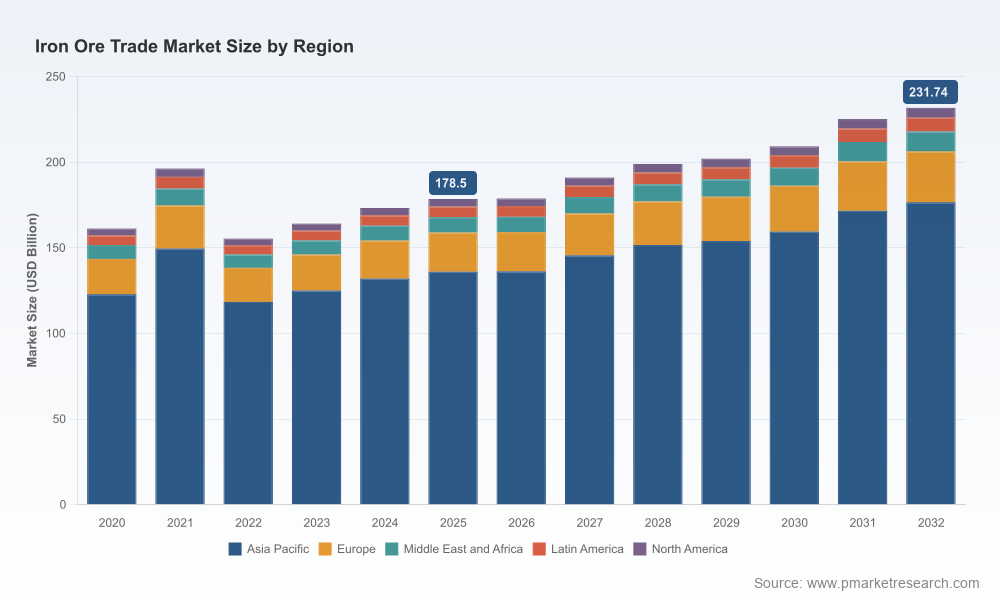
With a base year of 2025 and historical analysis spanning 2020–2025, the report projects the market through 2032, revealing a steady compound annual growth rate of 3.8%. This measured yet resilient expansion reflects the enduring centrality of iron ore in the global steel value chain, even as the industry confronts decarbonization pressures, new supply entrants, and fluctuating demand patterns from major steel-producing regions. The research underscores that 2026 will not be a year of radical disruption but rather one of strategic repositioning, where winners will be defined by their ability to secure high-grade supply, optimize logistics, and adapt to tightening environmental standards.
Worldwide Iron Ore Trade Market
The Strategic Value of Forward-Looking Market Intelligence
In an environment where iron ore benchmark prices have hovered between $100–107 per tonne in early 2026, volatility remains a constant. New supply from major projects is beginning to influence trade flows, while Chinese demand — which continues to dominate global seaborne receipts — shows nuanced shifts in preference for product specifications. For corporate leaders, mining executives, traders, and steel strategists, this report provides the analytical clarity needed to move beyond reactive hedging toward proactive portfolio optimization.
Worldwide Iron Ore Trade Market
The study’s primary value lies in its ability to contextualize near-term decisions within a longer-term trajectory. Whether evaluating capital allocation for mine expansions, negotiating long-term offtake agreements, assessing M&A opportunities in the seaborne trade space, or stress-testing supply chain resilience against geopolitical risks, the research equips stakeholders with scenario-based frameworks grounded in rigorous modeling. By 2026, companies that integrate these insights into their planning cycles will hold a measurable edge in an increasingly concentrated and competitive marketplace.
Market Dynamics Shaping the 2026 Outlook
The iron ore trade sector continues to demonstrate remarkable resilience despite multiple headwinds. Global production is projected to reach approximately 2.73 billion tonnes in 2026, up from 2.61 billion tonnes the previous year, fueled by capacity expansions in Australia, Brazil, and the gradual ramp-up of new supply sources. Yet this growth is not uniform. The market remains heavily dependent on a small number of dominant exporters, with Australia and Brazil together accounting for the vast majority of seaborne supply.
Regulatory and sustainability pressures are accelerating. The achievement of IRMA 75 certification by a major producer sets a new benchmark for responsible mining practices, signaling that environmental, social, and governance (ESG) credentials are rapidly transitioning from optional differentiators to commercial necessities in international trade. Buyers, particularly in Europe and among leading Asian steelmakers, are placing increasing weight on traceable, low-carbon iron ore in their procurement decisions.
Geopolitical factors further complicate the picture. Concentrated trade flows, ongoing logistical challenges in certain exporting regions, and the potential for policy shifts in major importing nations create both risks and opportunities. The report meticulously examines these dynamics, offering nuanced perspectives on how shifting alliances, infrastructure bottlenecks, and evolving trade policies could reshape seaborne routes and pricing mechanisms over the coming years.
Comprehensive Coverage: What the Report Delivers
This research goes far beyond desktop analysis. It provides an integrated view of the entire iron ore trade ecosystem, combining granular supply-side modeling with demand-side intelligence across key steelmaking applications. The study dissects the market by product form — fines, lumps, and pellets — revealing distinct performance characteristics, pricing premiums, and customer preferences that are critical for positioning strategies.
Regional trade flow analysis forms a cornerstone of the report. It maps evolving import dependencies, port infrastructure developments, and maritime logistics trends that directly impact delivered costs and contract negotiations. Particular attention is given to the interplay between captive mining operations and merchant trade, as integrated steel producers recalibrate their external procurement needs.
One of the report’s most practical components is its detailed competitive landscape assessment. Drawing on proprietary data and extensive primary research, the study profiles the strategic priorities, production capabilities, expansion pipelines, and trade tactics of the world’s leading iron ore participants. This includes in-depth evaluation of:
- Vale S.A. (Rio de Janeiro, Brazil): A dominant force in global seaborne trade, leveraging its Brazilian operations to supply high-grade iron ore and pellets to steelmakers across multiple continents, with ambitious production targets set for 2026.
- Rio Tinto (London, with core operations in Australia): The Pilbara giant continues to refine its operational efficiency while advancing the Simandou project in Guinea. The company’s recent restructuring into dedicated product groups, including a focused Iron Ore division, signals sharper execution in trade activities. The first export cargo from Simandou in late 2025 marks a significant milestone in diversifying high-grade supply sources.
- BHP Group Limited (Melbourne, Australia): Renowned for its large-scale, low-cost Pilbara operations, BHP maintains its position as a cornerstone supplier to Asian markets, emphasizing volume, reliability, and continuous productivity improvements.
- Fortescue Metals Group Ltd. (Perth, Australia): Demonstrating strong momentum with record shipments and cost reductions in 2025, Fortescue is expanding its role in the seaborne trade market through disciplined capacity growth in Western Australia.
- Anglo American plc (London, UK): Through its Kumba operations in South Africa, the company supplies premium lump and fines products. Its leadership in responsible mining certification strengthens its appeal to ESG-focused customers.
Additional profiles examine the distinct strategies of ArcelorMittal, Cleveland-Cliffs Inc., NMDC Limited, LKAB, Metalloinvest, Ferrexpo plc, and Mineral Resources Limited. Each company assessment integrates recent developments, capital expenditure plans, sustainability roadmaps, and trade flow patterns to provide a three-dimensional view of competitive positioning.
The report further explores critical industry themes including the accelerating adoption of direct reduced iron (DRI) technologies, the evolving role of pellets in decarbonization pathways, infrastructure bottlenecks in key export basins, and the potential impact of emerging supply from West Africa. It also addresses how steel industry consolidation and the rise of electric arc furnace steelmaking are subtly reshaping long-term iron ore specifications and procurement strategies.
Why 2026 Represents a Pivotal Decision Window
The convergence of several factors makes the 2026–2028 period particularly consequential for industry participants. New high-grade supply from projects such as Simandou is expected to add meaningful volume to the seaborne market, potentially exerting downward pressure on premiums while offering steelmakers new options for lower-carbon feedstocks. Simultaneously, major producers are optimizing their portfolios, as evidenced by Vale’s targeted production range of 340–360 Mt and Fortescue’s continued focus on cost leadership.
Against this backdrop, the report’s scenario modeling and sensitivity analysis become indispensable tools. It enables executives to quantify the potential impact of various price trajectories, supply disruptions, demand shocks, and regulatory changes on their operations and investment cases. The research also highlights latent opportunities in emerging trade corridors, product innovation (particularly around pelletizing and beneficiation), and strategic partnerships that can secure priority access to preferred material.
Market concentration remains elevated, with the top three players accounting for a substantial share of global trade and the top five extending that dominance further. This reality amplifies the importance of differentiated strategies — whether through quality premiums, logistical superiority, sustainability leadership, or vertical integration.
From Insight to Implementation: A Practical Strategic Framework
Unlike many industry studies that conclude with high-level observations, PW Consulting’s research is explicitly designed for translation into boardroom decisions. It includes practical frameworks for supply contract design, portfolio stress testing, capital deployment prioritization, and competitive response planning. The report’s forecasting methodology integrates macroeconomic variables, steel production outlooks, environmental policy trajectories, and mine-by-mine capacity modeling to deliver robust, defensible projections.
Readers will find detailed appendices covering trade flow matrices, pricing correlation analysis, sustainability benchmarking, and risk registers — all calibrated to support immediate application in strategic planning cycles.
The iron ore trade market in 2026 will reward those who combine operational excellence with strategic foresight. PW Consulting’s Worldwide Iron Ore Trade Market research provides the independent, authoritative intelligence necessary to excel in this environment. It strips away noise to reveal structural trends, highlights emerging pressure points before they become crises, and illuminates pathways to sustainable value creation in one of the world’s most vital industrial supply chains.
For leaders tasked with navigating these complexities, the report represents more than market data — it constitutes a strategic asset. Those seeking the complete dataset, full competitive benchmarking, granular scenario modeling, and proprietary trade flow visualizations are invited to access the full study on the PW Consulting website. In a market where information truly equates to competitive advantage, this research delivers the clarity required to make confident, informed decisions that will shape corporate performance for years to come.
(Word count: 1,378)
For detailed analysis of this topic, please visit the official page:Worldwide Iron Ore Trade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek