
Strategic Imperatives in the Global Photocuring Printer Market: Why 2026 Will Be a Pivotal Decision Window
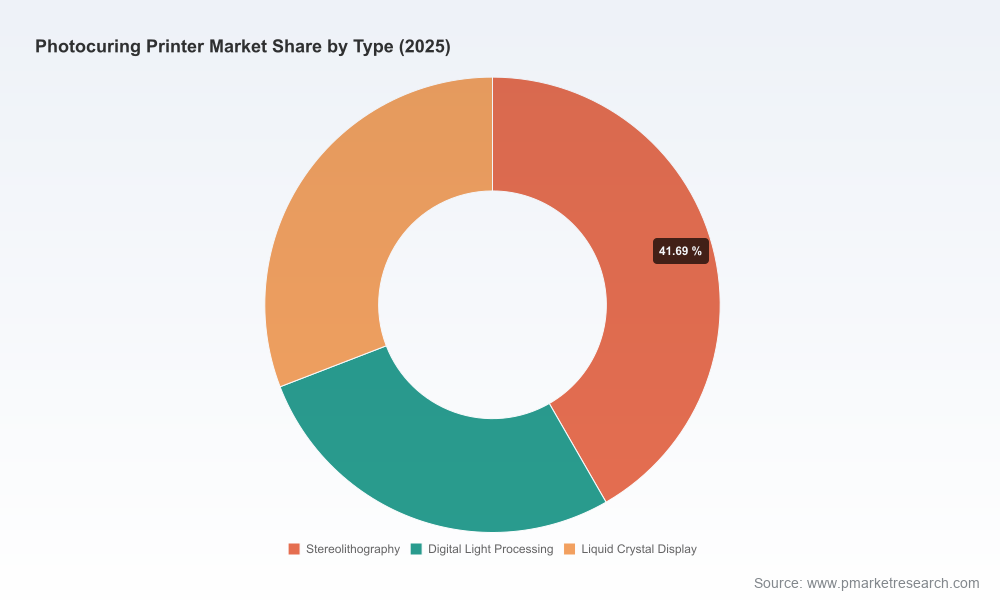
The photocuring printer industry, encompassing Stereolithography (SLA), Digital Light Processing (DLP), and Liquid Crystal Display (LCD) technologies, stands at the threshold of transformative growth. As organizations across manufacturing, healthcare, and design sectors accelerate their adoption of vat photopolymerization additive manufacturing, the Worldwide Photocuring Printer Market is projected to expand at a robust compound annual growth rate of 17.62% from 2026 through 2032. This momentum builds upon a market that has already grown from USD 2,050.4 million in 2020 to an estimated USD 4,580.6 million in 2025, reflecting the technology’s transition from prototyping tool to production-grade solution.
Worldwide Photocuring Printer Market
For enterprise leaders and investors, the 2026–2032 period represents far more than incremental market expansion. It marks a critical inflection point where technology maturity, regulatory standardization, and competitive consolidation will determine long-term winners. Our latest comprehensive market research delivers precisely the strategic intelligence required to navigate this complexity, offering not abstract forecasts but actionable frameworks that directly inform capital allocation, partnership strategies, and technology roadmaps.
Worldwide Photocuring Printer Market
The Compelling Case for Photocuring Technology Adoption
Photocuring 3D printing has evolved beyond its origins in rapid prototyping to become a cornerstone of high-precision, high-throughput manufacturing. The technology’s ability to deliver exceptional surface finish, fine feature resolution, and material versatility has driven adoption across diverse end-use applications. From dental and medical device production to jewelry design, automotive and aerospace components, consumer electronics, and education and research initiatives, organizations are leveraging photocuring systems to compress development cycles and unlock geometries impossible with traditional subtractive methods.
Worldwide Photocuring Printer Market
This expansion is underpinned by continuous innovation in both hardware and materials. Recent product launches demonstrate the industry’s focus on scaling production efficiency. Large-frame systems with expanded build volumes, multi-laser architectures, and specialized resins tailored for investment casting and high-performance applications are redefining throughput capabilities. At the same time, advancements in proprietary photocuring processes, such as ultrafast lubricant sublayer photocuring, are addressing previous limitations in speed and post-processing requirements.
Yet beneath this growth narrative lies increasing market concentration. The top three players command approximately 38.4% of the global market, while the top five account for over 52%, signaling an environment where scale, ecosystem depth, and technological differentiation will increasingly separate leaders from followers. Understanding these dynamics is essential for any organization seeking to either compete directly or strategically partner within the ecosystem.
What the Research Delivers: A Practical Decision-Making Toolkit
This market study is engineered as a comprehensive strategic reference for 2026 decision cycles. Rather than offering generic industry commentary, the report provides layered intelligence across four critical dimensions that directly impact enterprise strategy.
First, it presents a detailed examination of market dynamics, integrating the effects of evolving international standards and regulatory frameworks. The recent ISO/ASTM 52940:2025 standard on characterization of ceramic slurry feedstock materials, alongside ongoing work by ISO/TC 261 on environment, health, safety, and quality management requirements (including ISO 13485 compliance for medical applications), is reshaping procurement criteria and certification pathways. These developments are not peripheral considerations; they are becoming central to supplier selection and risk management protocols.
Second, the research delivers granular segmentation analysis across technology types, applications, and geographic markets. This enables executives to identify specific growth vectors and align investment priorities with the highest-potential opportunities. The analysis reveals how different photocuring approaches—SLA for large-format industrial applications, DLP for precision and speed, and LCD for cost-effective professional use—compete and complement each other across verticals.
Third, the competitive landscape section provides in-depth profiles of the most influential market participants. These are not simple company overviews but strategic assessments of technological positioning, go-to-market approaches, and innovation trajectories. The analysis covers industry pioneers and emerging challengers alike, creating a clear map of the competitive battlefield.
Key Players Defining the Competitive Arena
3D Systems continues to set the benchmark for industrial SLA technology. The company’s recent introduction of the SLA 825 Dual system—with its significantly expanded build volume, dual-laser architecture, and new materials optimized for investment casting—reinforces its leadership in high-throughput applications for motorsports, aerospace, and service bureaus. Their focus on both hardware and advanced resin formulations creates a formidable ecosystem barrier.
Formlabs has successfully scaled professional SLA technology from desktop to large-format systems. The Form 4 series and its extensive resin portfolio have established the company as the dominant supplier in professional and dental markets. Their integrated approach to hardware, software, and materials has proven particularly effective in democratizing high-resolution photocuring for both prototyping and production applications.
UnionTech represents the rising strength of Chinese industrial manufacturers. With a significant share of the global SLA market, the company has expanded its portfolio with large-format RSPro systems and multi-laser platforms. Recent launches, including the RSPro800 X four-laser system and RA900 industrial platforms showcased at major trade events, target demanding applications in automotive prototyping, investment casting, and tire mold manufacturing. Their aggressive innovation timeline signals intensifying global competition.
Nexa3D has carved a distinctive position through its Lubricant Sublayer Photocuring (LSPc) technology, which dramatically improves print speeds and production economics. This approach addresses one of the traditional limitations of resin-based additive manufacturing, positioning the company strongly in applications where throughput is paramount.
European specialist Prodways maintains leadership in DLP and MovingLight technologies, with particular strength in high-precision investment casting, ceramics, and dental applications. Their recent advancements in silica-loaded photocurable slurries demonstrate continued material science innovation that enhances the performance ceiling of photocuring processes.
Additional significant players include ACME3D and Kings 3D Printing Technology from China, both focusing on large-format industrial systems; Stratasys through its Origin DLP platform targeting production-grade resin parts; Asiga with its specialized dental and jewelry DLP systems; RAYSHAPE with its focus on digital dentistry; and Prismlab, which brings proprietary polymer formulation expertise to the market. The strategic positioning, partnerships, and technology roadmaps of these companies will materially influence supply chain decisions and technology selection through the end of the decade.
Navigating the 2026 Decision Landscape
The coming year represents a unique strategic window. Organizations must simultaneously address several converging forces: accelerating technological capability, tightening regulatory requirements, shifting competitive intensity, and evolving customer expectations for sustainable and certifiable production methods.
Our research equips decision-makers with the necessary frameworks to answer critical questions. How should capital expenditure be allocated between different photocuring technologies? Which emerging applications offer the highest return on investment? How can organizations build resilient supply chains in an increasingly concentrated vendor environment? What partnership and acquisition strategies will secure competitive advantage as the market consolidates?
The analysis extends beyond current market conditions to identify latent opportunities and potential disruption vectors. It examines how photocuring technology is intersecting with broader Industry 4.0 initiatives, the implications of material science breakthroughs, and the evolving role of these systems in distributed manufacturing models.
From Intelligence to Actionable Advantage
In an industry characterized by rapid innovation and high strategic stakes, access to timely, accurate, and strategically framed market intelligence is not merely advantageous—it is essential. This research transforms complex market dynamics into clear strategic pathways, enabling executives to move from reactive adaptation to proactive market leadership.
The report’s value lies in its dual nature: it provides sufficient depth and rigor to validate strategic hypotheses while deliberately preserving the most sensitive granular data, competitive benchmarks, and forward-looking scenarios for those who access the complete study. This approach ensures that organizations making multi-million-dollar technology and partnership decisions in 2026 do so with complete situational awareness.
As the photocuring printer market approaches USD 14 billion by 2032, the decisions made in the next 12–18 months will likely determine competitive positioning for the remainder of the decade. Whether your organization is a current participant, potential entrant, investor, or end-user seeking to optimize its additive manufacturing strategy, this research offers the contextual intelligence and analytical frameworks necessary to make high-conviction decisions.
The complete Worldwide Photocuring Printer Market research is now available. It contains the full dataset, detailed forecasting models, comprehensive competitive benchmarking, and strategic recommendation matrices developed through months of primary research and advanced analytics. Access the full report to transform these market insights into your organization’s decisive competitive advantage.
Word count: 1,378
For detailed analysis of this topic, please visit the official page:Worldwide Photocuring Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek