
Strategic Fueling of the Future: Navigating the Replenishment At Sea System Market in 2026
In an era where maritime superiority is increasingly defined by endurance and logistical autonomy, the Replenishment At Sea (RAS) System Market stands as a critical enabler of global naval and commercial maritime strategy. As defense budgets recalibrate and operational mandates expand, the ability to transfer fuel, munitions, and stores while underway is no longer a tactical convenience—it is a strategic imperative. Our latest comprehensive research, “Replenishment At Sea (RAS) System Market: Strategic Outlook 2026–2032,” delivers the analytical rigor and actionable intelligence required to navigate this complex landscape. Designed specifically for executive decision-makers, procurement leaders, defense planners, and maritime technology investors, this study translates historical trends, macroeconomic pressures, and technological shifts into a forward-looking framework that directly informs capital allocation, vendor selection, and capability road-mapping through 2032.
Replenishment At Sea (RAS) System Market
The period from 2026 onward will not be defined by incremental upgrades, but by structural transformation. Fleets are operating farther from home ports, joint interoperability requirements are tightening, and environmental and safety regulations are demanding higher precision in underway logistics. Against this backdrop, understanding where capital will flow, which technological pathways will dominate, and how competitive forces will realign is essential. This article outlines the strategic architecture of our research, previews the operational depth it covers, and clarifies how the findings will shape enterprise decisions in the coming planning cycles.
Replenishment At Sea (RAS) System Market
Market Architecture: A Structurally Resilient Ecosystem Reaching Motion in 2026
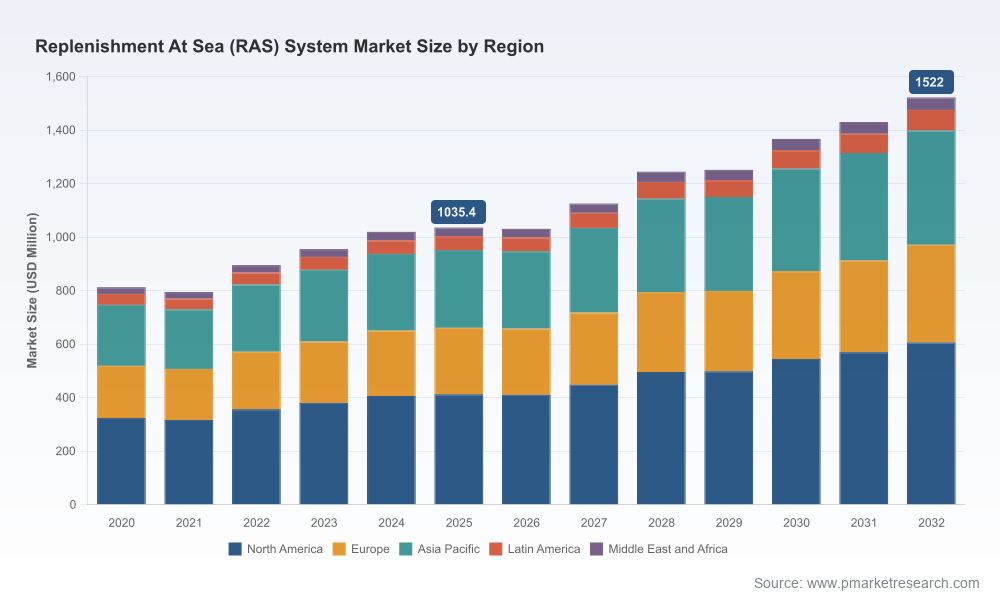
The RAS market has demonstrated remarkable resilience through cyclical procurement shifts, operational pivots, and supply chain recalibrations. Tracking revenue trajectories from 2020 through 2025 reveals a clear pattern: initial contraction gave way to steady recovery, culminating in a mature baseline that sets the stage for a decisive growth phase. The data positions 2026 not as a peak, but as a transitional inflection point, where baseline stabilization clears the way for a sustained expansion arc. By the close of the forecast window, the market is projected to surpass its current revenue footprint by a meaningful margin, reflecting accelerated procurement cycles, newer vessel classes entering service, and broader adoption of integrated transfer architectures across allied and regional navies.
Replenishment At Sea (RAS) System Market
The projected compound annual growth rate of 5.65 percent through 2032 underscores a market that is neither speculative nor fragile, but anchored in tangible operational demand and long-cycle defense industrial planning. This trajectory is reinforced by multi-year funding commitments, fleet modernization programs, and the growing recognition that logistical self-sufficiency directly translates into operational freedom. From a strategic standpoint, this growth profile signals a market entering a phase where early positioning, standardized interoperability, and technology integration will dictate competitive advantage. Decision-makers who align procurement timelines, partnership strategies, and capability investments with this rhythm will be better equipped to secure supply continuity, influence specification roadmaps, and capture share in a consolidating landscape.
Core Research Dimensions: What the Study Delivers for 2026 Decision-Makers
This research is engineered to move beyond descriptive market sizing and into operational utility. The report maps the RAS ecosystem across the dimensions that matter most to procurement, engineering, and strategy teams. Each section is structured to support clarity in specification writing, vendor evaluation, and long-range capability planning.
- A comprehensive segmentation framework that separates systems by functional type, enabling stakeholders to isolate growth vectors in liquid transfer, dry cargo handling, and solid stores logistics without getting lost in aggregated averages.
- An application-led analysis that distinguishes fleet support architectures, auxiliary vessel operations, and joint logistics environments, highlighting where mission profiles will drive specification divergence and where standardization will create economies of scale.
- A regional demand mapping that identifies where procurement momentum, fleet replacement cycles, and allied capability investments are converging, providing context for international sourcing, partnership localization, and market entry considerations.
- A technology and integration review that examines automation readiness, tension control systems, hose and probe architectures, and the growing intersection of RAS equipment with broader combat support and logistics digitalization efforts.
- A regulatory and standards overlay that contextualizes operating procedures, safety protocols, and compliance expectations shaping both new builds and retrofit programs.
Each dimension is supported by primary triangulation, secondary verification, and scenario-based interpretation, so readers can distinguish between cyclical noise and structural shifts. The study does not simply report where the market stands; it identifies the decision points that will determine where it goes next.
Competitive Landscape: Strategic Positioning Among Pioneers and Specialists
The RAS market is defined by a blend of specialist manufacturers with decades of domain expertise and larger maritime technology integrators that bring cross-system interoperability and global delivery capacity. Competitive dynamics in this space are shaped not only by product performance, but by engineering responsiveness, compliance with naval standards, geographic proximity to key fleets, and the ability to support long-lifecycle maintenance and upgrade programs.
Van Halteren Technologies has established itself as a provider of advanced liquid and solid RAS solutions, with a track record that includes custom configurations for major combat support and replenishment vessels. Its recent selection by Damen Naval for the Anti-Submarine Warfare Frigate programme illustrates how RAS capabilities are being embedded earlier in platform design cycles, reinforcing the importance of early supplier integration and specification influence.
Kongsberg Maritime continues to expand its footprint in electric RAS and fuelling-at-sea equipment, supplying winches, high points, and mast systems for navies pursuing modernization and electrification pathways. The sequence of recent contract awards, including equipment deliveries for Indian Navy Fleet Support Ships and Portuguese replenishment and logistic vessels, highlights a pattern of sustained demand tied to fleet support ship programs and the broader electrification of underway transfer systems.
Hepburn Engineering brings long-standing experience in single-purpose and dual solids/liquids RAS configurations, with a strong alignment to the Standard Tensioned Replenishment Alongside Method. In a market where operational safety, repeatability, and procedural compliance are paramount, this specialization positions the company well for navies that prioritize standardized replenishment methodologies and proven hardware maturity.
Hydrasearch Company focuses on the fluid conveyance layer of underway replenishment, manufacturing hoses, probes, and hardware that form the physical and operational backbone of fuel and store transfer. Its defense-oriented engineering emphasis reflects the reality that RAS performance is often determined not only by large structural systems, but by the reliability and interoperability of the conveyance components that connect them.
KMT Submarine rounds out the competitive field as a leading manufacturer of underway replenishment equipment spanning fuel, munitions, stores transfer, and vertical replenishment. Its broad component and system scope reinforces the growing expectation that modern replenishment architectures must support multi-mission logistics rather than single-stream transfer.
Across this competitive field, market concentration remains moderate, with a meaningful share still distributed among specialized incumbents and regional suppliers. That structure suggests both opportunity and risk: opportunity for firms that can differentiate through integration, lifecycle support, and standards alignment, and risk for those that rely solely on legacy positioning without adapting to evolving platform requirements and electrification trends.
Market Dynamics: Forces Shaping Demand, Compliance, and Procurement Timing
Several converging forces are reshaping how RAS capabilities are specified, funded, and deployed. Understanding these dynamics is essential for anticipating procurement timing, negotiating contract structures, and aligning technology roadmaps with operational expectations.
Standardization as a Procurement Anchor
Standardized procedures for underway replenishment have become a central reference point for equipment design and operational training. Published naval guidance continues to define equipment requirements, safety protocols, and procedural expectations that govern RAS evolutions. For suppliers and fleet operators alike, alignment with these standards is no longer optional; it is a baseline expectation that influences qualification cycles, integration risk, and long-term supportability. This creates a market environment where compatibility, repeatability, and procedural discipline carry strategic weight alongside raw performance metrics.
Fleet Architecture and the Rise of Dedicated Support Vessels
Naval modernization programs are increasingly paired with dedicated replenishment and logistics platforms, extending the operational range of surface fleets and reducing dependency on port infrastructure. Multi-year procurement intentions for large fleet replenishment oilers and support ships indicate sustained demand for integrated RAS and fuelling systems over the forecast horizon. For decision-makers, this translates into a market where platform availability, delivery scheduling, and capability pairing become as important as individual equipment specifications. Supply chain readiness, production slot allocation, and lead-time transparency will play an outsized role in determining execution risk.
Allied Capability Investments and Expeditionsary Reach
European allies and partner navies are increasing investment in replenishment capabilities as part of broader efforts to strengthen operational autonomy and expeditionary reach. This shift is driven by evolving maritime security requirements, extended mission profiles, and the need to sustain presence without over-reliance on host-nation logistics. The resulting demand environment favors suppliers who can support multi-national interoperability, provide configurable solutions across vessel classes, and deliver training and sustainment packages that accelerate fielding.
Who Should Use This Report and How It Will Shape 2026 Decisions
This study is designed for a focused audience: defense procurement executives, maritime system integrators, naval logistics planners, technology investors with exposure to shipboard systems, and strategic advisors supporting fleet modernization programs. Its value lies not in presenting a static snapshot, but in providing a decision architecture that connects market structure to actionable choices.
- Procurement leaders can use the segmentation and application analysis to refine specification priorities, reduce integration risk, and identify where dual-purpose or modular configurations may lower total lifecycle cost.
- Engineering and program managers can align platform upgrade roadmaps with emerging electrification, automation, and tension-control trends, ensuring that retrofit and new-build decisions are synchronized with market direction.
- Commercial and partnership teams can assess where concentration, specialization, and recent contract awards indicate where incumbency is strongest and where differentiated offerings may gain traction.
- Investors and market strategists can use the growth trajectory, competitive concentration context, and demand drivers to evaluate where capital deployment, M&A attention, and regional expansion may produce the strongest risk-adjusted returns.
Crucially, the report is structured to help organizations avoid two common pitfalls: overreacting to short-term procurement announcements and underestimating the cumulative impact of standards alignment, platform replacement cycles, and allied capability investment. By separating signal from noise, the study provides a defensible basis for multi-year planning.
Strategic Outlook: Positioning for the Next Cycle of Underway Logistics
The RAS market is entering a phase where operational demand, technology evolution, and procurement discipline will jointly determine competitive outcomes. Growth will not be uniform across every segment or application; it will concentrate where mission requirements are expanding, where fleet support architectures are being refreshed, and where standardization and electrification intersect to create clearer paths to integration. In that environment, the organizations that gain advantage will be those that treat replenishment not as a discrete equipment purchase, but as a functional component of broader logistics endurance and interoperability strategy.
Our full research release provides the detailed segmentation intelligence, scenario-tested forecasts, competitive mapping, and operational context required to act on this outlook. Because the strategic value of this market lies in its specifics—the relative weight of different transfer types, the regional pacing of demand, the application-level dynamics, and the evolving concentration of share—this article intentionally previews the analytical framework rather than disclosing the full quantitative breakdown. The complete dataset, company-level implications, and forward-looking recommendations are available in the full report, where decision-makers can access the granularity needed to translate market structure into procurement, investment, and partnership decisions.
For executive teams preparing for the 2026 planning cycle, the message is clear: underway replenishment is moving from a support function to a strategic capability domain. Those who understand the structural drivers now will be better positioned to secure capability continuity, influence specification outcomes, and navigate a market that is growing with purpose rather than volatility.
For detailed analysis of this topic, please visit the official page:Replenishment At Sea (RAS) System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek