
High Purity Alumina Sol Market Strategic Intelligence 2026: Navigating the Nano-Dispersion Boom
The global industrial landscape is undergoing a profound transformation driven by material science advancements, electrification, and the relentless pursuit of higher performance in chemical applications. At the center of this shift lies High Purity Alumina Sol, a critical nano-dispersion of aluminum oxide that serves as a foundational enabler for next-generation technologies. As we step into 2026, corporate strategists, supply chain directors, and R&D leaders face a complex environment defined by rapid market expansion, shifting raw material economics, and an intensely competitive vendor landscape. This article outlines the strategic imperatives of the current high purity alumina sol market and introduces a comprehensive research framework designed to equip decision-makers with the actionable intelligence needed to secure competitive advantage in the years ahead.
High Purity Alumina Sol Market
A Market Accelerating at Double-Digit Velocity
The trajectory of the high purity alumina sol market has moved decisively beyond incremental growth. Historical tracking from 2020 through 2025 reveals a consistent upward curve, with industry revenue climbing from approximately 75.4 million USD in 2020 to 140.0 million USD by the 2025 base year. This progression reflects a compound annual growth rate of roughly 14.0 percent, underscoring the material's expanding relevance across advanced coatings, catalyst systems, precision ceramics, and electronics manufacturing. The momentum is not stalling; rather, forecasting models project the market to reach 155.95 million USD in 2026 and continue its steep ascent toward 350.32 million USD by 2032. Such sustained expansion signals that high purity alumina sol is transitioning from a niche specialty chemical to a mainstream industrial input with broad economic leverage.
High Purity Alumina Sol Market
Understanding this macro trajectory is only the first layer of strategic insight. What truly differentiates market leaders from followers is the ability to dissect the underlying drivers, anticipate inflection points, and align procurement, production, and partnership strategies accordingly. The next phase of growth will be shaped by regional supply-demand balances, evolving application specifications, and raw material cost dynamics that are already reshaping procurement calculus across the value chain. For organizations operating in or adjacent to this space, relying on top-line figures alone is insufficient. Granular intelligence on volume shifts, pricing architectures, and competitive positioning is essential.
High Purity Alumina Sol Market
Strategic Pillars of the 2026 Market Research Report
Comprehensive Market Architecture and Forecasting Framework
The forthcoming High Purity Alumina Sol Market research report is engineered to deliver more than retrospective analysis. It provides a rigorous, multi-dimensional view of the market's structure, covering historical performance from 2020 through 2025 and extending forward-looking forecasts through 2032. By anchoring insights in verified revenue trajectories and applying scenario-based modeling, the report equips stakeholders to stress-test their strategic assumptions against multiple growth pathways. Readers will gain access to detailed breakdowns of market volume and value trends, allowing them to pinpoint where demand is consolidating and where latent opportunities remain untapped.
Crucially, the report avoids superficial aggregations. It maps the interplay between product types, regional supply ecosystems, and application-driven consumption patterns, giving executives a clear lens through which to evaluate their market exposure. Rather than presenting static snapshots, the analysis emphasizes dynamic shifts, helping teams anticipate how changing end-use requirements and feedstock economics will reshape competitive benchmarks over the forecast period.
Deep-Dive Segmentation Analysis
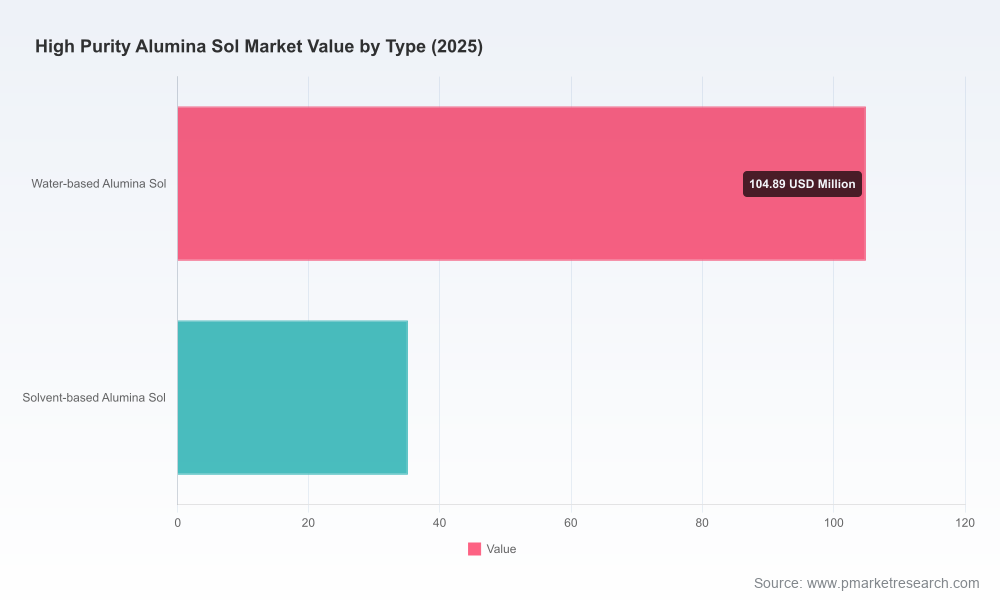
Segment-level intelligence forms the backbone of effective market positioning. The report examines the high purity alumina sol landscape through multiple segmentation lenses, including product formulation categories and application verticals. On the product side, the analysis differentiates between water-based and solvent-based alumina sol variants, exploring how each formulation addresses distinct processing constraints, performance thresholds, and regulatory considerations. Understanding the relative market positioning of these types allows manufacturers and buyers to align their technical specifications with the most viable supply options.
On the application front, the research dissects consumption patterns across key end-use sectors, from lithium-ion battery separators and catalyst support systems to precision ceramics, semiconductors, and electronics. Each vertical carries unique purity requirements, dispersion stability demands, and scalability expectations. The report maps these nuances to reveal which applications are driving volume growth, which are acting as margin anchors, and where emerging technical standards may open new doors for specialized suppliers. By focusing on the interplay between application engineering and material performance, the analysis helps stakeholders identify cross-selling opportunities and prioritize R&D investments with higher confidence.
Competitive Landscape Mapping: Who Shapes the Market
The competitive architecture of the high purity alumina sol market is defined by a mix of established multinational chemical players and highly specialized regional manufacturers. A core cohort of firms commands significant influence, and the report provides detailed profiling of these key companies to illuminate their strategic footprints, product portfolios, and regional strengths.
- Nissan Chemical (Japan) maintains a prominent position by offering high purity alumina sol as nano dispersions tailored for coatings, catalysts, and precision applications, reflecting a sustained commitment to advanced material engineering.
- Sasol Performance Chemicals (South Africa) supplies a broad range of high purity alumina sol grades targeting catalyst carriers, advanced ceramics, coatings, and specialty chemical uses, leveraging its integrated chemical infrastructure to serve diverse industrial needs.
- Nyacol Nanotechnologies (USA) specializes in colloidal dispersions, including high purity alumina sol formulations optimized for coatings and performance materials, positioning itself as a technical solutions provider rather than a commoditized bulk supplier.
- Wesbond (USA) focuses on refractory and ceramic binding systems, addressing niche but high-value application requirements where dispersion consistency and thermal stability are paramount.
- Kawaken Fine Chemicals (Japan) and JGC Catalysts and Chemicals (Japan) both contribute to the market by supplying high purity alumina sol for catalyst and ceramic precursor applications, reinforcing Japan's strong tradition in fine chemical and catalyst support technologies.
- A robust contingent of Chinese manufacturers, including Zibo Jiarun, Hangzhou Veking, Zibo Jinqi, Beijing Yataiaohua, and Zibo Senchi, has expanded production capacity and application coverage across refractory coatings, ceramic treatment, industrial binding, and specialty coatings, reflecting the region's growing influence in both volume supply and cost-competitive segments.
Market concentration metrics underscore the strategic weight of leading participants. The report highlights a competitive environment where the top three players hold a consolidated share of approximately 54.2 percent, while the top five collectively account for around 72.8 percent of market revenue. This structure indicates that scale, technological differentiation, and supply reliability remain critical barriers for new entrants, while incumbent players enjoy meaningful leverage in pricing, long-term contracts, and innovation partnerships. The competitive analysis section of the report goes beyond firm profiles to examine how these players are positioning themselves against shifting raw material costs, regional demand patterns, and evolving customer specifications.
Raw Material Economics and Supply Chain Implications
The high purity alumina sol value chain is intimately tied to the economics of its primary feedstock: aluminum hydroxide. Recent market intelligence reveals notable regional divergence in aluminum hydroxide pricing, creating both challenges and tactical opportunities for producers and purchasers. In March 2026, aluminum hydroxide prices in Northeast Asia reached approximately 0.24 USD per kilogram, representing a 17.2 percent decline from December 2025 levels. This drop reflects weakened downstream demand and excess inventory accumulation, conditions that could compress producer margins if not managed strategically but may also offer cost advantages for buyers with flexible procurement timelines.
European markets displayed a more moderate trajectory, with aluminum hydroxide prices settling around 0.63 USD per kilogram in March 2026, a 3.1 percent decline from the end of 2025. The softening was linked to reduced demand in flame retardant formulations and construction-related applications. Meanwhile, North America demonstrated greater price resilience, with aluminum hydroxide quoted near 0.59 USD per kilogram as of March 2026, supported by steady consumption from flame retardants and specialty chemical end-users despite upstream variability.
At the macro level, the global aluminum hydroxide market was valued at approximately 12.75 billion USD in 2025 and is projected to reach 13.28 billion USD in 2026. Because aluminum hydroxide serves as a foundational precursor for high purity alumina sol production through controlled hydrolysis or peptization processes, fluctuations in feedstock pricing and availability directly influence production economics, grade consistency, and supply reliability. The research report integrates these raw material dynamics into its market analysis, helping readers assess cost pressure vectors, evaluate supplier risk exposure, and develop procurement strategies that balance price sensitivity with quality assurance.
Real-World Application Trends Driving Demand
Beyond input costs and competitor mapping, the most decisive force shaping the high purity alumina sol market is the evolving technical demands of end-use industries. Lithium-ion battery separator coatings continue to represent a dominant application driver, as manufacturers seek materials that enhance thermal stability, mechanical strength, and electrochemical performance in next-generation cells. Catalyst and support applications remain a vital consumption channel, with high purity alumina sol providing the dispersion characteristics needed for efficient catalytic surfaces and carrier structures. Precision ceramics and advanced coating systems likewise depend on high-purity dispersions that enable tighter tolerances, improved surface finishes, and enhanced durability in demanding environments.
In the semiconductor and electronics sector, the push toward miniaturization, higher thermal management requirements, and cleaner manufacturing environments is elevating the role of specialty alumina sol formulations. Each of these verticals is subject to distinct performance benchmarks, qualification cycles, and regulatory frameworks, meaning that a uniform market strategy is rarely effective. The report dissects these application-specific dynamics to reveal where specification upgrades are creating premium pricing opportunities, where volume scaling is compressing margins, and where cross-industry technology transfer could unlock new use cases.
Why This Research Matters for 2026 Decision-Making
Aligning Strategy with Market Realities
The 2026 market environment demands more than reactive planning. Companies must anticipate how feedstock volatility, regional supply shifts, and application specification changes will interact to reshape competitive benchmarks. The research report is designed to support this forward-looking posture by translating macro trends into operational implications. It helps procurement teams evaluate contract structures in light of raw material price trajectories, enables R&D leaders to prioritize formulation development against the most promising application segments, and guides executive teams in assessing partnership, acquisition, or capacity expansion opportunities with greater clarity.
Navigating Concentration and Competitive Intensity
With a market structure where leading firms hold substantial share, strategic differentiation becomes essential. The report analyzes how top players are leveraging technical expertise, regional presence, and product breadth to maintain positioning, and it identifies the vulnerabilities and openings that less dominant participants can exploit. Whether an organization is a producer seeking to expand its footprint, a distributor evaluating supplier portfolios, or a downstream manufacturer optimizing material sourcing, understanding the competitive map is critical to avoiding margin erosion and capturing share in higher-value niches.
Turning Raw Material Signals into Advantage
The recent divergence in aluminum hydroxide pricing across Northeast Asia, Europe, and North America illustrates how regional market conditions can create asymmetric advantages for nimble organizations. By incorporating these real-time signals into a structured analytical framework, the research enables stakeholders to time procurement decisions more effectively, hedge against localized supply disruptions, and exploit cost differentials where logistics and quality requirements permit. In an environment where input costs can shift meaningfully within a single quarter, the ability to read and act on raw material intelligence is a strategic asset.
From Insight to Action: What the Report Delivers
Beyond high-level market characterization, the report provides practical, decision-ready artifacts that bridge analysis and execution. Readers will find detailed segmentation breakdowns, competitive profiling, application-specific consumption analysis, and forward forecasts calibrated to multiple scenario assumptions. The content is structured to support internal briefings, investment committee discussions, product roadmap planning, and supply chain realignment efforts. By focusing on actionable intelligence rather than abstract market commentary, the report empowers teams to translate findings into concrete strategies, whether that means adjusting product mix, negotiating supplier agreements, or entering new application segments with confidence.
Conclusion: Positioning for the Next Phase of Growth
The high purity alumina sol market is entering a period of sustained expansion underpinned by technological demand, material performance requirements, and evolving production economics. With a clear growth trajectory extending from the 2025 base year through 2032, organizations that invest in precise, forward-looking market intelligence will be better positioned to capture value, mitigate risk, and outperform competitors constrained by incomplete information. The interplay of raw material cost dynamics, regional supply conditions, application-driven demand, and a concentrated yet dynamic competitive landscape creates both complexity and opportunity. Success will belong to those who can read these signals accurately and act on them decisively.
For decision-makers who require deeper granularity beyond the high-level perspective presented here, the full High Purity Alumina Sol Market research report offers a comprehensive intelligence package designed to inform strategy, sharpen execution, and unlock competitive advantage. To access the complete segmentation data, detailed competitor profiles, regional and application-level analysis, and full forecast models, visit the source page to obtain the complete market research package and ensure your organization is equipped with the most current and actionable intelligence available for 2026 and beyond.
For detailed analysis of this topic, please visit the official page:High Purity Alumina Sol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek