
Strategic Intelligence for the Next Wave of Wearable Fitness: Inside the Worldwide Smart Fitness Belt Market 2026–2032
The global fitness technology landscape is undergoing a structural transformation. Wearables have graduated from simple step counters to sophisticated, context-aware devices that integrate biometric sensing, electrical muscle stimulation, and real-time posture analytics. Within this evolving ecosystem, the smart fitness belt has emerged as a highly strategic product category, bridging consumer wellness, rehabilitation-adjacent applications, and digital health ecosystems. PW Consulting’s newly released Worldwide Smart Fitness Belt Market report is designed to equip executives, product strategists, and investment leaders with decision-grade intelligence for 2026 and beyond. This overview outlines the strategic value of the study, the architecture of the analysis, and the competitive and regulatory dynamics shaping the sector—without diluting the proprietary segmentation and forecasting data reserved for full report subscribers.
Worldwide Smart Fitness Belt Market
Market intelligence in high-velocity wearable categories is often reduced to headline figures. Yet executive decision-making demands more than top-line projections. It requires an integrated view of how product architectures, distribution pathways, regional demand rhythms, and regulatory classifications interact to shape margin profiles, go-to-market priorities, and competitive positioning. The Worldwide Smart Fitness Belt Market report delivers precisely this integrated lens, anchored in a rigorous historical reconstruction and a forward-looking forecast window spanning 2026 through 2032. By anchoring strategy in evidence rather than speculation, the study enables leadership teams to allocate capital, prioritize R&D, and calibrate market entry or expansion plans with confidence.
Worldwide Smart Fitness Belt Market
The Strategic Imperative for 2026 Decision-Making
Why does a dedicated smart fitness belt study matter in 2026? The answer lies in the convergence of several forces that are reshaping both demand and supply in the wearable fitness segment. First, consumer expectations around home-based and hybrid fitness routines continue to mature, driving demand for devices that deliver measurable muscular engagement rather than passive tracking. Second, the line between consumer wellness and regulated medical or safety applications is increasingly blurred, creating both opportunity and compliance complexity. Third, competition in this category is intensifying across geographies, with manufacturers differentiating through electrode technology, app ecosystems, and channel control. In this environment, organizations that rely on fragmented data sources or generic fitness wearables reports risk misjudging category-specific growth vectors.
Worldwide Smart Fitness Belt Market
This report is built to resolve that information asymmetry. It translates historical demand patterns into a transparent forecasting framework, enabling executives to test strategic assumptions against modeled trajectories for 2026 and the subsequent seven-year outlook to 2032. The study’s base-year context and historical reconstruction cover the 2020 to 2025 period, providing the empirical foundation needed to evaluate how the category responded to post-pandemic fitness behavior shifts, supply chain normalization, and evolving channel economics. From that foundation, the forecast period examines how growth is expected to compound, where momentum is likely to concentrate, and how different product and distribution configurations may outperform or lag.
Crucially, the study is structured to serve multiple decision functions simultaneously. For product leaders, it clarifies which functional orientations and technology bundles are defining category standards. For commercial teams, it maps the relative importance of online versus specialty and mass retail pathways, revealing where customer acquisition costs, brand control, and basket economics diverge. For corporate development and investors, it frames the competitive landscape in terms of concentration, differentiation, and the strategic logic of incumbents versus emerging entrants. The result is not a single-number summary but a decision platform that supports scenario planning across product roadmaps, channel strategy, geographic prioritization, and partnership design.
Market Trajectory and Growth Architecture
At the macro level, the Worldwide Smart Fitness Belt category has demonstrated sustained expansion across the reconstructed historical window and is positioned for continued upward momentum throughout the forecast horizon. The market trajectory reflects a category that has moved beyond early-adopter experimentation into a more mature demand phase, where functionality, usability, and brand trust increasingly determine purchase behavior. The forecast model incorporates this maturation dynamic, translating historical revenue progression into forward expectations that account for product cycle timing, channel evolution, and shifting consumer preferences.
The historical record captured in the study shows a clear scaling pattern: the category advanced from a foundational base in 2020, accelerated through successive years as fitness hardware gained broader acceptance in home and hybrid training contexts, and sustained that momentum into the most recent base-year observation. This progression underscores the category’s transition from niche novelty to a recognizable fixture within the broader wearable fitness portfolio. Rather than treating this trajectory as a simple arithmetic extrapolation, the forecast methodology integrates structural drivers—including product innovation cadence, channel mix shifts, and regional demand variation—so that growth expectations reflect the market’s operational realities rather than headline momentum alone.
The forward-looking window to 2032 is designed to help executives evaluate long-horizon commitments. By examining how the category is expected to scale across multiple years, leadership teams can assess the durability of demand, the timing of incremental growth waves, and the potential impact of new product introductions or regulatory developments on category velocity. This temporal framing is especially valuable for organizations considering product platform investments, manufacturing capacity decisions, or market entry timing, where misaligned forecasts can translate directly into excess inventory, under-resourced launches, or missed competitive windows.
In parallel, the report situates growth within a broader competitive and structural context by analyzing market concentration dynamics. The category’s concentration profile indicates a landscape where a meaningful share of value is held by a defined set of participants, yet sufficient openness remains for differentiated entrants to carve out positions through specialization, technology traction, or channel advantage. Understanding this balance is essential for evaluating partnership opportunities, acquisition rationale, and the strategic defensibility of product portfolios. The study uses this concentration lens to frame where competitive intensity is likely to be strongest and where whitespace may still exist for targeted strategies.
Segment Architecture Driving Commercial Strategy
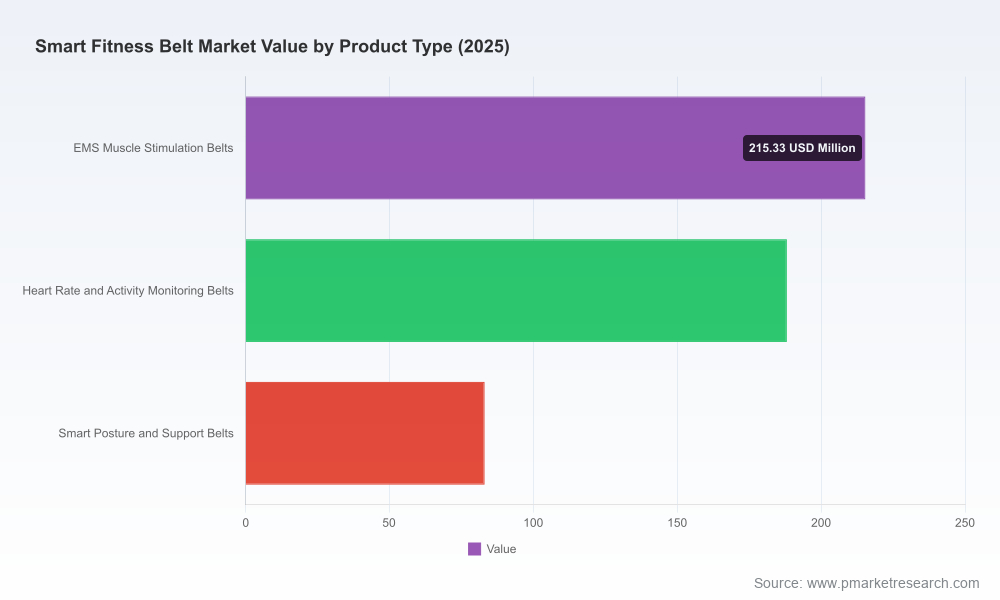
One of the most actionable dimensions of the report is its segmentation architecture. Smart fitness belts are not a monolithic category; they encompass distinct functional orientations that appeal to different user needs, price points, and purchase journeys. The study disaggregates the market into core product-type segments that reflect how consumers and channel partners evaluate value. These include electrical muscle stimulation belts designed for targeted muscle activation, heart rate and activity monitoring belts centered on biometric tracking and performance feedback, and smart posture and support belts focused on alignment, movement quality, and core engagement awareness.
Each segment carries its own strategic implications. EMS-oriented products demand differentiation through stimulation technology, electrode quality, usability, and safety perception, often positioning the category closer to active training tools than passive trackers. Biometric and activity monitoring belts compete in a more crowded sensing environment, where accuracy, app integration, and ecosystem value become decisive. Posture and support belts address a distinct use case that blends fitness, ergonomics, and daily wearability, expanding the addressable context beyond dedicated workout sessions. By examining these segments as interrelated but separate strategic arenas, the report helps leaders identify where to concentrate product development, messaging, and channel resources.
Distribution represents another critical axis of differentiation. The category’s channel structure shapes brand visibility, margin economics, and customer relationship ownership. Online retail pathways offer scale, data richness, and direct-to-consumer engagement potential, while specialty fitness stores provide credibility, hands-on demonstration opportunities, and category alignment with trained staff. Supermarkets and hypermarkets contribute reach and convenience, though often with different margin and positioning dynamics. The report evaluates the relative weight of these pathways without reducing them to simplistic rankings, enabling commercial teams to model channel mix scenarios that reflect their brand strategy, cost structure, and customer acquisition approach.
Regional demand variation adds further nuance. Different geographic markets exhibit distinct adoption rhythms based on fitness culture, e-commerce maturity, healthcare and wellness infrastructure, and competitive supply. Rather than presenting static regional snapshots, the study uses regional variation as a strategic input for prioritization decisions. This allows executives to assess where early traction is most plausible, where scaling may require localized product or channel adaptations, and where competitive supply is already dense. The segmentation architecture as a whole is designed to support practical allocation choices: which product orientation to lead with, which channel to strengthen, and which regional opportunities merit dedicated resources versus opportunistic presence.
Competitive Landscape and Differentation Logic
Competitive strategy in the smart fitness belt market depends on understanding not only who the players are, but how they compete. The report maps a landscape that includes established device manufacturers, technology-focused entrants, and companies building specialized niches around EMS training, posture tracking, or activity monitoring. Rather than treating competition as a brand list, the analysis emphasizes differentiation logic: the technology foundations, product positioning, and application contexts that separate one offering from another.
MTG Co., Ltd., based in Nagoya, Japan, exemplifies a playbook centered on electrical muscle stimulation for home-based core training. Its SIXPAD EMS training devices, including abdominal and body fitness belts, illustrate how a brand can anchor its identity around a specific stimulation philosophy and consumer training regimen. PowerDot, operating in the United States, reflects a different but related orientation, providing smart muscle stimulator devices and wearable EMS technology applicable to targeted abdominal and core muscle activation. These two profiles highlight that EMS-oriented competition is not uniform; it spans distinct design philosophies, user experiences, and commercialization approaches, even when the underlying technology category overlaps.
Shenzhen Roundwhale Technology Co., Ltd. represents the manufacturing and product specialization side of the market, producing electrode belts and EMS fitness belts specifically for abdominal muscle training. This profile underscores the importance of component-level engineering and application focus in a category where electrode performance, fit, and repeated usability can materially influence perceived value. On the posture and movement tracking side, Lumo Bodytech, also based in the United States, develops smart belts with fitness and core engagement monitoring capabilities, illustrating how functional differentiation can extend beyond stimulation into movement quality and behavioral feedback. WELT, based in South Korea, adds another strategic angle by producing smart belts focused on activity tracking, posture, and fitness metrics, showing how regional innovation centers are building offerings that blend multiple functional signals within a single wearable form factor.
Together, these companies demonstrate that the category’s competitive dynamics are shaped by both technology specialization and application framing. Some participants compete primarily on stimulation efficacy and training outcomes, others on posture and movement intelligence, and others on integrated activity metrics that broaden everyday relevance. The report uses this competitive mapping to help strategists evaluate where a potential entrant or incumbent can create defensible differentiation, where brand positioning may be crowded, and where partnerships or acquisitions could accelerate capability building.
Market concentration data further enriches this competitive view. By examining how value is distributed across participants, the study provides a basis for assessing whether the category is trending toward consolidation, remaining contestable, or fragmenting around niche applications. This is particularly relevant for organizations evaluating whether to compete broadly or to anchor strategy in a narrower, higher-margin segment. Concentration analysis also informs expectations about pricing behavior, channel leverage, and the potential for feature convergence as competitors respond to one another’s product cycles.
Regulatory and Technology Forces Reshaping the Category
The strategic context for smart fitness belts extends beyond consumer demand and product features. Regulatory classification and material technology choices are increasingly influential in defining what a belt can claim, how it can be positioned, and which pathways are available for commercialization. In the United States, regulatory attention around powered muscle stimulators has created important safeguards and boundaries. FDA maintenance of Import Alert 89-01, which allows detention without physical examination of certain misbranded and/or adulterated powered muscle stimulators, explicitly including specific fitness belt models, signals that compliance and labeling integrity are not peripheral concerns. For manufacturers and brand owners, this reinforces the importance of rigorous documentation, truthful claims, and product quality controls, especially for EMS-oriented products that may be scrutinized more closely than passive trackers.
At the same time, regulatory developments also illustrate how wearable belts can move into more specialized use cases. Recent FDA actions, including De Novo classification pathways for certain wearable smart belts intended for injury prevention applications, show that classification outcomes can differ markedly depending on intended use and functional claims. This distinction matters strategically because it affects market positioning, customer trust, and the commercial framing of a device. A belt positioned strictly as a consumer fitness product faces a different set of expectations and constraints than one aligned with a regulated medical or safety indication. The report incorporates these dynamics so that executives can evaluate the strategic implications of classification choices, claim boundaries, and category adjacency.
On the technology side, electrode design and materials remain central to EMS-based smart belts. Consumer product specifications increasingly emphasize reusable hydrogel pads and silicone electrodes, with some listings referencing usable lifespans measured in multiple applications. These material considerations influence user experience, replacement cycles, cost structure, and environmental positioning. They also create differentiation opportunities: companies that improve pad durability, adhesion quality, skin comfort, or electrode consistency can translate those advantages into stronger product perception and lower friction in repeat use. The study integrates this material-level context into its segment and product analysis, recognizing that the performance of core consumables and contact components can be as strategically important as the belt’s electronic architecture.
A further strategic dimension lies in the broader reimbursement and classification environment for wearables that cross into medical indications. Certain wearable smart belts designed for specific safety or health-related applications may navigate FDA Class II medical device pathways rather than functioning purely as consumer fitness products. This does not mean every belt will pursue such a pathway, but it does suggest that the category boundary is permeable. For organizations considering expansion into adjacent use cases, the distinction between consumer wellness and regulated device positioning can shape product requirements, evidence generation, time-to-market, and channel partnerships. By acknowledging these pathways, the report helps leaders anticipate where category evolution may create new commercial models and where compliance overhead may need to be built into planning.
What the Report Delivers: An Operational Intelligence Framework
The Worldwide Smart Fitness Belt Market report is designed as an operational resource, not a static market snapshot. It combines historical reconstruction, forecast modeling, segmentation analysis, competitive mapping, and regulatory and technology context into a unified framework that can be used across multiple business functions. The study answers practical questions that executives face when evaluating entry, expansion, portfolio adjustment, or investment in this category.
Among the core deliverables is a transparent view of market sizing and trajectory that connects base-year evidence with forward-looking expectations. This enables teams to benchmark internal assumptions, test growth scenarios, and assess whether product or channel plans are aligned with modeled demand behavior. The segmentation analysis supports product strategy by clarifying how different functional orientations and distribution pathways shape market structure. Rather than treating segments as abstract labels, the report frames them as decision-relevant building blocks for portfolio design, messaging, and commercialization sequencing.
The competitive section provides a structured reading of the landscape, highlighting how leading and emerging players differentiate, where concentration is influencing market dynamics, and what that implies for positioning and partnership strategy. Combined with the regulatory and technology context, this gives strategists a multidimensional view of the environment in which products will be launched, sold, and iterated. The inclusion of material-level considerations, classification pathways, and compliance signals ensures that the analysis reflects the operational realities of bringing a smart fitness belt to market, not just the surface-level appeal of the category.
For organizations using the report to support cross-functional planning, the value lies in integration. Product, commercial, supply chain, and corporate development teams can use the same evidence base to align priorities rather than working from fragmented inputs. That alignment is particularly important in categories where product functionality, channel economics, regulatory posture, and competitive response all interact quickly. By providing a shared analytical foundation, the study reduces the risk of siloed interpretations and helps leadership coordinate actions across the organization.
Translating Insight into Decision Advantage
The strategic value of the Worldwide Smart Fitness Belt Market report ultimately rests on its ability to convert data into action. For 2026 decision-making, that means helping executives answer questions that are both immediate and structural. Which product orientation offers the strongest alignment with current demand and future growth? How should channel mix be optimized to balance reach, margin, and brand control? Where does competitive concentration create risk, and where does it create opportunity for focused differentiation? How should regulatory and technology developments shape claims, design priorities, and possible market adjacency?
The report is built to support these decisions with discipline. It preserves the analytical rigor needed for credible forecasting while maintaining a practical orientation that executives can apply directly to strategic planning. By focusing on the interplay of product type, distribution channel, regional demand variation, competitive logic, and regulatory context, it provides a complete enough picture to guide action without oversimplifying the complexity of the category. At the same time, it intentionally reserves the deepest level of segment-specific data for the full report, ensuring that decision-makers who require granular intelligence can access it in a structured, proprietary format.
In a market where wearable fitness continues to evolve rapidly, the organizations that succeed will be those that treat category intelligence as a strategic asset. The Worldwide Smart Fitness Belt Market study offers that asset in a form designed for 2026 and the forecast years ahead: evidence-based, segment-aware, competition-informed, and operationally relevant. For leaders seeking to move beyond general industry narratives and into precise, decision-ready understanding, the full report provides the detailed segmentation, regional and channel-level intelligence, and proprietary market structure data needed to convert insight into a durable competitive position.
For detailed analysis of this topic, please visit the official page:Worldwide Smart Fitness Belt Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek