
Beyond the Amplification Curve: Strategic Insights into the Worldwide Molecular Diagnostic Raw Enzymes Market (2026–2032)
The molecular diagnostics industry stands at a critical inflection point. As healthcare systems globally transition toward precision medicine, decentralized testing, and rapid infectious disease surveillance, the foundational components that make these assays possible have never been more strategically significant. Among these components, raw enzymes serve as the biochemical engine of modern molecular testing. From polymerases that drive nucleic acid amplification to reverse transcriptases that enable RNA detection, the supply, quality, and innovation trajectory of these raw materials directly shape the competitiveness of diagnostic manufacturers, assay developers, and healthcare providers alike.
Worldwide Molecular Diagnostic Raw Enzymes Market
PW Consulting is pleased to introduce our latest comprehensive research study, the Worldwide Molecular Diagnostic Raw Enzymes Market. This report is designed to equip executives, investors, procurement leaders, and innovation strategists with the analytical rigor needed to navigate a market undergoing simultaneous transformation across technology, regulation, and geography. Below, we provide a strategic preview of the market landscape, competitive dynamics, and decision-making frameworks explored in depth within the full study.
Worldwide Molecular Diagnostic Raw Enzymes Market
The Macro Trajectory: Why 2026 Is a Defining Year
Understanding the scale and pace of this market is essential for any strategic planning exercise. Drawing on historical data spanning 2020 through 2025 and a forward-looking forecast window extending to 2032, our analysis captures both the consolidation of post-pandemic demand and the emergence of new growth vectors.
Worldwide Molecular Diagnostic Raw Enzymes Market
The global molecular diagnostic raw enzymes market registered steady expansion over the past half-decade, with total revenue climbing from 895.4 million USD in 2020 to 1200.0 million USD in 2025. This historical progression reflects not only the heightened reliance on molecular testing during public health crises but also the durable integration of molecular workflows into routine clinical diagnostics, oncology profiling, and genetic screening programs. As the industry moves into the 2026 base year, the market is projected to reach 1318.85 million USD, signaling renewed momentum beyond the volatility of earlier years.
Looking ahead across the forecast period through 2032, the market is positioned to reach 2075.33 million USD. This trajectory corresponds to a compound annual growth rate of 8.14 percent, a figure that underscores the structural nature of demand rather than a transient surge. For strategic planners, an 8 percent-plus growth environment presents both opportunity and complexity: it rewards early investment in capacity, quality infrastructure, and application-specific enzyme engineering, while simultaneously raising the stakes around supply chain resilience, regulatory compliance, and competitive differentiation.
It is worth noting that historical data reveals a nuanced pattern. After a period of consistent year-over-year growth, the 2025 valuation shows a slight moderation compared to 2024. This normalization reflects a broader industry recalibration as supply chains stabilize, procurement cycles mature, and end-users optimize inventory strategies. Far from signaling weakness, this pattern highlights the importance of forward-looking analysis that distinguishes between cyclical adjustments and long-term secular growth drivers.
Market Structure and Segmentation Dynamics
The molecular diagnostic raw enzymes market is not monolithic. It is shaped by distinct enzyme classes, diverse application pathways, and regional variations in healthcare infrastructure, regulatory frameworks, and procurement practices. Our report dissects these dimensions systematically, providing decision-makers with a granular understanding of where value is created and how demand flows through the ecosystem.
Enzyme Types: The Core Catalysts of Molecular Workflows
At the heart of the market lie three principal enzyme categories, each tied to specific assay architectures and end-user requirements. Polymerases remain the dominant engine of nucleic acid amplification, enabling the foundational processes behind PCR, qPCR, and emerging isothermal methods. Reverse transcriptases are indispensable for RNA-targeted workflows, including viral load monitoring, gene expression analysis, and transcriptome-based diagnostic applications. Nucleases and other specialized enzymes complete the toolkit, serving roles in sample preparation, contamination control, and assay optimization.
The relative prominence of each type is driven by application mix, technological adoption cycles, and manufacturing complexity. Our study examines how purity standards, stability profiles, and production scale requirements differ across these categories, and what those differences mean for suppliers seeking to capture share in high-value segments.
Applications: Where Diagnostic Value Is Realized
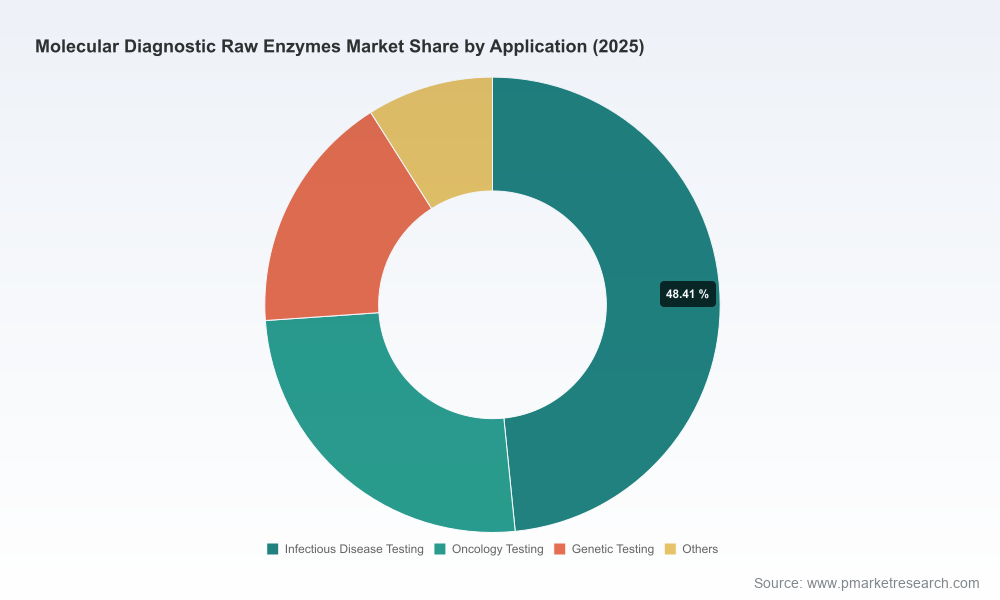
Molecular diagnostic raw enzymes ultimately serve a range of clinical and research applications, each with its own demand characteristics and growth catalysts. Infectious disease testing represents a substantial and enduring demand pool, fueled by ongoing needs in respiratory pathogen detection, bloodstream infection diagnostics, and sexually transmitted infection screening. Oncology testing continues to expand as companion diagnostics, minimal residual disease monitoring, and molecular tumor profiling become embedded in standard care pathways. Genetic testing applications, including inherited disease screening and pharmacogenomic workflows, add another layer of structural demand. Beyond these core areas, additional application categories contribute to a diversified demand base that strengthens overall market resilience.
For companies developing or procuring enzymes, understanding the application mix is not merely an academic exercise. It shapes formulation priorities, quality certification pathways, and commercial strategy. The full report maps these application-driven dynamics in detail, showing how demand patterns are evolving across clinical laboratories, IVD manufacturers, and decentralized testing environments.
Regional Landscape: Divergent Growth Engines
Demand for molecular diagnostic raw enzymes is distributed across a global footprint, but growth rates, regulatory maturity, and procurement models vary significantly by region. North America remains a central hub of demand, supported by well-established diagnostic infrastructure, extensive research activity, and a robust IVD manufacturing base. Europe contributes a substantial share as well, shaped by strong public healthcare systems, evolving regulatory requirements, and active participation in both clinical and industrial research. Asia Pacific represents a dynamic growth region, where expanding healthcare access, growing diagnostic capacity, and increased investment in life sciences are accelerating adoption. The Rest of the World, while smaller in relative scale, is gaining attention as emerging markets build diagnostic capabilities and regional supply networks.
Regional analysis in our study goes beyond headline figures to address the strategic implications of geographic diversification. For suppliers, this means evaluating where local manufacturing, regulatory alignment, and technical support capabilities can create durable advantage. For buyers, it means understanding where concentration risk, lead-time variability, and quality assurance requirements may influence sourcing decisions.
Competitive Landscape: Scale, Specialization, and Strategic Positioning
The molecular diagnostic raw enzymes market features a blend of large multinational life sciences companies, specialized enzyme manufacturers, and emerging innovators. This diversity creates a competitive environment in which scale, technical differentiation, quality systems, and customer intimacy all play roles in market positioning. Our report profiles the key participants shaping this landscape and analyzes the strategic moves that are redefining competitive boundaries.
Among the established leaders, F. Hoffmann-La Roche Ltd through its CustomBiotech division operates as a significant provider of molecular raw materials, offering products such as FastStart Taq DNA Polymerase, designer polymerases for reverse transcription, lyo-ready enzymes, and KAPA polymerases optimized for molecular diagnostics assays and IVD manufacturing. Thermo Fisher Scientific is another major supplier, with a broad portfolio of enzymes for molecular diagnostics including Taq DNA polymerases, reverse transcriptases, and other PCR and RT-PCR enzymes used in clinical and IVD applications. Merck KGaA, operating through MilliporeSigma and Sigma-Aldrich, provides ultra-pure molecular raw materials for diagnostics, including JumpStart Taq DNA Polymerase, High Temp RT Enzyme, and BST-RT Polymerase suitable for IVD assay development and manufacturing.
The competitive field also includes firms with strong specialization in enzyme engineering, GMP-grade production, and diagnostic-grade quality systems. Meridian Bioscience manufactures PCR and RT-qPCR enzymes, DNA polymerases, reverse transcriptase enzymes, and buffer systems under ISO 13485 for IVD assay development and optimization. New England Biolabs supplies high-quality molecular biology enzymes including polymerases and other tools manufactured at GMP-grade quality and scale for diagnostic and therapeutic innovation. Promega Corporation provides enzymes and reagents for molecular diagnostics workflows, including PCR amplification, reverse transcription, restriction enzymes, and NGS applications. QIAGEN supplies bulk OEM enzymes including DNA polymerases, RNA polymerases, reverse transcriptases, and ligases for PCR, RT-PCR, and NGS in molecular diagnostics. Takara Bio offers high-performance DNA polymerases, reverse transcriptases, and other enzymes tailored for RT-PCR and molecular diagnostics workflows. Additional contributors such as Aldevron, Codexis, ArcticZymes Technologies, and Creative Enzymes further broaden the ecosystem, each bringing distinct capabilities in enzyme engineering, manufacturing scale, or application-specific performance.
Strategic analysis in our study explores how these companies navigate the tension between breadth and depth. Some compete on portfolio scale and global distribution; others on specialized enzyme performance, regulatory-grade quality, or customer-specific assay support. For buyers and investors, understanding these strategic postures is essential for evaluating supplier resilience, partnership potential, and long-term pricing dynamics.
Recent Industry Developments Shaping the 2026 Outlook
Market context is never static. Recent corporate activity and industry shifts are already reshaping expectations for the forecast period. Our report integrates these developments into a cohesive view of where the market is heading and why.
In January 2026, Synthego announced entry into the molecular biology and clinical diagnostic reagents market with components for nucleic acid amplification, detection, high-fidelity PCR enzymes, and high-sensitivity reverse transcriptase. This move signals a broader trend of new entrants seeking to capture value in critical enzyme categories, intensifying competition in segments where performance differentiation and quality assurance are increasingly decisive.
In March 2026, New England Biolabs expanded support for diagnostic and therapeutic innovation by manufacturing and inventorying multiple enzymes at GMP-grade quality and scale, spanning milliliter to liter volumes for commercially-approved production. This development highlights the growing importance of manufacturing readiness, scale flexibility, and regulatory-grade supply in an environment where IVD manufacturers and therapeutic developers require dependable, validated enzyme sources.
In April 2026, Takara Bio USA launched a certified service provider program to advance research using NGS and single-cell technologies, supporting the broader molecular diagnostics ecosystem. Initiatives of this type reflect the convergence of research tools, diagnostic workflows, and technical service models, reinforcing the idea that enzyme suppliers are increasingly competing on ecosystem value rather than product catalog alone.
Regulatory, Quality, and Reimbursement Forces
Market growth does not occur in a vacuum. Regulatory requirements, quality expectations, and reimbursement pathways are shaping how molecular diagnostic raw enzymes are developed, manufactured, and adopted. These forces create both barriers to entry and opportunities for companies that align their capabilities with industry requirements.
Enzymes for molecular diagnostics are typically manufactured under ISO 13485 regulations to meet requirements for IVD assay development and clinical use. This quality management framework establishes expectations for documentation, process control, and traceability that directly influence supplier selection. At the product level, molecular diagnostic raw enzymes such as Taq DNA polymerase and reverse transcriptases require high-purity production processes free of detectable DNA, DNase, RNase, nickase or endonuclease contamination. Such specifications elevate the importance of process integrity, analytical validation, and consistent batch performance.
Beyond quality systems, regulatory clearance dynamics are expanding the commercial landscape. FDA clearance of additional near-patient molecular tests has expanded reimbursement pathways, incentivizing adoption of molecular diagnostic platforms that rely on raw enzymes. As point-of-care and near-patient testing continue to grow, enzyme suppliers must consider not only central laboratory requirements but also the stability, packaging, and performance characteristics needed for decentralized environments.
GMP-grade production and quality standards are also increasingly required for enzymes used in commercially-approved mRNA and diagnostic manufacturing processes. This convergence of diagnostic and biomanufacturing expectations points to a future in which enzyme suppliers with robust quality infrastructure and scalable GMP capabilities may enjoy broader market access and stronger customer stickiness.
Strategic Implications for 2026 Decision-Makers
The macro trajectory, segmentation structure, competitive dynamics, and regulatory context described above converge into a set of strategic questions that our report is designed to help leaders answer.
For suppliers and manufacturers, the market’s 8.14 percent projected CAGR through 2032 suggests that demand expansion will reward players who can align product portfolios with high-growth application areas, invest in regulatory-grade manufacturing, and differentiate through enzyme performance or service models. At the same time, the presence of well-capitalized incumbents and new entrants means that pricing pressure, portfolio overlap, and customer switching behavior must be managed proactively.
For IVD manufacturers and diagnostic developers, enzyme selection is a strategic input that affects assay robustness, development timelines, regulatory readiness, and supply continuity. The growing emphasis on purity, contamination control, and GMP-grade production elevates the importance of supplier qualification and long-term partnership design. Regional demand variation further complicates sourcing strategy, as companies balance concentration risk against cost, lead time, and technical support considerations.
For investors and market strategists, the combination of moderate concentration at the top of the competitive spectrum and persistent innovation activity across enzyme types and applications suggests a market where value creation is increasingly tied to technical differentiation and ecosystem integration. Analyzing market concentration levels, recent corporate entries, and manufacturing scale investments can help identify where competitive advantage is being built and where disruption risk may be rising.
Our full study explores these themes through detailed market sizing, segmentation analysis, regional breakdowns, and company-level profiling. It also examines how raw material requirements, reimbursement developments, and regulatory frameworks interact to shape procurement choices and commercial strategy across the forecast horizon.
What the Full Report Delivers
This preview offers a high-level view of the market architecture and strategic issues at play. The complete Worldwide Molecular Diagnostic Raw Enzymes Market report goes further, providing a structured decision-support platform that includes:
- Historical market data and forecast models spanning 2020 through 2032, with a 2026 base year and analysis of demand normalization patterns
- Segment-level analysis across enzyme types, applications, and regions, with context on how each segment contributes to overall market dynamics
- Competitive profiling of leading enzyme suppliers and innovators, including product focus, manufacturing approach, and recent strategic developments
- Qualitative and quantitative analysis of regulatory, quality, and reimbursement forces shaping enzyme selection and market access
- Strategic frameworks for evaluating supplier risk, partnership models, capacity planning, and geographic diversification
- Insight into recent market entries, manufacturing expansions, and service programs that are altering competitive expectations
By integrating market structure with competitive and regulatory context, the report is designed to support a wide range of decisions, from portfolio planning and sourcing strategy to investment prioritization and market entry assessment.
How to Use This Intelligence
The molecular diagnostic raw enzymes market is becoming more technically demanding, more regionally varied, and more competitive at the same time. In such an environment, strategic decisions benefit from evidence that connects market size and growth to the underlying drivers of demand, supply, and differentiation.
Our report is intended to serve as a reference point for executives who need to evaluate where the market is heading, which segments and regions are generating the most momentum, and how key competitors are positioning themselves for the forecast period. It is equally useful for operational leaders seeking to understand quality expectations, regulatory requirements, and supply chain considerations that affect sourcing and manufacturing choices.
To access the full dataset, segmentation analysis, competitive profiles, and strategic commentary, we invite you to explore the complete report on the PW Consulting website. There, you will find the detailed tables, regional and segment breakdowns, company assessments, and forecast scenarios that provide the depth required for informed decision-making in 2026 and beyond.
The next phase of growth in molecular diagnostics will be shaped not only by end-user demand but also by the companies that supply the enzymes making that demand measurable, reliable, and scalable. With the right strategic intelligence, organizations can position themselves to participate in that growth with clarity and confidence.
For detailed analysis of this topic, please visit the official page:Worldwide Molecular Diagnostic Raw Enzymes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek