
Navigating the Cold Frontier: Strategic Intelligence for the Global Cryosurgical Units Market in 2026
The landscape of minimally invasive therapy is undergoing a profound transformation, driven by an aging global population, the rising prevalence of oncological conditions, and an accelerating demand for outpatient procedural efficiency. Within this complex ecosystem, cryosurgical units (CSUs) have emerged as a cornerstone technology, offering precise tissue ablation with reduced recovery times and lower complication rates compared to traditional excisional methods. As we enter 2026, understanding the trajectory of this market is no longer optional for medical device manufacturers, healthcare providers, and investors; it is a strategic imperative.
Worldwide Cryosurgical Units (CSUs) Market
PW Consulting's latest comprehensive study on the Worldwide Cryosurgical Units Market serves as an essential navigational tool for stakeholders aiming to capitalize on these shifting dynamics. This research is not merely a retrospective analysis of past sales figures; it is a forward-looking intelligence asset designed to inform high-stakes decision-making throughout the forecast period extending to 2032. The following insights outline the strategic value embedded within this report, highlighting the macro-environmental drivers, competitive intricacies, and regulatory currents that will define the next era of cryosurgery.
Worldwide Cryosurgical Units (CSUs) Market
Macro-Economic Trajectory and Revenue Potential
The financial architecture of the cryosurgical units market demonstrates robust growth characteristics that warrant serious attention from portfolio managers and strategic planners. Historical data analysis from 2020 through the base year of 2025 reveals a consistent upward trajectory in market revenue, reflecting the steady adoption of cryogenic technologies across varied clinical settings. The market has evolved from a niche segment into a substantial component of the broader surgical devices landscape, with valuation figures indicating significant momentum as the sector moves into the forecast horizon.
Worldwide Cryosurgical Units (CSUs) Market
Looking forward, the optimistic growth outlook is underpinned by a projected compound annual growth rate that signals sustained expansion over the coming years. This growth is not linear but is instead influenced by pivotal product launches, regulatory clearances, and shifting reimbursement frameworks that alter the adoption curve for specific technologies. For organizations evaluating market entry or expansion, the forecast period data provided in our study offers critical benchmarks for revenue modeling and capacity planning. The ability to anticipate peak valuation years and understand the velocity of growth between intervals allows for optimized resource allocation and investment timing.
Stakeholders must recognize that the market size evolution is contingent upon several macro variables, including healthcare expenditure trends in key economies and the rate of technological diffusion from developed to emerging markets. Our analysis contextualizes these revenue figures within the broader economic environment, ensuring that clients can distinguish between temporary fluctuations and structural growth shifts. This distinction is vital for long-term strategic planning, particularly when assessing the viability of sustained R&D investment or potential acquisition targets within the cryogenic space.
Deconstructing the Supply Side: Product Diversity and Application Breadth
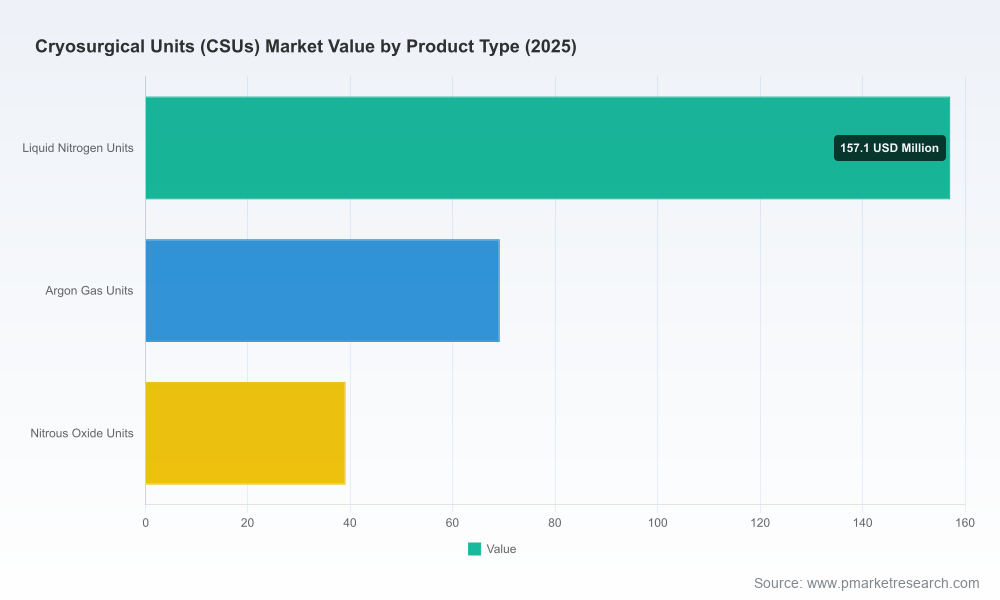
The cryosurgical market is not a monolith; it is a diversified collection of technologies serving distinct clinical needs. A primary value of this report lies in its granular breakdown of product types, which allows manufacturers to identify high-growth pockets within their specific technology lanes. The market is primarily segmented by the type of cryogenic agent and delivery mechanism, ranging from established liquid nitrogen systems to specialized argon gas and nitrous oxide units. Each category carries unique implications for handling, safety protocols, clinical efficacy, and target customer profiles.
Liquid nitrogen units continue to hold a significant position, particularly in settings where cost-effectiveness and versatility are paramount. These systems are widely recognized for their utility in dermatology and certain ablation procedures. Conversely, argon gas units are often associated with more specialized interventional applications where precision and specific thermal dynamics are required. Nitrous oxide systems occupy a specialized niche, often favored in specific gynecological or localized treatment scenarios. Understanding the share and growth dynamics of each product type is essential for companies deciding whether to diversify their portfolio or double down on a core competency.
Beyond the hardware, the report extensively covers the application landscape, which is equally fragmented and opportunity-rich. Dermatology remains a dominant field for cryosurgical interventions, driven by the high volume of benign and pre-malignant lesion treatments in outpatient clinics. However, the oncology sector represents a high-value frontier, where cryoablation is increasingly utilized for tumor destruction in organs such as the prostate, kidney, and liver. Cardiology is another critical segment, where cryotechnology is applied for arrhythmia management, a area experiencing significant innovation. Additional applications in gynecology and other therapeutic areas contribute to the overall demand profile.
By mapping the revenue contribution and growth potential of each application area, the report enables stakeholders to prioritize clinical marketing efforts and tailor product development roadmaps. For instance, a company specializing in handheld devices might find greater strategic alignment with dermatology needs, while those with complex ablation systems may target oncology and cardiology centers. The interplay between product type and application is a key focus of the analysis, revealing cross-segment opportunities that might otherwise remain obscured in aggregate market data.
The Competitive Battlefield: Profiles and Strategic Moves
The global cryosurgical units market is characterized by a mix of established multinational corporations, specialized niche players, and emerging entrants seeking to capture share through innovation or pricing strategies. Our report provides detailed profiling of key companies that are shaping the industry, offering a clear view of the competitive hierarchy. The concentration of market share among the top players indicates a moderately consolidated environment, where strategic partnerships, acquisitions, and regulatory milestones often dictate market leadership.
Prominent entities such as Brymill Cryogenic Systems have long maintained a strong presence, particularly in the handheld liquid nitrogen segment, leveraging decades of heritage and brand recognition in dermatology and veterinary markets. Similarly, Cortex Technology represents a significant European force, known for hand-assembled precision and compliance with both FDA and European MDR standards, focusing heavily on skin lesion treatments. These established players benefit from loyal customer bases and extensive distribution networks, setting a high bar for new entrants.
In the broader ablation and surgical space, large medical device conglomerates play a crucial role. Companies like Medtronic bring substantial resources and integrated solutions, often incorporating acquired technologies to expand their cryoablation offerings for cardiac and surgical applications. Galil Medical, now part of larger entities like BTG or Varian, exemplifies the strategy of specialization within oncology, providing advanced needle probe systems for tumor destruction. The presence of such large-scale players ensures that capital-intensive R&D and clinical validation are sustained, driving the technology forward.
Regional manufacturers are also making notable strides. Hygea Medical Technology Co., Ltd. from China, for example, has recently achieved significant regulatory milestones in the United States, signaling the increasing globalization of supply chains and the competitiveness of Asian manufacturers in high-regulation markets. Medinice S.A. in Poland has similarly garnered attention for their cardiac cryoablation solutions, securing necessary clearances to enter the US market. These developments highlight the dynamic nature of the competitive landscape, where geographic boundaries are becoming less restrictive for innovative devices.
Smaller, agile companies also contribute to the ecosystem's vitality. CryoSurgery, Inc. and CryoConcepts, LP represent segments focused on portable and over-the-counter solutions, tapping into consumer-driven healthcare trends and point-of-care convenience. AtriCure, Inc. focuses on specific surgical applications with dedicated reimbursement strategies, illustrating how niche focus can be leveraged for sustainable growth. The report analyzes the strategic positioning of these firms, their recent operational updates, and their potential impact on market pricing and availability.
Regulatory and Reimbursement Currents Shaping Market Dynamics
The path to commercialization and profitability in the medical device sector is heavily influenced by regulatory frameworks and reimbursement policies. The cryosurgical units market is no exception. Our study dedicates significant attention to the regulatory environment, particularly the classification and clearance processes that govern market access. In the United States, cryosurgical units and accessories are regulated by the FDA as Class II medical devices under specific code sections. This classification requires manufacturers to demonstrate safety and effectiveness through premarket notification pathways, such as the 510(k) clearance process.
Recent records indicate a steady stream of FDA clearances for various cryosurgical devices. For example, in early 2026, Medinice S.A. received clearance for their CoolCryo system for cardiac applications, marking a significant entry point for their technology in the US market. Similarly, earlier clearances granted to companies like CryoSurgery, Inc. for OTC devices and Hygea Medical Technology for their ablation systems highlight the ongoing activity in regulatory approvals. These milestones are not just administrative victories; they are the keys that unlock commercial potential. Our report tracks these clearances to provide a pipeline view of upcoming products and potential market disruptors.
In Europe, the regulatory landscape is shaped by the Medical Device Regulation (MDR). Manufacturers like Cortex Technology must ensure their products, such as the CryoPro units, meet MDR Class IIa requirements and are manufactured in ISO 13485-certified facilities. Compliance with these stringent standards is a barrier to entry but also a marker of quality that can be leveraged in marketing and procurement negotiations. Understanding the nuances of regional regulatory requirements is critical for any company with international aspirations.
Beyond approval, the economics of usage are dictated by reimbursement codes. The introduction of new billing codes can dramatically alter the adoption rate of a procedure. Effective January 1, 2026, the implementation of a new G-Code provides separate reimbursement for certain cryoablation procedures, primarily under Medicare. This change can incentivize providers to adopt cryo technologies over alternative methods if the reimbursement alignment is favorable. For cardiac applications, specific G-Code considerations associated with systems from companies like AtriCure underscore the importance of aligning product development with billing realities.
In dermatology, the coding landscape involves specific CPT codes for lesion removal, where the reimbursement structure varies based on the number of lesions treated. Knowledge of these coding guidelines—ranging from the first lesion to subsequent treatments—is essential for device manufacturers supporting their customers with reimbursement support programs. Our analysis integrates these reimbursement dynamics into the market forecast, assessing how coding changes might accelerate or hinder growth in specific segments. Ignoring these financial drivers can lead to flawed market assessments, which is why they are woven into the fabric of our strategic analysis.
The Strategic Value of Deep-Dive Intelligence
The surface-level data points available in general industry summaries often fail to provide the actionable clarity required for complex strategic decisions. What distinguishes this PW Consulting report is the depth of operational intelligence provided. We do not merely present numbers; we contextualize them. The report includes supply chain considerations, distribution channel analysis, and pricing trends that affect margin structures. For procurement leaders, this translates into better negotiation leverage and vendor selection criteria. For marketing directors, it offers evidence-based segmentation strategies to target high-value accounts.
The segmentation analysis extends beyond the obvious categories. While the report covers region, product type, and application, the true value lies in the interaction effects between these segments. How does the adoption of argon gas units differ between oncology centers in one region versus dermatology clinics in another? What is the impact of OTC device availability on professional market share in specific geographies? These nuanced questions are addressed through the comprehensive data modeling presented in the study.
Furthermore, the report evaluates market concentration metrics to help stakeholders understand the competitive intensity. Knowing the share held by the top three or five players provides insight into the ease of market entry and the potential for consolidation. In a market where the top players command a substantial portion of revenue, new entrants must have a distinct value proposition or target underserved niches. Conversely, in less concentrated segments, there may be opportunities for growth through acquisition or aggressive market share capture.
The inclusion of recent industry developments and news monitoring ensures that the data is not static. The medical device industry moves quickly, with product updates, regulatory letters, and company announcements occurring frequently. By integrating recent clearances and product catalog updates from key players like Brymill and others, the report provides a current snapshot that reflects the market reality as of 2026. This timeliness is crucial for investors and strategic planners who cannot afford to base decisions on outdated information.
Charting the Course for 2032 and Beyond
As the market looks toward the end of the forecast period in 2032, several long-term trends are expected to shape the industry landscape. Technological convergence, where cryosurgery integrates with imaging guidance or robotic assistance, is likely to expand the clinical utility of these systems. The aging population will continue to drive demand for less invasive treatments for chronic and oncological conditions. Additionally, the expansion of healthcare access in emerging economies could unlock new volume growth, although this will be tempered by local regulatory and reimbursement challenges.
Sustainability and safety protocols surrounding cryogenic agents will also gain prominence. As hospitals and clinics face increasing pressure to manage hazardous materials and reduce environmental impact, innovations in storage, delivery, and alternative agents may become differentiating factors. Companies that proactively address these operational concerns may find themselves preferred partners in procurement processes.
Ultimately, success in the cryosurgical units market requires a synthesis of clinical understanding, regulatory acumen, and commercial strategy. The data provided in this report serves as the foundation for building that synthesis. Whether the goal is to launch a new product, enter a new region, or acquire a competitor, the intelligence contained herein is designed to reduce uncertainty and highlight opportunity.
PW Consulting invites industry leaders, investors, and strategic partners to engage with the full dataset and analysis contained in the Worldwide Cryosurgical Units Market report. The insights summarized here represent only the beginning of the intelligence available. To access the complete breakdown of market sizes, segmentation splits, competitive profiles, and forward-looking forecasts, stakeholders are encouraged to visit the source webpage. Comprehensive intelligence is the first step toward confident action, and in a market defined by precision and innovation, having the right data is the most critical tool in your arsenal.
For detailed analysis of this topic, please visit the official page:Worldwide Cryosurgical Units (CSUs) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek