
Strategic Horizons: Navigating the Worldwide Semiconductor Military Laser Market Through 2032
The intersection of semiconductor physics and defense strategy has rarely been as consequential as it is today. As geopolitical tensions escalate and asymmetric threats evolve, the global demand for high-power semiconductor laser systems is reshaping supply chains, R&D priorities, and competitive positioning across the defense industrial base. This article serves as an executive preview of PW Consulting latest comprehensive study, the Worldwide Semiconductor Military Laser Market, designed to equip strategic decision-makers with the contextual intelligence needed to navigate a rapidly expanding sector projected to reach significant scale by the end of the decade.
Worldwide Semiconductor Military Laser Market
For executives, investors, and program managers operating in aerospace, defense, or advanced photonics, the strategic question is no longer whether this market will grow, but how to position portfolios, partnerships, and manufacturing capabilities to capture value while managing regulatory and supply chain risks. The following analysis synthesizes historical trajectories, forward-looking forecasts, competitive dynamics, and critical industry constraints to illustrate why this research is an essential input for 2026 strategic planning.
Worldwide Semiconductor Military Laser Market
Market Trajectory: From Recovery to Structural Expansion
The semiconductor military laser market has demonstrated remarkable resilience and acceleration over the past five years. Tracking historical performance from 2020 through the base year of 2025 reveals a clear upward inflection, driven by defense modernization programs, the proliferation of unmanned aerial systems, and the operational imperative to deploy non-kinetic and directed-energy capabilities at scale. In 2020, global revenues stood at approximately 875.4 million USD. By 2025, that figure had climbed to roughly 1,420.5 million USD, reflecting a compound trajectory shaped by both procurement cycles and technological maturation.
Worldwide Semiconductor Military Laser Market
Looking forward, our forecast window spanning 2026 through 2032 projects sustained momentum. The market is expected to surpass 1,544.41 million USD in 2026 and continue expanding to 2,848.39 million USD by 2032. This trajectory translates to a compound annual growth rate of 10.45 percent over the forecast period, a rate that underscores the structural nature of demand rather than a temporary procurement spike. Such growth is not evenly distributed across time; it is concentrated in program win cycles, technology readiness level transitions, and the scaling of production capacities for high-brightness diode arrays, vertical cavity surface emitting lasers, and edge emitting solutions.
Strategic implication for 2026: Organizations that treat this growth as a linear extrapolation risk misallocating capital. The market is entering a phase where component-level innovation, thermal management integration, and coherent beam combining architectures will determine which programs move from demonstration to fielded capability. Leadership teams should align R&D roadmaps and supplier qualification processes with the phases of this forecast, recognizing that the revenue acceleration between 2028 and 2032 will likely be tied to the operational deployment of next-generation directed energy weapon subsystems and advanced lidar and navigation platforms.
Decoding the Framework: Technology, Application, and Regional Architecture
Understanding where growth concentrates requires an analytical framework that separates the market into actionable layers. Our research dissects the landscape across type, application, and geography, revealing distinct value pools that demand tailored go-to-market strategies.
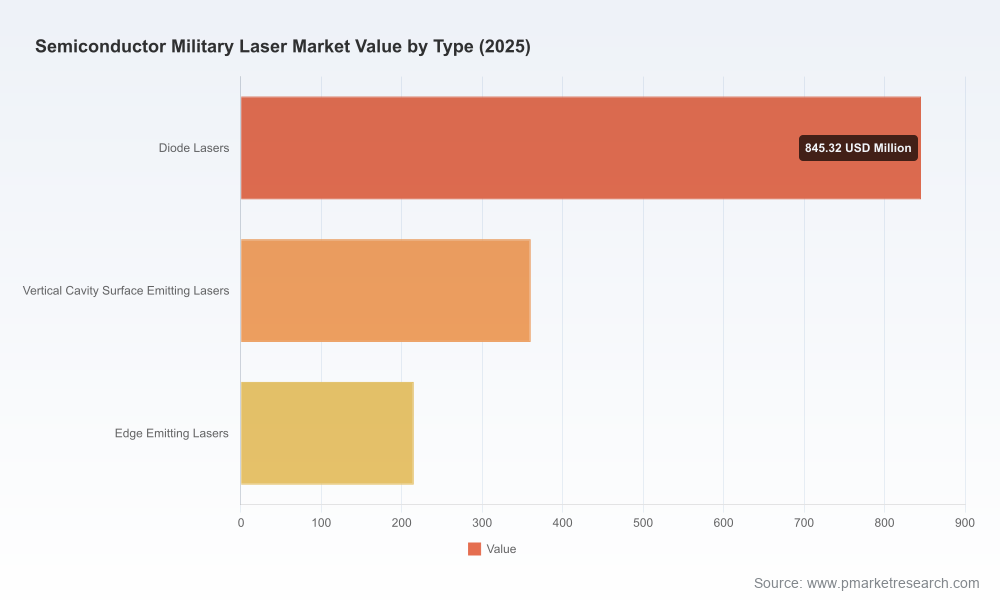
Technology segmentation differentiates the market into diode lasers, vertical cavity surface emitting lasers, and edge emitting lasers. Diode lasers represent the largest value center within the type breakdown, reflecting their role as direct emitters and pump sources for higher-level systems. Their dominance is tied to continuous improvements in brightness, wavelength stability, and packaging ruggedness. Vertical cavity surface emitting lasers carve out a specialized niche, particularly where compact form factors and two-dimensional array configurations support targeting and countermeasure functions. Edge emitting lasers occupy a more focused segment, often selected for applications requiring specific beam characteristics and integration geometries. Decision-makers evaluating vendor partnerships or internal technology roadmaps should assess not just current share, but the rate at which each technology type is advancing in power scaling, reliability under field conditions, and compatibility with downstream beam control architectures.
Application segmentation highlights how end-use requirements shape procurement priorities. Target designation and range finding commands the largest application share, driven by sustained modernization of electro-optical systems across ground, airborne, and maritime platforms. Directed energy weapons subsystems form the second-largest application cluster, reflecting the defense community accelerating investment in high-energy laser capabilities for counter-drone, counter-missile, and asymmetric threat mitigation. Lidar and navigation applications represent a growing but more specialized pool, often linked to platform autonomy and precision guidance. Laser countermeasures, while smaller in current value, are experiencing heightened interest as non-kinetic protection becomes a priority across multiple service branches. Strategic planners should note that application demand is not purely technology-driven; it is heavily influenced by program timelines, test and evaluation milestones, and the willingness of prime contractors to integrate semiconductor laser components into broader weapon system architectures.
Regional segmentation illustrates how geography distributes value and risk. North America accounts for the largest regional share, anchored by sustained defense budgets, mature prime contractor ecosystems, and a deep base of photonics suppliers. Asia Pacific holds the second-largest share, reflecting both domestic defense modernization efforts and a rapidly expanding semiconductor manufacturing base. Europe represents a meaningful contributor, supported by multinational defense programs and precision photonics heritage. The rest of world segment, while smaller in current scale, contains emerging demand centers and supply chain diversification opportunities. Importantly, regional dynamics are not static; export control regimes, allied cooperation frameworks, and domestic content requirements are actively reshaping where production, integration, and final assembly occur. Organizations should evaluate regional exposure not only in terms of current revenue but also in terms of regulatory adjacency, sourcing resilience, and the potential for dual-use technology cooperation.
Competitive Architecture: A Concentrated Field of Primes, Specialists, and Component Innovators
The competitive landscape for semiconductor military lasers is characterized by a blend of large defense primes, specialized photonics manufacturers, and component-focused innovators. Market concentration metrics indicate that the top three competitors collectively hold approximately 42.5 percent of market value, while the top five capture roughly 61.2 percent. This structure suggests a market where scale, program access, and integration depth confer advantages, but where specialized technology leaders can still command strategic importance through niche performance, reliability, or supply chain uniqueness.
Several organizations define the current competitive frontier. Northrop Grumman Corporation, based in Falls Church, Virginia, continues to develop and integrate high-energy laser systems for directed energy weapons, including semiconductor laser components and thermal management solutions designed for counter-UAS and high-power beam combining applications. RTX Corporation (Raytheon), headquartered in Arlington, Virginia, delivers high-energy laser weapon systems such as HELWS and DE M-SHORAD, leveraging semiconductor laser technology for shipboard, ground, and airborne directed energy defense against drones, missiles, and asymmetric threats. Lockheed Martin Corporation, located in Bethesda, Maryland, develops high-energy laser systems for naval and ground platforms, integrating semiconductor diode lasers as pumps or direct sources in directed energy weapons for counter-drone and missile defense missions.
nLIGHT, Inc., from Vancouver, Washington, specializes in high-power semiconductor lasers and fiber lasers for directed energy, delivering 50kW-class systems for Army DE M-SHORAD and advancing coherent beam combining under HELSI for megawatt-scale military applications. Power Technology, Inc., based in Alexander, Arkansas, manufactures high-performance laser diode modules and semiconductor lasers for military defense, including ruggedized solutions for targeting, illumination, and directed energy applications. NUBURU Inc., operating from Centennial, Colorado, focuses on high-power blue semiconductor lasers for portable directed-energy platforms, including counter-drone dazzler systems and non-kinetic effects for defense and security. L3Harris Technologies Inc., headquartered in Melbourne, Florida, supplies military laser systems and electro-optical components, including semiconductor laser-based solutions for targeting, countermeasures, and directed energy integration.
On the component and materials side, Coherent Corp., based in Santa Clara, California, develops semiconductor lasers and components used in high-power military laser systems, including pumps for fiber lasers and direct diode solutions for defense applications. IPG Photonics Corporation, from Oxford, Massachusetts, produces high-power fiber and semiconductor lasers serving as pump sources and direct emitters in military directed energy and defense laser systems. Jenoptik AG, headquartered in Jena, Germany, supplies precision semiconductor laser diodes and photonic components for military applications, including defense and aerospace laser systems.
Recent developments reinforce the pace of activity. In March 2026, NUBURU Inc. completed a proof-of-concept for a portable directed-energy laser dazzler platform using semiconductor laser expertise for counter-drone defense applications. Also in March 2026, BluGlass Limited entered a multi-phased development program with a U.S. tier-1 defence prime for custom visible GaN DFB lasers and gain chips, receiving an initial order and signaling the growing importance of visible-wavelength semiconductor sources in dual-use defense and aerospace applications. In February 2026, Power Technology, Inc. highlighted high-performance laser diode modules for military defense applications, emphasizing ruggedized solutions for extreme environments. Earlier, in December 2025, NUBURU Inc. announced a strategic alliance and network contract with Maddox Defense and Tekne S.p.A. to advance next-generation drone and directed-energy technologies using semiconductor laser platforms.
Strategic implication for 2026: Competitive advantage will increasingly depend on the ability to integrate component-level performance with system-level reliability, thermal management, and programmatic access. Primes that can secure stable supplies of high-brightness diode arrays, while simultaneously advancing beam combining and packaging techniques, are positioned to win long-cycle directed energy programs. Component specialists that demonstrate ruggedization, wavelength precision, and supply continuity can become indispensable partners. Organizations should map their supplier and partner ecosystems against these dynamics, identifying where concentration risk exists and where diversification or strategic alliances could strengthen resilience.
Market Dynamics and Structural Forces Shaping the 2026 to 2032 Window
Beyond competitive positioning, several structural forces will influence how the market evolves. These dynamics are not peripheral; they directly affect sourcing strategies, partnership models, and the realism of deployment timelines.
Regulatory and export control environments play a defining role. High-power semiconductor laser stacked arrays with specific wavelength and power parameters are subject to export controls under the Wassenaar Arrangement dual-use list and U.S. EAR/ITAR frameworks for military applications. This regulatory overlay shapes how technology can be shared across borders, how joint development programs are structured, and which supply chain nodes can be located in which jurisdictions. Strategic planners should treat compliance architecture as a competitive capability, not a back-office function, because the ability to navigate dual-use controls can accelerate or constrain program participation.
Critical material dependencies introduce supply chain risk that is increasingly central to procurement planning. Gallium is a critical material used in the fabrication of high-power semiconductor lasers for directed energy weapons, and U.S. supply chain vulnerabilities have been noted due to reliance on foreign sources and Chinese export restrictions. This dependency is especially relevant for diode laser production, where material purity, wafer availability, and price stability can influence cost structures and delivery commitments. Organizations should evaluate gallium sourcing strategies, consider qualified alternative suppliers where feasible, and incorporate material risk into program profitability models.
Government investment and program roadmaps provide a powerful demand signal. The U.S. Department of Defense continues multi-year investments in directed energy programs, including semiconductor laser scaling initiatives such as HELSI for 500kW to megawatt-class performance. Semiconductor lasers serving as pump sources are foundational to scaling solid-state and fiber laser directed energy weapons in U.S. military programs like DE M-SHORAD and HELIOS. These program commitments create a multi-year pipeline of requirements, but they also introduce stage-gate risk: technologies must demonstrate readiness, reliability, and integration compatibility to progress from research to fielding. Decision-makers should align their technology development and qualification plans with the milestones implied by these roadmaps, recognizing that program continuity can shift with budget cycles and test outcomes.
Standardization and research solicitations are shaping the next generation of component architectures. Ongoing U.S. military SBIR/STTR topics target development of bright blue semiconductor laser arrays and photonic crystal surface-emitting lasers for compact, high-brightness military directed energy and machining applications. These solicitations signal where the defense community is seeking breakthroughs in brightness, form factor, and integration efficiency. For innovators and suppliers, alignment with these research priorities can open pathways to prototype funding, qualification opportunities, and eventual program inclusion. For primes and system integrators, monitoring these topics helps anticipate emerging component options and potential supply chain entrants.
Why This Research Is a Strategic Input for 2026 Decision-Making
The Worldwide Semiconductor Military Laser Market research is designed to move beyond headline figures and provide the operational intelligence that leadership teams need to make informed choices in a complex, regulated, and rapidly scaling environment. The study integrates historical analysis, forecast modeling, segmentation depth, competitive profiling, and dynamic context into a cohesive decision-support framework.
Practically, the report delivers actionable content across multiple dimensions. It maps the revenue trajectory from 2020 through 2032, giving executives a calibrated view of where the market has been and where it is heading, including the approximate midpoint reached in the base year and the scale anticipated by the end of the forecast window. It breaks down the market by type, application, and region so that strategy teams can identify which value pools align with their capabilities, customers, and risk tolerance. It profiles the core competitors shaping the landscape, describing their headquarters, focus areas, and strategic activities, which supports benchmarking, partnership evaluation, and competitive positioning. It also documents recent developments and structural dynamics, including regulatory constraints, critical material considerations, government program investments, and research priorities, all of which influence how value is created and captured over the forecast period.
For 2026 specifically, the research supports several high-priority decisions. It helps organizations assess whether to deepen commitments in diode laser platforms, vertical cavity surface emitting lasers, or edge emitting lasers based on the growth profile and application alignment of each type. It aids in evaluating geographic exposure and supply chain diversification strategies, particularly given the concentration of value in certain regions and the regulatory sensitivities attached to high-power semiconductor laser technologies. It informs partnership and M&A screening by clarifying which companies are building scale, which are advancing critical component technologies, and which are forming alliances that could reshape access to programs. It also supports risk planning by highlighting export control frameworks, material dependencies, and the stage-gate nature of directed energy program progression.
Importantly, the study is structured to enable scenario-based planning. Because the market is influenced by program wins, technology readiness, regulatory interpretation, and material availability, a single-point forecast is insufficient for robust strategy. The report framework allows decision-makers to test assumptions about deployment timing, regional demand shifts, and competitive responses, helping to identify where flexibility, hedging, or accelerated investment may be warranted.
Looking Ahead: Positioning for a Decade of Directed Energy Acceleration
The worldwide semiconductor military laser market is entering a phase in which technological performance, programmatic access, and supply chain resilience will jointly determine competitive outcomes. The forecast trajectory suggests a market that more than doubles from its base-year level by 2032, with a growth rate that reflects sustained defense investment and the operational need for scalable directed energy and electro-optical capabilities. Yet growth alone does not guarantee value capture. The organizations that thrive will be those that treat this market as a system of interdependent choices: which technology types to prioritize, which applications to target, which regions to serve or avoid, which suppliers to qualify, and how to build compliance and material resilience into the core of their operating models.
For senior leadership, the strategic imperative in 2026 is to convert market awareness into structured action. That means aligning R&D and qualification efforts with the technology and application segments most likely to scale, stress-testing supplier and material strategies against regulatory and geopolitical variables, and evaluating competitive moves not just on the basis of current share but on the basis of program access, integration depth, and alliance positioning. It also means recognizing that concentration in the market creates both opportunities and vulnerabilities, and that strategic partnerships can be as important as internal capability development.
PW Consulting Worldwide Semiconductor Military Laser Market research provides the depth, structure, and contextual intelligence required to make those decisions with greater confidence. By combining historical analysis, forward-looking forecasts, segmentation clarity, competitive profiling, and dynamic risk factors into a single integrated view, the study equips organizations to navigate a market where the next wave of value creation will belong to those who can anticipate, adapt, and execute with precision.
For detailed analysis of this topic, please visit the official page:Worldwide Semiconductor Military Laser Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek