
Navigating the Aerodynamic Crossroads: Strategic Imperatives in the 2026 Aircraft Wind Tunnel Testing Services Market
Executive Summary: A Market at the Inflection Point
The aircraft wind tunnel testing services market stands at a critical juncture as aerospace manufacturers navigate post-pandemic supply chain normalization, accelerating next-generation airframe development, and tightening regulatory certification pathways. Our latest comprehensive study maps the trajectory of this essential engineering ecosystem through 2032, positioning decision-makers to anticipate capacity constraints, pricing dynamics, and competitive repositioning ahead of the curve. The global market commanded an estimated valuation in 2025, having expanded steadily from its 2020 baseline, and is projected to sustain a compound annual growth rate of 5.25 percent across the 2026 to 2032 forecast horizon. This growth trajectory is not merely a function of incremental airframe production; it reflects structural shifts in how airframe designers validate performance, how regulatory bodies enforce empirical aerodynamic proof, and how specialized testing providers align their facility portfolios with emerging flight regimes.
Aircraft Wind Tunnel Testing Services Market
For enterprise strategists, program managers, and investment committees operating in aerospace and defense, the wind tunnel testing services sector represents both a critical dependency and a competitive differentiator. Physical aerodynamic validation remains irreplaceable in the certification lifecycle, and the organizations that secure timely access to appropriately configured test sections, specialized instrumentation, and experienced engineering support will dictate the pace of their development programs. This insight brief previews the analytical architecture of our full market research, outlining the macro dynamics, competitive architecture, and operational realities that will shape procurement decisions, partnership strategies, and capacity planning throughout the remainder of the decade.
Aircraft Wind Tunnel Testing Services Market
Macro Trajectory and Demand Drivers: Why the Numbers Matter for 2026 Planning
The market's historical expansion from 2020 through 2025 laid a foundation of measured but consistent growth, with annual valuations progressing through the mid- to high-six-hundred-million-dollar range by the end of the base year. Looking forward, the forecast period-through 2032-paints a picture of sustained momentum, with the market advancing toward the high-eight-hundred-million to near-one-billion-dollar threshold by the close of the projection window. This 5.25 percent CAGR reflects a market that is neither experiencing explosive disruption nor stagnating under saturation; rather, it is expanding in step with broader aerospace development cycles, regulatory mandates, and the gradual commercialization of advanced flight concepts that demand rigorous aerodynamic characterization.
Aircraft Wind Tunnel Testing Services Market
Several converging forces are amplifying demand for specialized wind tunnel testing services. Regulatory frameworks administered by major aviation authorities continue to mandate empirical aerodynamic validation through physical testing as a cornerstone of aircraft certification and airworthiness standards. These requirements are not static; evolving safety, performance, and environmental criteria are lengthening validation protocols and increasing the scope of aerodynamic characterization required before type certification can be granted. Concurrently, the capital intensity of maintaining and operating large transonic and supersonic facilities creates a natural barrier to entry that concentrates testing capacity among established infrastructure operators. The construction of a large transonic wind tunnel alone represents a capital outlay exceeding half a billion dollars, accompanied by substantial ongoing operational expenditures. This economic reality means that testing capacity is neither easily replicated nor rapidly expanded, reinforcing the strategic importance of long-term facility access agreements and diversified testing partnerships.
Beyond regulatory and infrastructure fundamentals, the market is being reshaped by technology and sustainability imperatives. Increasing emphasis on hypersonic research, sustainable aviation fuel compatibility assessment, and unconventional airframe configurations-such as blended wing body architectures and advanced high-lift systems-is driving higher utilization of transonic and supersonic test regimes. Simultaneously, the rapid maturation of unmanned aerial systems and electrified vertical takeoff and landing platforms is widening the customer base for low-speed and specialized aerodynamic testing. These dynamics create a complex demand landscape in which testing providers must balance traditional commercial and military airframe programs with emerging platforms that require different test section geometries, instrumentation packages, and acoustic or propulsion-related evaluation capabilities.
Service Portfolio Evolution and Aircraft Application Realities
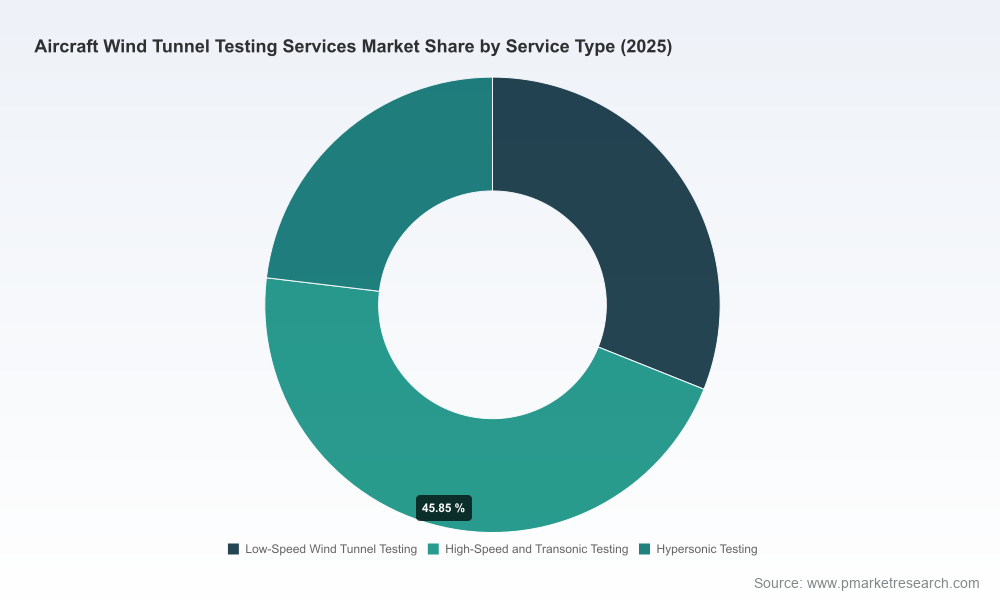
The wind tunnel testing services market is structurally diversified across service types and aircraft applications, and understanding how these categories interact is essential for strategic procurement and capacity planning. Low-speed testing remains foundational for takeoff and landing configuration analysis, high-lift system validation, and stability assessments across a range of scaled platforms. High-speed and transonic testing constitutes a major share of specialized service demand, supporting cruise efficiency optimization, shock wave management, and propulsion integration across modern transport and fighter categories. Hypersonic testing, while a smaller component of current service utilization, is gaining strategic relevance as defense programs and advanced research initiatives push toward higher flight regimes, demanding specialized facilities capable of replicating extreme Mach conditions with precise instrumentation and data acquisition.
From an aircraft application perspective, commercial airframe development continues to drive substantial testing volume, particularly as manufacturers pursue aerodynamic refinements, drag reduction initiatives, and next-generation high-lift configurations. Military aircraft programs represent an equally significant demand pillar, with testing requirements spanning store separation, dynamic stability, propulsion integration, and acoustic characterization across a diverse portfolio of manned and unmanned platforms. The UAV and eVTOL segment reflects a rapidly evolving application category, where scaled-model testing, low-turbulence environments, and specialized instrumentation support the iterative development of distributed electric propulsion architectures, unconventional rotor systems, and advanced control-surface configurations.
What distinguishes a high-value testing engagement in this environment is not merely access to a tunnel, but the integration of model design, fabrication, instrumentation, calibration, and data interpretation into a coherent engineering workflow. Providers that offer turn-key model manufacturing, precision positioning systems, force and moment balances, and calibrated measurement protocols reduce program risk and accelerate the feedback loop between test campaigns and design iteration. As development timelines compress and certification pathways become more data-intensive, the ability to execute multi-configuration test matrices with minimal downtime and high measurement fidelity becomes a decisive factor in vendor selection.
Competitive Landscape: Strategic Positioning Among Key Providers
The competitive architecture of the wind tunnel testing services market is characterized by a mix of independent testing specialists, OEM-affiliated testing divisions, and multinational research organizations operating specialized facilities across multiple flight regimes. Market concentration metrics indicate a moderately consolidated landscape, with the top three participants commanding a notable share of total service revenue and the top five collectively representing a substantial majority. This concentration reflects the capital intensity of facility ownership, the technical expertise required to execute complex test programs, and the long-term client relationships that develop around recurring airframe development cycles and certification campaigns.
Several organizations define the strategic contours of this competitive environment. Calspan Corporation operates transonic testing capability with a substantial test section and a comprehensive suite of model manufacturing, positioning, balance, and calibration services tailored to aerospace applications. Its recent contract award with the U.S. Naval Test Pilot School underscores the enduring importance of flight-adjacent testing support and the role of independent providers in sustaining training, evaluation, and validation pipelines. Boeing Testing Services leverages a multi-facility portfolio that spans transonic, polysonic, subsonic, and icing tunnels, enabling customized aerodynamic, propulsion, and acoustic testing for a broad range of aircraft programs. The integration of testing services within an OEM ecosystem provides distinctive advantages in proprietary development workflows while also positioning the organization to serve external customers with specialized capability requirements.
The German-Dutch Wind Tunnels organization provides advanced testing coverage spanning subsonic to supersonic regimes, with specialized sites optimized for takeoff and landing configuration analysis and recent expansions into adjacent test sections that broaden its service envelope. Its recent rotor active twist testing and contributions to hydrogen-electric aircraft evaluations illustrate how established wind tunnel operators are adapting their portfolios to emerging propulsion and aerodynamic challenges. ONERA's Modane-Avrieux center operates multiple facilities capable of aerodynamic testing up to hypersonic speeds, supporting both civil and military programs and reinforcing the role of national research organizations in maintaining high-regime testing capacity. Aircraft Research Association Limited, an independent specialist based in the United Kingdom, offers comprehensive testing services including transonic capability for advanced aircraft and aerospace concepts, with recent model testing activity demonstrating continued relevance in research-grade aerodynamic validation.
Regional and specialized providers further diversify the competitive field. RUAG Aerodynamics operates a large low-speed wind tunnel and complementary facilities, supporting full development cycle activities from model design through instrumentation and testing. AeroTEC specializes in the design, fabrication, instrumentation, and testing of complex wind tunnel models, with program management capabilities that align with the needs of complex, multi-phase development campaigns. Lockheed Martin's low-speed and high-speed wind tunnel operations support aerodynamic force and moment testing, store separation, propulsion integration, and dynamic stability assessments for aircraft and missiles, reflecting the dual-use nature of high-performance testing infrastructure. San Diego Wind Tunnel provides a privately operated low-speed environment optimized for scaled jet aircraft, unmanned platforms, and low-turbulence aerospace testing, serving a niche but growing segment of scaled-model and advanced air mobility development programs.
Strategic positioning in this landscape hinges on several differentiating factors. Facility range and test section configuration determine which flight regimes and airframe scales can be accommodated. Instrumentation breadth and calibration rigor influence data quality and repeatability. Model fabrication and program management capabilities affect turnaround time and integration complexity. Recent activity across the competitive set-new facility sections, modernization of test systems, research-grade model campaigns, and long-term service contracts with training and evaluation institutions-reflects a market in which providers are actively aligning their capabilities with the next generation of airframe, propulsion, and certification challenges.
Regulatory, Economic, and Technological Dynamics Shaping Demand
The wind tunnel testing services market does not operate in isolation; it is deeply embedded in regulatory, economic, and technological ecosystems that influence test volume, service scope, and pricing dynamics. Empirical aerodynamic validation remains a non-negotiable element of certification pathways administered by major aviation authorities, and the stringency of contemporary safety and performance criteria continues to expand the scope of testing required to demonstrate airworthiness. As regulatory expectations evolve, programs that anticipate validation requirements early and integrate testing into design iteration cycles are better positioned to manage certification timelines and mitigate the risk of late-stage redesign.
Infrastructure economics also exert a powerful influence on market dynamics. The substantial capital investment required to construct and maintain large transonic and supersonic facilities, combined with high ongoing operational costs, means that testing capacity is strategically scarce. This scarcity reinforces the value of long-term access agreements, diversified service portfolios, and collaborative testing arrangements that spread utilization across multiple programs and customers. For airframe developers and platform integrators, the practical implication is clear: securing reliable access to appropriately configured testing capacity is a program-critical activity that warrants early planning and sustained partnership investment.
Technological and sustainability trends are further reshaping testing demand. The push toward advanced airframe configurations, sustainable fuel compatibility assessment, and high-speed flight regimes is increasing the utilization of transonic, supersonic, and specialized test facilities. At the same time, the growth of unmanned and electrified vertical takeoff platforms is expanding the low-speed testing segment and placing new demands on scaled-model fidelity, instrumentation, and aerodynamic characterization. These trends are not isolated; they interact with broader program economics, supply chain readiness, and the pace of certification activity, creating a dynamic environment in which testing providers and customers alike must continuously align their capabilities with evolving development priorities.
What the Full Study Delivers: Operational Intelligence for 2026 Decision-Making
The complete market research study is designed to translate these macro dynamics into actionable intelligence for procurement, strategy, and investment decisions. Beyond the headline market sizing and growth trajectory, the report provides a structured examination of service type segmentation, aircraft application demand patterns, and regional market architecture, enabling readers to contextualize their own program portfolios within broader industry utilization trends. The analysis integrates recent developments across the competitive set, including facility modernization initiatives, new test section openings, research-grade model campaigns, and long-term service contracts, to illustrate how providers are repositioning their capabilities in response to emerging aerodynamic and certification challenges.
Operational content extends to the practical realities of testing engagement, including the relationship between facility configuration and test regime suitability, the role of instrumentation and model fabrication in program efficiency, and the economic factors that influence capacity availability and service pricing. The study also examines the regulatory and certification environment in which testing services are consumed, mapping the empirical validation requirements that drive demand and the evolving performance criteria that expand testing scope. By combining quantitative market structure with qualitative competitive and operational analysis, the report equips readers to evaluate vendor capabilities, anticipate capacity constraints, and design procurement strategies that align with multi-year development and certification timelines.
Strategic Recommendations for 2026 and Beyond
As the market progresses through the 2026 to 2032 forecast period, several strategic priorities merit attention. First, organizations should treat wind tunnel testing capacity as a program-critical resource and secure access agreements early in the development lifecycle, particularly for programs that require transonic or supersonic testing where facility availability is structurally constrained. Second, procurement strategies should evaluate providers not solely on tunnel availability but on the integration of model design, fabrication, instrumentation, calibration, and data interpretation capabilities, as these elements directly influence test turnaround, measurement fidelity, and design iteration speed. Third, competitive intelligence should account for the evolving portfolios of both independent specialists and OEM-affiliated testing organizations, recognizing that recent facility expansions, test system modernizations, and research-grade campaigns are reshaping which providers can accommodate emerging airframe, propulsion, and certification requirements.
Fourth, sustainability and advanced-configuration development trajectories should be factored into testing demand forecasts. Programs exploring blended wing body architectures, sustainable fuel compatibility, high-lift optimization, or high-speed flight regimes will increasingly depend on transonic, supersonic, and specialized test capabilities, and engagement strategies should reflect the growing utilization of these regimes. Finally, regulatory planning should be integrated with testing schedules from the outset, ensuring that empirical validation requirements are mapped to test campaigns in a manner that supports certification timelines and minimizes the risk of late-stage rework.
Conclusion: Positioning for the Next Wave of Aerodynamic Validation
The aircraft wind tunnel testing services market is entering a phase of sustained, structurally supported growth driven by regulatory validation requirements, infrastructure scarcity, and the expanding aerodynamic complexity of next-generation airframes and propulsion systems. The 5.25 percent CAGR projected through 2032 reflects a market that is expanding in alignment with broader aerospace development cycles rather than in response to transient demand spikes, making it a reliable subject for long-range strategic planning. For enterprises operating in commercial aerospace, defense, and advanced air mobility, the ability to navigate this market with clear intelligence on capacity dynamics, competitive positioning, and service integration will directly influence program velocity, certification outcomes, and competitive differentiation.
This insight brief has outlined the strategic contours of the market and the operational realities that shape testing demand and provider selection. The full research study builds on this foundation with detailed market structure analysis, competitive profiling, recent development tracking, and practical guidance for capacity planning and procurement strategy. For decision-makers who require comprehensive visibility into market sizing, segmentation dynamics, and provider capability mapping, the complete report offers the depth necessary to translate aerodynamic validation requirements into resilient, forward-looking business strategy.
For detailed analysis of this topic, please visit the official page:Aircraft Wind Tunnel Testing Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek