
Global Opto-Isolators Market Intelligence: Strategic Decision-Making Framework for 2026
The opto-isolator market stands at a critical inflection point. Driven by the convergence of electric vehicle architectures, industrial 4.0 automation, and stringent safety regulations, isolation technology has transitioned from a passive protection component to a strategic enabler of next-generation power and signal systems. For procurement leaders, R&D directors, and corporate strategists, navigating 2026 requires more than headline figures. It demands granular visibility into regional supply constraints, type-specific performance trade-offs, application-driven demand shifts, and the competitive maneuvers reshaping the supply base. Our latest Worldwide Opto-Isolators Market research translates this complexity into an actionable intelligence framework, equipping enterprises with the structural clarity required to allocate capital, secure supply, and position product roadmaps with precision.
Worldwide Opto-Isolators Market
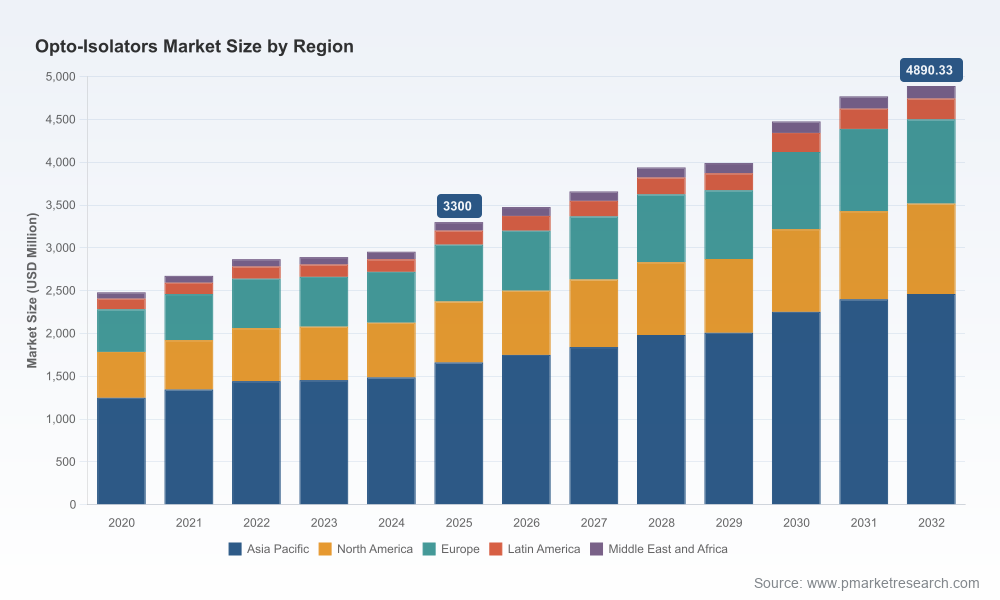
This market landscape operates against a backdrop of measurable expansion. Over the historical evaluation window, the sector demonstrated consistent upward momentum, recovering from cyclical volatility and accelerating through recent quarters. The base-year valuation anchors the analysis, while the forward trajectory maps a deliberate climb toward a multi-thousand-million-dollar endpoint by the end of the forecast horizon. The annualized growth rate across this period underscores a market that is neither speculative nor stagnant, but structurally expanding at a pace that rewards early positioning and penalizes reactive procurement. Understanding the mechanics behind this trajectory, rather than the headline numbers alone, is what separates strategic advantage from costly misalignment.
Worldwide Opto-Isolators Market
Why 2026 Demands a Refined Market Lens
The year 2026 functions as a decisive bridge between recent normalization and the long-cycle expansion ahead. Several intersecting forces converge to make granular market intelligence non-negotiable for enterprise decision-making. First, architectural shifts in automotive electrification and renewable energy integration are re-calibrating isolation requirements around higher voltage differentials, faster switching transients, and extended thermal envelopes. Second, industrial automation deployments, particularly in motor drive inverters, programmable logic controllers, and smart grid interfaces, are scaling isolation density across production floors. Third, regulatory and standards evolution is redefining compliance thresholds, altering qualification pathways, and influencing component selection at the design stage.
Worldwide Opto-Isolators Market
Simultaneously, supply-side conditions introduce a layer of operational complexity that offsets otherwise favorable demand signals. Raw material dynamics, particularly around silicon fabrication inputs, have tightened availability and influenced cost structures across the opto-electronic supply chain. Substrate availability for specialized isolation devices has extended procurement lead times for high-performance variants, compelling design engineers to balance performance specifications against availability risk. Pricing behavior has also adjusted, with certain high-grade digital isolation components reflecting the combined effects of material constraints, qualification rigor, and application-specific performance premiums. These dynamics do not merely affect unit economics; they reshape sourcing strategies, inventory planning, and technology roadmap prioritization.
Within this environment, market intelligence serves a dual purpose: it reveals where structural growth is concentrated, and it exposes where supply constraints, regulatory mandates, and competitive maneuvers will create friction. Enterprises that treat isolation components as commodities risk being exposed to lead-time volatility, specification mismatches, and margin compression. Enterprises that understand the segmentation mechanics, the application demand map, and the competitive differentiation strategies can design around constraints, negotiate from a position of clarity, and align product development with durable demand vectors.
Decoding the Competitive Architecture
The opto-isolator supply base is characterized by a concentrated yet highly differentiated competitive landscape. A handful of multinational semiconductor and opto-electronic manufacturers command a substantial share of global revenue, while a broader tier of specialized and regional players competes on application specificity, qualification readiness, and supply agility. This concentration creates both opportunity and caution for enterprise buyers. On one hand, scale players drive consistent roadmap investment, maintain broad qualification portfolios, and offer platform-level continuity across product generations. On the other hand, concentrated supply can amplify exposure to single-source risk, pricing leverage, and roadmap synchronization challenges.
Key incumbents operate across distinct strategic territories. Toshiba Electronic Devices & Storage Corporation maintains a broad opto-isolator portfolio anchored on its TLP series, with emphasis on high-speed digital, power, and industrial variants deployed in power supplies, motor drives, and inverters. Broadcom Inc. leverages its HCPL and ACPL series to address high-reliability environments spanning industrial automation, renewable energy infrastructure, and electric vehicle platforms. Vishay Intertechnology, Inc. contributes VOS and IL series devices, including gate drivers and high-voltage isolators, serving consumer electronics, telecommunications, and automotive applications. Lite-On Technology Corporation focuses its LTV series on power management, medical devices, and home appliance isolation requirements. Everlight Electronics Co., Ltd. supplies EL series components optimized for signal transmission in industrial controls, smart grids, and consumer products.
Beyond these scale-oriented players, application and performance specialists add critical depth to the supply architecture. ON Semiconductor (onsemi) targets automotive, industrial, and safety-critical isolation through its FOD and NCV series. Infineon Technologies AG pushes the performance frontier with optoMOS and EiceDRIVER solutions designed for gate driving in silicon carbide and gallium nitride power systems, as well as EV charging infrastructure. Renesas Electronics Corporation supports high-speed interface requirements in MCU communications, factory automation, and telecommunications through its PS and RV series. Sharp Corporation addresses logic gate and high-output isolation needs in printers, medical equipment, and security systems via its PC series. Isocom Components Ltd. occupies a specialized niche, delivering MOC and TLP-compatible devices for military, aerospace, and high-reliability industrial deployments where qualification and robustness take precedence over volume optimization.
Recent corporate activity illustrates how this competitive set is actively reshaping the market. Infineon advanced the high-voltage isolation frontier with the introduction of a 6.5 kVrms opto-driver tailored for SiC MOSFET applications in EV and solar inverters. Toshiba moved toward space-constrained industrial designs by announcing sampling of an ultra-small quad-channel optocoupler intended for compact control architectures. onsemi progressed automotive qualification on a high-speed optocoupler, aligning product readiness with the stringent reliability expectations of vehicle-grade isolation. Broadcom locked in supply continuity through a multi-year agreement for gate driver components with a major EV manufacturer, signaling the strategic importance of guaranteed availability in high-growth end markets. Vishay reinforced industrial applicability by publishing updated documentation extending the operating temperature range for a core isolate series. These moves are not isolated product announcements; they are indicators of where value is being captured, where qualification investment is flowing, and where supply relationships are hardening ahead of demand acceleration.
For enterprises, the strategic implication is clear: competitive analysis must extend beyond market-share narratives to include roadmap cadence, qualification coverage, application fit, and supply-relationship durability. The winners in 2026 and beyond will be those who can match isolation performance to application requirements while insulating their programs from supply volatility and qualification delays.
Segmentation Dynamics Without the Noise
Effective procurement and design strategy depend on understanding how the market fragments across type, application, and geography, and how those fragments interact with supply realities. The opto-isolator category is not monolithic. Different output architectures serve different performance envelopes. Digital and high-speed logic gate variants address fast signal propagation, noise immunity, and interface isolation in microcontroller and communication pathways. Power-oriented outputs, including triac and SCR configurations, manage switching isolation in load control and inverter environments. Linear optocouplers occupy precision signal transfer roles where linearity and low distortion matter more than raw switching speed. Each type carries distinct design trade-offs in bandwidth, voltage handling, propagation delay, and thermal behavior, and those trade-offs directly influence component selection in actual system architectures.
The application map further clarifies where demand momentum originates. Industrial automation remains a foundational driver, reflecting the proliferation of motor drives, programmable controllers, robotics interfaces, and distributed control systems that rely on galvanic separation for safety and noise management. Automotive and electric vehicle applications represent a structurally expanding demand pool, fueled by battery management isolation, onboard charger interfaces, powertrain control, and high-voltage safety separation. Telecommunications infrastructure continues to require isolation for signal integrity, power conversion, and interface protection across network equipment. Consumer electronics sustain steady, volume-based demand where cost, size, and baseline safety requirements shape selection. Medical devices, while smaller in absolute volume, impose elevated reliability, longevity, and safety expectations that influence qualification pathways and component grade selection.
Geographically, demand and supply footprints diverge in ways that matter for sourcing strategy. Asia Pacific reflects the largest revenue concentration, consistent with the scale of electronics manufacturing, industrial infrastructure investment, and automotive production activity across the region. North America and Europe each contribute substantial but distinctly structured demand profiles, influenced by regional automation adoption, automotive electrification programs, telecom upgrade cycles, and regulatory environments. Latin America and the Middle East and Africa represent smaller but growing contribution vectors, often tied to specific industrial modernization programs, infrastructure development, and selective electronics adoption pathways. The practical takeaway is not to treat these regions as interchangeable. Supply chain routing, qualification expectations, logistics reliability, and localized support capabilities vary meaningfully, and sourcing strategies must account for where devices are manufactured, where they are qualified, and where lead-time risk concentrates under stressed conditions.
Because type, application, and region intersect, enterprise decisions cannot rely on aggregate market size alone. A component suited to consumer electronics volume may not meet industrial temperature or reliability expectations. A high-performance isolation device optimized for SiC gate driving may carry procurement constraints that make it impractical for cost-sensitive consumer designs. A region with strong demand may simultaneously face the most acute supply tightness. Our analysis preserves these intersections in a structured format, enabling users to evaluate trade-offs without collapsing the market into oversimplified aggregates.
Forces Reshaping the 2026–2032 Horizon
The forecast window is shaped by a combination of demand creation, supply-side constraints, standards evolution, and geopolitical friction. Demand-side pull will continue to strengthen around electrification, automation scale-up, and network infrastructure modernization. As system architectures move toward wider voltage ranges, faster switching, and more distributed control nodes, the need for reliable galvanic isolation expands across both power and signal domains. This creates a durable growth foundation, but durability does not imply uniform ease of execution.
On the supply side, material and substrate dynamics are introducing measurable friction. Silicon wafer pricing pressure has emerged from tight fabrication availability, influencing cost trajectories across opto-electronic production. For specialized isolation devices that depend on specific substrate characteristics, availability constraints have extended lead times, especially for high-CTI models where performance integrity is paramount. These supply conditions have translated into pricing adjustments for certain high-grade digital isolators, reflecting the combined weight of material cost, qualification overhead, and application-driven performance premiums. Enterprises planning multi-year product cycles must therefore factor not only unit cost, but also procurement predictability, qualification lead time, and the risk of specification substitution under constrained supply.
Regulatory and standards activity adds another layer of strategic relevance. Safety and insulation standards continue to evolve, with reinforced insulation expectations applying to higher-voltage isolation in consumer-facing equipment. Compliance is no longer a downstream check; it increasingly shapes upstream design decisions, component grading, and supplier qualification lists. Organizations that integrate standards trajectories into their early design and sourcing processes reduce the probability of late-stage redesign, qualification gaps, and market-entry delays.
Geopolitical and trade dynamics further complicate the operating environment. Export controls and technology-transfer restrictions can affect the availability of advanced isolation technologies across certain entity lists and regional supply paths. For global enterprises, this introduces a need to map supply resilience not only in terms of volume, but also in terms of eligible sourcing routes, documentation readiness, and alternative qualification pathways. The goal is not speculation, but preparedness: knowing which components, suppliers, and routes carry elevated exposure under current policy frameworks allows procurement and engineering teams to build contingency logic into their plans before constraints become operational emergencies.
Taken together, these forces define a market in which intelligence is not optional. Growth is real, but so is friction. The organizations that convert growth into advantage will be those that understand where demand is structurally anchored, how supply constraints propagate through lead times and pricing, how standards shape qualification, and how competitive players are positioning their roadmaps and supply relationships.
Inside the Worldwide Opto-Isolators Market Report
This research is designed as a decision-grade intelligence asset rather than a static market summary. It integrates historical baseline analysis, forward forecast structure, segmentation mechanics, competitive profiling, and supply-side context into a unified view that supports procurement, engineering, investment, and corporate strategy functions. The report’s value lies not only in the data it presents, but in the way it organizes that data into actionable interpretation.
At the core of the analysis is a structured market sizing and forecasting framework that traces the sector from the historical evaluation window through the base year and across the full forecast horizon. This framework establishes the growth arc and provides the quantitative backbone for scenario planning, capacity allocation, and investment prioritization. Rather than presenting figures in isolation, the analysis situates them within the operational context that drives them, allowing users to understand the direction, pace, and composition of market expansion.
Segmentation coverage is built to reflect real-world purchasing and design decisions. Type-based analysis distinguishes among output architectures and their associated performance envelopes, enabling evaluation of which device families align with specific speed, voltage, linearity, and reliability requirements. Application-based analysis maps demand across industrial automation, automotive and electric vehicles, telecommunications, consumer electronics, and medical devices, providing visibility into where volume and value are concentrated and how demand characteristics differ by end market. Regional analysis identifies the geographic distribution of revenue and demand activity, helping users assess where supply paths, qualification expectations, and market opportunities converge or diverge. Each segmentation dimension is presented in a way that supports cross-referencing, so that enterprises can evaluate, for example, how a particular type aligns with an application in a particular region without relying on blunt aggregate assumptions.
Competitive intelligence forms another essential pillar. The report profiles the major companies shaping the opto-isolator landscape, including Toshiba Electronic Devices & Storage Corporation, Broadcom Inc., Vishay Intertechnology, Inc., Lite-On Technology Corporation, Everlight Electronics Co., Ltd., ON Semiconductor, Infineon Technologies AG, Renesas Electronics Corporation, Sharp Corporation, and Isocom Components Ltd. These profiles are structured to support supplier evaluation, partnership screening, and competitive benchmarking. They synthesize each organization’s product orientation, application focus, and strategic posture, helping users understand not just who is active, but how each player is positioned relative to performance requirements, qualification coverage, and supply continuity.
To keep the analysis current and operationally relevant, the report integrates recent corporate developments that signal roadmap direction and supply-relationship strategy. These include high-voltage opto-driver introductions for SiC MOSFET applications, ultra-small quad-channel sampling for compact industrial controls, automotive-grade qualification achievements on high-speed optocouplers, multi-year supply agreements for gate driver components tied to EV manufacturing, and catalog updates that extend temperature capability for industrial use. Each development is interpreted in terms of its strategic implication, enabling readers to distinguish between routine product updates and moves that reflect deeper competitive positioning or supply-chain commitment.
Supply-side and market-dynamic context is woven throughout to ensure that users can connect demand analysis to procurement reality. Material availability, substrate constraints, lead-time behavior for high-performance models, pricing adjustments in specific digital isolation categories, standards-driven insulation requirements, and trade-policy exposure are all addressed as variables that influence sourcing strategy, design choice, and program risk. This context allows enterprises to evaluate market opportunity alongside execution risk, rather than treating the two as separate conversations.
The report is also structured to support multiple internal use cases. Procurement teams can use the segmentation and competitive content to refine approved vendor lists, assess alternative components, and build contingency sourcing logic. Engineering teams can leverage type and application analysis to align isolation selection with performance requirements and qualification constraints. Strategy and planning teams can use the forecast structure and market-dynamics context to prioritize investment, anticipate demand shifts, and stress-test assumptions against supply-side variability. By presenting the market in an integrated, decision-oriented format, the research enables cross-functional alignment rather than siloed interpretation.
Most importantly, the report preserves analytical depth without overwhelming the decision-maker with undifferentiated data volume. It focuses on the relationships that matter: which device types serve which applications, where regional demand and supply paths create advantage or exposure, how competitors are differentiating their portfolios, and how recent developments and market dynamics alter the practical calculus of sourcing and design. That is the difference between information and intelligence.
Strategic Implications for Enterprise Decision-Makers
For organizations operating in or adjacent to the opto-isolator market, 2026 is a year to convert visibility into execution discipline. The first imperative is to align component selection with application reality rather than with convenience or legacy habit. Isolation requirements differ sharply across motor drives, EV powertrains, telecom power stages, consumer devices, and medical equipment. Matching type, performance, and grade to the actual operating environment reduces rework, improves reliability, and strengthens qualification outcomes.
The second imperative is to treat supply continuity as a design input. With lead-time extensions affecting certain high-performance models and pricing adjustments visible in selected digital isolation categories, procurement strategies should incorporate qualification breadth, alternative-component mapping, and supply-route diversification where feasible. Where high-reliability or safety-critical applications are involved, qualification status and documentation readiness become as important as unit price.
The third imperative is to monitor competitive and standards signals as early indicators of market direction. Product launches in high-voltage SiC enablement, automotive qualification achievements, multi-year supply agreements with major EV manufacturers, and updated industrial temperature specifications all point to where investment and capability are flowing. At the same time, evolving insulation expectations and trade-policy constraints can alter the feasibility of certain sourcing routes or component grades. Early awareness of these signals reduces reaction time and improves strategic preparedness.
The fourth imperative is to use market segmentation as a planning tool rather than a reporting artifact. Regional demand distribution, application-level growth vectors, and type-level performance trade-offs should inform capacity planning, inventory policy, and roadmap prioritization. Enterprises that internalize these relationships are better positioned to allocate resources to the highest-value opportunities while building resilience against supply and compliance pressure points.
Conclusion: Converting Insight into Advantage
The worldwide opto-isolators market is expanding along a structurally supported trajectory, but the practical value of that expansion depends on how well organizations understand the market’s internal architecture. Growth is not uniform across types, applications, and regions. Supply constraints, pricing behavior, qualification requirements, standards evolution, and competitive positioning all influence how growth translates into real-world opportunity. Enterprises that rely on high-level summaries risk under-estimating execution complexity. Enterprises that use detailed, decision-oriented market intelligence can align sourcing, design, and strategy with the actual mechanics of the market.
Our Worldwide Opto-Isolators Market research is built to provide that intelligence. It combines historical and forecast market structure, segmentation analysis, competitive profiling, recent corporate developments, and supply-side context into a coherent framework for 2026 decision-making and beyond. For organizations seeking to secure supply, optimize component selection, evaluate competitors, or prioritize investment, the report offers the depth required to act with confidence. The full analytical breakdown, segmentation detail, regional and application-level intelligence, and proprietary forecast structure are available through the complete report, where the full scope of the market picture can be examined and applied to your specific strategic decisions.
For detailed analysis of this topic, please visit the official page:Worldwide Opto-Isolators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek