
Unlocking the Cold Chain: Strategic Intelligence for the 2026 Ice Cubers Market
The commercial ice manufacturing sector stands at a pivotal intersection of operational efficiency, regulatory compliance, and evolving foodservice demands. For enterprises navigating the 2026 landscape, comprehensive market intelligence is not merely advantageous—it is a critical prerequisite for capital allocation, product portfolio optimization, and competitive positioning. PW Consulting's latest Ice Cubers Market research delivers precisely this depth, translating macroeconomic trajectories and granular industry dynamics into actionable strategic frameworks. This article outlines the fundamental market architecture, competitive forces, and operational contingencies that will define decision-making throughout the forecast horizon.
Ice Cubers Market
Such intelligence becomes indispensable when historical momentum meets structural transformation. The global market for commercial ice cubers has demonstrated consistent expansion, with revenue scaling from approximately $2.55 billion in 2020 to a projected $3.85 billion in 2025. Forward-looking estimates place the 2026 valuation near $4.13 billion, with sustained growth anticipated through the end of the decade. The compound annual growth rate of 6.5 percent across the 2026 to 2032 forecast period signals a maturing yet still expanding ecosystem where demand is increasingly fragmented across product architectures, geographies, and application verticals. Understanding how capital flows through this ecosystem—and where margins are being captured or compressed—requires more than headline figures. It demands a diagnostic lens that connects equipment specifications, supply chain volatility, standardization mandates, and end-user procurement behaviors.
Ice Cubers Market
Market Architecture and Growth Mechanics
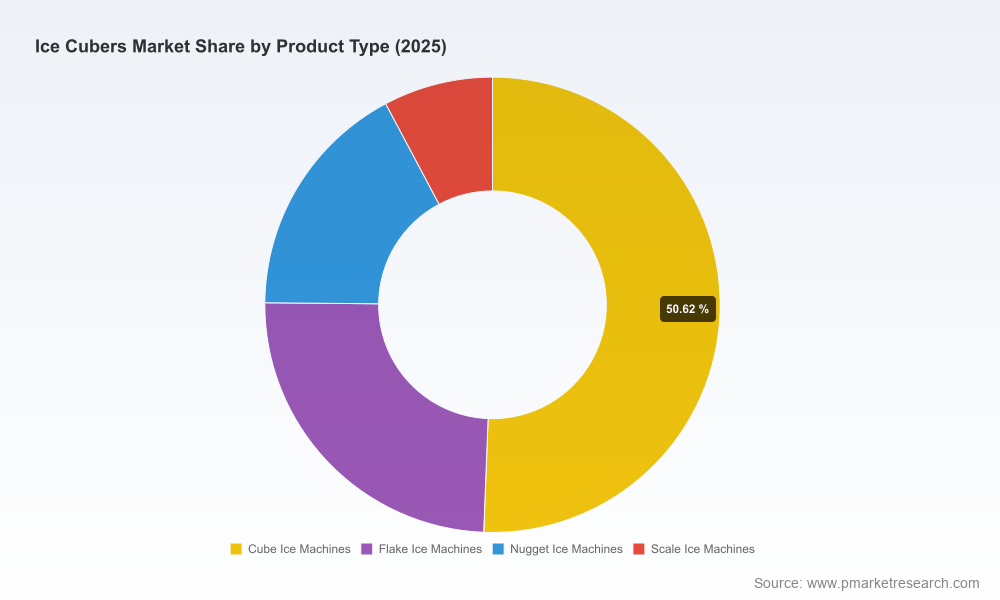
The commercial ice cuber segment operates within a multi-layered demand environment. Healthcare facilities, foodservice operators, retail outlets, and industrial users each impose distinct performance requirements on equipment ranging from production capacity and ice clarity to storage integration and sanitation protocols. The product category itself has diversified considerably. Traditional cube ice machines continue to anchor the segment, while flake, nugget, and scale ice configurations serve specialized operational niches where melt rates, surface area, or dispensing mechanics dictate equipment selection. This diversification means that strategic buyers cannot rely on a single equipment archetype to satisfy cross-vertical requirements; rather, they must evaluate how specific machine families align with volume expectations, utility constraints, and hygiene specifications.
Ice Cubers Market
Distribution of demand across regions and applications introduces additional strategic complexity. North American operators, European suppliers, and Asia Pacific manufacturers each navigate distinct procurement cycles, labor cost structures, and compliance environments. Likewise, foodservice applications account for a dominant share of commercial ice consumption, yet healthcare, retail, and industrial deployments generate meaningful and growing demand streams with their own specification thresholds. Decision-makers evaluating market entry, capacity expansion, or vendor partnerships must therefore analyze where volume concentrates, how pricing power is distributed, and which application segments exhibit the highest replacement or upgrade frequency.
Beyond volume distribution, equipment economics are increasingly shaped by input-cost trajectories and efficiency mandates. Stainless steel remains the construction material of choice for ice cuber manufacturing, driven by corrosion resistance and sanitation requirements. Early 2026 pricing observations across Asian and European markets showed declines of up to 16 percent for relevant grades, offering potential margin relief for manufacturers and procurement teams that can lock in favorable supply contracts. At the same time, energy efficiency expectations and refrigerant compliance—particularly the transition toward R290 systems—continue to influence engineering roadmaps. Equipment that balances lower operational expenditure with regulatory conformity is gaining preferential positioning in hospitality and foodservice procurement cycles, making efficiency metrics a central element of value assessment rather than a secondary technical feature.
Competitive Landscape: Scale, Differentiation, and Motion
The commercial ice cuber market features a competitive field characterized by moderate concentration and active differentiation. Industry concentration metrics indicate that the top three participants command roughly 31.5 percent of market revenue, while the top five reach approximately 40.2 percent. This structure suggests a landscape where incumbent scale confers advantages in distribution, service networks, and brand recognition, yet meaningful room remains for specialized manufacturers to compete on product performance, regional reach, or application-specific engineering.
Several established manufacturers anchor this ecosystem. Hoshizaki Corporation operates as a leading global producer of commercial ice machines, maintaining production capabilities in Japan and the United States to serve a broad foodservice and commercial customer base. Manitowoc Ice, part of Pentair, represents a major American source of commercial ice machines and cube ice systems, offering a wide portfolio tailored to foodservice environments. Scotsman Ice Systems has built recognition around gourmet clear cube machines and restaurant-quality commercial cubers, including its Brilliance series. Ice-O-Matic, operating under the Ali Group umbrella, specializes in commercial cube ice makers capable of producing full, half, and gourmet formats. Follett Ice focuses on integrated ice machines, storage, and dispensing systems, with cube ice solutions addressing both healthcare and foodservice needs.
Regional and niche specialists add further variety to the competitive map. Brema Ice Makers, an Italian manufacturer active since 1985, supplies cube, finger, and fast ice models. Cornelius, Inc. provides ice machines and dispensers as part of broader beverage systems, incorporating cube ice production capabilities. North Star Ice Equipment targets high-capacity industrial applications, including cube and flake systems designed for seafood processing and heavy-duty operational cycles. KOLD-DRAFT has earned a distinct position through pure square cube ice machines that leverage horizontal evaporator technology to produce clear, dense ice. These profiles illustrate that competitive advantage in this market is rarely monolithic; it is built from combinations of production geography, product range, service reach, and application focus.
Competitive motion is equally important. Trade show activity during early 2026 underscored ongoing engagement with end-users and channel partners. ICESTA showcased ice making solutions, including relevant cube systems, at Canton Fair 2026 Phase 1. Naixer displayed commercial cube ice machines at the NRA Show 2026 in Chicago. Icematic presented ice cube machines at SIGEP World in early 2025. These exhibitions are more than promotional events; they function as signal mechanisms for product direction, regional prioritization, and channel strategy. Procurement teams and investors alike should treat such activity as leading indicators of where manufacturers expect demand to intensify and which configurations they believe will resonate with buyers.
Operational Dynamics and Strategic Implications
Several interrelated dynamics will shape purchasing behavior and equipment economics throughout the forecast period. Regulatory compliance remains a foundational requirement. Commercial ice machines must adhere to NSF/ANSI standards for food equipment safety and sanitation. This requirement drives engineering choices around material grade, surface finish, drainage design, and cleanability, reinforcing the continued use of high-grade stainless steel and influencing total cost of ownership calculations. Manufacturers that can demonstrate conformance while maintaining production efficiency are better positioned to secure specification decisions in regulated environments.
Energy performance and refrigerant strategy now intersect directly with procurement economics. As energy efficiency mandates tighten and R290 refrigerant compliance becomes embedded in new model designs, operational cost trajectories are shifting. In hospitality and foodservice settings, where equipment may run persistently across service hours, efficiency differentials can translate into substantial cost variances over a machine's service life. Buyers evaluating tenders or replacement cycles should therefore weigh direct purchase price against anticipated utility consumption, maintenance intensity, and refrigerant-related service considerations.
Supply chain input trends add another layer of strategic relevance. Stainless steel pricing movements in early 2026 suggested potential near-term relief for equipment manufacturers and procurement departments capable of timing purchases advantageously. However, the broader steel environment remains subject to volatility linked to nickel and chromium markets, with benchmark indicators such as steel rebar trading reflecting modest monthly changes and underlying alloy sensitivity. These dynamics highlight the importance of scenario planning: budgeting for equipment programs, service contracts, and inventory strategies should account for the possibility that input costs may shift between specification, approval, and delivery phases.
Application-specific requirements further complicate procurement logic. Healthcare environments prioritize hygiene, storage integration, and reliable dispensing; foodservice operators emphasize production speed, ice clarity, and footprint efficiency; retail deployments often require robust visibility and ease of access; industrial users look for high-capacity output and durability under continuous operation. Because these requirements diverge, a single equipment specification cannot optimally serve every use case. Strategic buyers need to align product type, storage configuration, and service support with the operational profile of each site rather than relying on standardized one-size-fits-all assumptions.
What the PW Consulting Study Delivers
PW Consulting's Ice Cubers Market research is structured to support precise, evidence-based decision-making across multiple stakeholder groups. The study combines top-down market sizing with bottom-up segmentation logic, enabling readers to understand both aggregate growth patterns and the micro-dynamics that drive demand in specific product, application, and regional contexts. Rather than presenting static figures in isolation, the analysis maps how growth is distributed, where procurement intensity is highest, and how competitive positioning varies across equipment categories.
The report's operational content is designed for practical use. It examines product-type distinctions, including cube, flake, nugget, and scale ice configurations, and relates these distinctions to performance criteria, end-user preferences, and replacement cycles. It evaluates application-level demand drivers across foodservice, healthcare, retail, and industrial environments, helping decision-makers identify where specification requirements are most stringent and where upgrade activity is likely to accelerate. Regional coverage provides context for distribution strategies, sourcing decisions, and market-entry assessments without reducing complex geographies to oversimplified rankings.
Competitive analysis within the study goes beyond company descriptions. It assesses how incumbent manufacturers leverage production footprints, service networks, and product breadth to sustain market presence, while also examining how specialized producers differentiate through engineering characteristics, regional focus, or application expertise. Recent trade show participation and product exhibition activity are interpreted as indicators of strategic emphasis, helping readers infer where manufacturers expect growth and how they are positioning for upcoming procurement cycles.
Equally important, the study integrates industry context that affects equipment economics and procurement timing. Material supply considerations, regulatory expectations, and efficiency-oriented design trends are discussed in relation to their impact on pricing, specification, and total cost of ownership. This integrated approach allows executives to evaluate market opportunities with a clearer understanding of both revenue potential and operational risk. The analysis is built to inform capital planning, vendor selection, product development prioritization, and regional expansion strategy by connecting market structure to decision-relevant variables.
Strategic Takeaways for 2026 Decision-Making
For organizations operating in or entering the commercial ice cuber space, the 2026 environment rewards disciplined analysis and scenario-aware planning. Several priority considerations emerge from the market structure and competitive context.
- Evaluate equipment portfolios against application fit rather than headline capacity alone. Cube, flake, nugget, and scale configurations serve different operational needs, and procurement decisions should reflect site-specific volume, storage, sanitation, and presentation requirements.
- Incorporate efficiency and compliance into total cost models. Energy performance, R290 refrigerant alignment, and NSF/ANSI conformance influence both acquisition decisions and long-term operating economics, particularly in hospitality and foodservice deployments.
- Monitor input-cost trajectories and procurement timing. Fluctuations in stainless steel pricing and alloy-related volatility can affect equipment budgeting and contract negotiation windows, making timing and supplier engagement strategically relevant.
- Interpret competitive activity as a strategic signal. Trade show presence, product showcases, and regional exhibition patterns provide insight into where manufacturers anticipate demand growth and which configurations they believe will gain traction.
- Assess concentration and fragmentation together. Moderate market concentration indicates that scale players retain advantages in distribution and service, yet sufficient fragmentation remains for differentiated offerings to compete on performance, specialization, and regional responsiveness.
The broader implication is that market participation in 2026 requires more than awareness of growth trends. It demands a structured reading of how segmentation, regulation, efficiency mandates, and competitive motion interact to shape procurement behavior and margin distribution. Enterprises that align their strategies with these underlying mechanics are better positioned to capture opportunity while managing the operational and cost risks embedded in equipment specification and deployment.
Access the Full Intelligence
This overview reflects the strategic architecture behind PW Consulting's Ice Cubers Market study, but the full report contains the detailed segmentation logic, competitive profiles, regional context, and procurement insights necessary for execution-level planning. The complete analysis provides the granular market structure, company-level assessments, and operational scenarios that support capital allocation, sourcing strategy, and product roadmap decisions throughout the 2026 to 2032 forecast period.
For executives, procurement leaders, and investors seeking comprehensive market intelligence, the full study offers the depth required to move from high-level awareness to actionable strategy. Access the complete report to obtain the detailed market segmentation, competitive benchmarking, and decision-support frameworks that define the current commercial ice cuber landscape.
For detailed analysis of this topic, please visit the official page:Ice Cubers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek