
Unlocking Strategic Advantage: Navigating the Big Data Analytics in Defense and Aerospace Market Through 2032
The defense and aerospace sectors are undergoing a profound digital transformation, driven by the imperative to process, analyze, and act upon vast streams of mission-critical data. As platforms become more connected and threats more asymmetric, big data analytics has evolved from a supportive function to a core operational capability. Our latest market research, Worldwide Big Data Analytics In Defense and Aerospace Market, provides a comprehensive lens into this rapidly expanding landscape, offering the intelligence necessary to navigate uncertainty and capitalize on emerging opportunities through 2032.
Worldwide Big Data Analytics In Defense and Aerospace Market
For executives, strategists, and investors operating in this high-stakes environment, understanding the trajectory of data analytics adoption is not merely an academic exercise; it is a prerequisite for informed capital allocation, partnership formation, and competitive positioning. This introduction outlines the strategic value embedded within our analysis, highlighting the market's evolution, the shifting competitive dynamics, and the regulatory forces that will shape the industry over the next decade.
Worldwide Big Data Analytics In Defense and Aerospace Market
Market Trajectory: Sustained Growth Fueled by Digital Transformation
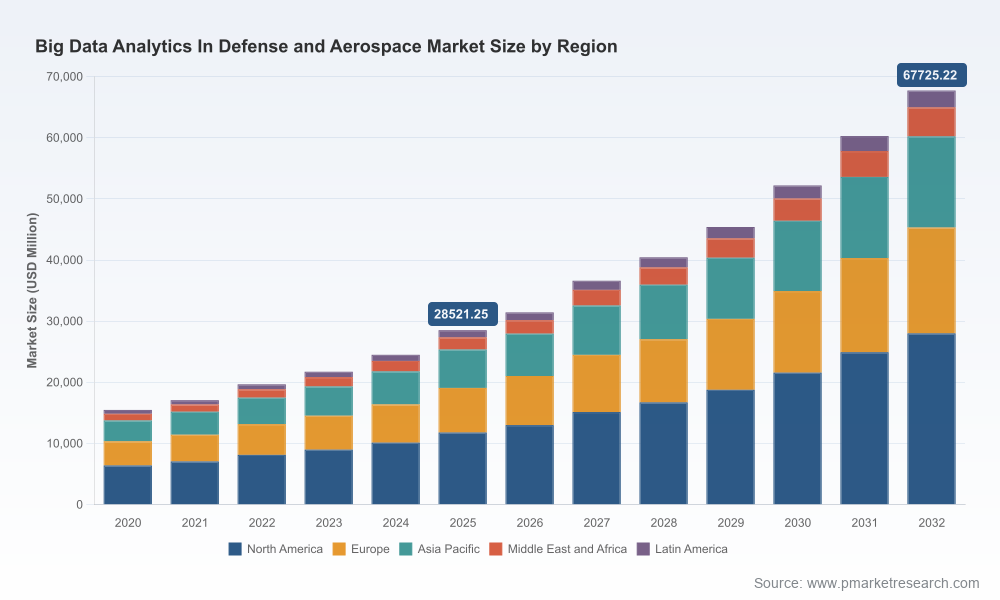
The financial scale and growth momentum of the big data analytics market in defense and aerospace underscore its strategic importance. Drawing on historical performance from 2020 through 2025 and projecting forward to 2032, our analysis captures a market in sustained expansion. In 2025, the market generated substantial revenue, reflecting years of steady investment in sensor networks, cloud infrastructure, and data fusion capabilities. From this base, the market is projected to grow at a compound annual growth rate of 13.15% over the forecast period, reaching a significantly larger operational scale by 2032.
Worldwide Big Data Analytics In Defense and Aerospace Market
This growth arc is not linear or accidental; it is the cumulative result of long-term institutional commitments to modernizing data architectures across defense and aerospace programs. Organizations that have already embedded analytics into their operational workflows are seeing compounding returns, while those still in the early stages of digital maturity are accelerating their adoption in response to peer benchmarks and operational demands. The trajectory observed from 2020 to 2025 demonstrates how quickly analytics capabilities can move from pilot projects to enterprise-wide deployments when supported by clear strategic mandates and infrastructure investment.
Beyond the top-line numbers, our report dissects the structural composition of the market to reveal where value is being created and how it is distributed across different dimensions. By examining the market through multiple lenses—component categories, application domains, and geographic footprints—stakeholders can identify the segments that align most closely with their capabilities and growth objectives. The report provides detailed breakdowns of how software and services interact to form end-to-end analytics solutions, as well as how distinct application areas such as predictive maintenance, intelligence and surveillance, cyber security, and supply chain logistics are driving demand across different operational contexts.
Geographic analysis within the report offers a nuanced view of regional market dynamics, highlighting areas of concentrated investment and emerging demand centers. Rather than presenting static snapshots, the geographic section traces how defense modernization priorities, procurement cycles, and technology transfer considerations influence regional market structures. This multi-dimensional segmentation framework enables stakeholders to evaluate growth opportunities with precision, avoiding the pitfalls of oversimplified market sizing that fail to capture the operational realities of defense and aerospace procurement.
Inside the Report: Actionable Intelligence for Decision-Makers
Our research is designed to serve as a practical decision-support tool rather than a theoretical overview. The report delivers a structured, evidence-based examination of the market that bridges high-level trends with on-the-ground realities. Key components of the analysis include a thorough review of market sizing and forecasting methodologies, a detailed segmentation assessment across components, applications, and regions, and an in-depth competitive profiling of the organizations shaping the industry.
The competitive landscape section provides a granular look at the strategies, capabilities, and recent initiatives of leading market participants. By mapping the activities of major defense contractors, technology platform providers, cloud and enterprise analytics vendors, and specialized consulting and integration firms, the report reveals how different players are positioning themselves across the value chain. This section also identifies patterns of collaboration, including partnerships that combine domain expertise with advanced analytics platforms, as well as the growing role of government-led initiatives in setting technical standards and procurement priorities.
A significant portion of the report is dedicated to market dynamics, where we examine the forces that are accelerating or constraining adoption. This includes an assessment of infrastructure dependencies, such as the reliance on high-performance computing, cloud platforms, and edge computing to support real-time sensor fusion and large-scale data processing. We also analyze the impact of regulatory frameworks on market behavior, including cybersecurity certification requirements, export control regimes, and emerging standards for AI trustworthiness in aerospace systems.
Furthermore, the report integrates recent developments that signal shifts in market direction. These include strategic action plans issued by defense organizations that prioritize enterprise-wide data governance and rapid technology adoption, as well as contract awards and partnerships that illustrate how government and industry are collaborating to deploy advanced analytics capabilities. By connecting these developments to broader market trends, the report helps readers interpret short-term events within the context of long-term structural change.
Competitive Landscape: Strategies and Moves Among Leading Players
The competitive environment in defense and aerospace big data analytics is characterized by a blend of established defense primes, technology platform leaders, and specialized integrators. Several core companies define the contours of this landscape, each bringing distinct strengths to the market. Palantir Technologies has built a prominent position through its Gotham and Foundry platforms, which enable the integration and analysis of complex multi-source datasets for real-time intelligence, predictive maintenance, and decision support. Their work spans classified programs and production optimization, reflecting the breadth of analytics applications across defense and aerospace operations.
Boeing Defense, Space & Security integrates big data analytics across its defense programs to streamline production, generate predictive insights, and enhance mission support. The company has increasingly partnered with analytics providers to standardize data across factories and classified aerospace systems, illustrating a broader industry trend toward interoperability and data consistency. Lockheed Martin deploys analytics within its platforms and systems to support intelligence fusion, predictive maintenance, and operational decision-making, embedding data capabilities directly into mission-critical environments.
Northrop Grumman utilizes analytics for sensor data processing, mission planning, and advanced systems integration, emphasizing the role of data in complex defense and aerospace applications. RTX Corporation applies analytics across radar, sensor, and command systems to enable real-time threat analysis and aerospace operations. BAE Systems offers data analytics capabilities tailored to intelligence, cyber, and electronic systems, reinforcing the convergence of analytics with broader defense technology portfolios. General Dynamics employs analytics across IT, combat, and aerospace systems for mission support, while L3Harris Technologies integrates analytics into communication, ISR, and space systems. Honeywell applies analytics in aerospace systems with a strong focus on predictive maintenance and operational optimization, and Thales Group supplies analytics solutions for avionics, defense electronics, and aerospace systems.
On the technology and services side, IBM supplies enterprise big data analytics platforms and AI tools designed for predictive maintenance, logistics, and intelligence applications. Microsoft provides Azure-based analytics, cloud computing, and AI services that support defense data integration and mission systems. Oracle delivers database and cloud analytics solutions for managing large-scale defense and aerospace data workloads. C3 AI offers enterprise AI and analytics applications for predictive maintenance, supply chain, and intelligence analysis in federal and defense contexts. Booz Allen Hamilton provides mission-focused analytics, AI integration, and consulting services for DoD and intelligence community programs, combining technical capability with deep domain expertise.
Recent developments highlight how these players are navigating the market. In September 2025, Boeing Defense, Space & Security announced a partnership with Palantir Technologies to integrate AI-driven data analytics using the Foundry platform across defense factories and classified programs, aiming to standardize insights, accelerate production, and support global military customers. Earlier in the year, the US Space Force published its Data and AI FY2025 Strategic Action Plan, which emphasizes enterprise-wide data governance, a data-driven culture, and rapid adoption of analytics and AI technologies. In July 2025, the DoD Chief Digital and Artificial Intelligence Office awarded contracts to frontier AI companies for the development of agentic AI workflows supporting big data analytics for national security and warfighting missions. These events reflect a market in which traditional defense contractors, technology providers, and government agencies are actively reshaping how analytics capabilities are developed, deployed, and integrated.
Market Dynamics: Regulation, Infrastructure, and Trustworthiness
The expansion of big data analytics in defense and aerospace is deeply intertwined with a complex set of technical, regulatory, and operational dynamics. Infrastructure remains a foundational consideration: analytics capabilities rely heavily on high-performance computing, cloud platforms, and edge computing to handle real-time sensor fusion and large-scale multi-source data processing. Organizations that can effectively orchestrate these infrastructure components gain a meaningful advantage in deploying analytics at the scale and speed required by modern defense and aerospace operations.
Regulatory frameworks exert significant influence over how analytics solutions are designed, deployed, and shared. The US Space Force Data and AI FY2025 Strategic Action Plan prioritizes maturing enterprise-wide data and AI governance, advancing a data-driven culture, and deepening partnerships across government, industry, and academia. At the same time, contractors handling big data analytics systems must comply with CMMC and NIST 800-171 standards to protect sensitive information, adding compliance rigor to procurement and development processes. Export controls such as ITAR and EAR govern the transfer of analytics technologies and related technical data, requiring strict licensing for international activities and shaping the geography of collaboration.
Emerging standards for AI trustworthiness are also reshaping the market. Building on established frameworks such as RTCA DO-178C for software, new safety and certification requirements are being developed for AI-enabled big data analytics in aerospace systems. These standards address concerns around reliability, explainability, and operational safety, and they influence how quickly and broadly analytics capabilities can be adopted in regulated environments. For market participants, understanding these dynamics is essential not only for compliance but also for positioning products and services in a way that aligns with evolving certification and procurement expectations.
In addition to formal regulations, market dynamics are influenced by procurement cycles, budget priorities, and the growing emphasis on interoperability across allied and partner networks. The convergence of data from multiple sources, the need for secure data sharing, and the demand for actionable insights under time pressure all contribute to a market environment in which technology choices, partnership structures, and compliance strategies must be carefully coordinated. Our report examines these dynamics in detail, helping readers anticipate how shifts in policy, infrastructure investment, and operational requirements will affect demand and competition.
Why This Research Matters for 2026 and Beyond
As we look toward 2026 and the years that follow, the strategic value of a rigorous, evidence-based market assessment becomes increasingly clear. The big data analytics market in defense and aerospace is not only expanding in size; it is evolving in complexity, with new participants, new use cases, and new regulatory expectations continuously reshaping the playing field. Decision-makers who rely on fragmented or outdated information risk misjudging the pace of adoption, the relative strength of competitors, and the direction of procurement priorities.
Our report is designed to mitigate these risks by providing a coherent, up-to-date view of the market that connects macro-level trends with the specifics of segmentation, competition, and dynamics. It enables stakeholders to benchmark their position against market structure, identify adjacent opportunities where capabilities can be extended, and evaluate the strategic implications of recent government actions and industry partnerships. By integrating historical performance with forward-looking forecasting, the research supports planning across multiple time horizons, from immediate operational decisions to long-term investment strategies.
For organizations seeking to deepen their understanding of where value is being created, how competitors are positioning themselves, and which forces will most influence market evolution, this report offers a structured foundation for analysis and action. The insights it provides are relevant to a broad range of functions, including strategy, business development, procurement, technology planning, and investment evaluation. In a market where the cost of misalignment can be significant, access to comprehensive, reliable intelligence is a decisive advantage.
To explore the full scope of segmentation data, competitive profiles, regulatory analysis, and forecast detail, we invite you to access the complete Worldwide Big Data Analytics In Defense and Aerospace Market report. The complete publication provides the depth and granularity required to translate high-level trends into specific strategic actions, ensuring that your decisions are grounded in a clear and current understanding of the market landscape.
For detailed analysis of this topic, please visit the official page:Worldwide Big Data Analytics In Defense and Aerospace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek