
Beyond Rigid Limits: Strategic Intelligence for the Semi-Flexible RF Coaxial Cable Market in 2026
Introduction: The Transitional Role of Semi-Flexible Interconnects
The RF interconnect landscape is undergoing a structural shift as system architects balance performance, installation complexity, and total cost of ownership. Semi-flexible coaxial cables have emerged as a pragmatic bridge between the absolute precision of rigid assemblies and the mechanical variability of fully flexible alternatives. For engineering leaders, procurement teams, and strategic planners, this category is no longer a niche compromise; it is a deliberate design choice for mission-critical routing in constrained environments. Our latest market research unpacks the commercial and technical forces shaping this transition, with a clear focus on how organizations can translate industry momentum into 2026 decision readiness.
Semi-flexible RF Coaxial Cable Market
Over the past several years, the market has expanded in a measured but consistent manner, reflecting sustained demand across high-frequency infrastructure, defense platforms, and precision instrumentation. The trajectory indicates that semi-flexible solutions are gaining traction precisely where installation flexibility, signal integrity, and environmental durability must coexist. This research is designed to move beyond surface-level summaries and provide a decision-grade view of where value is being created, how supply chains are reacting, and which competitive patterns are likely to persist through the end of the decade.
Semi-flexible RF Coaxial Cable Market
Market Trajectory and the Case for Strategic Foresight
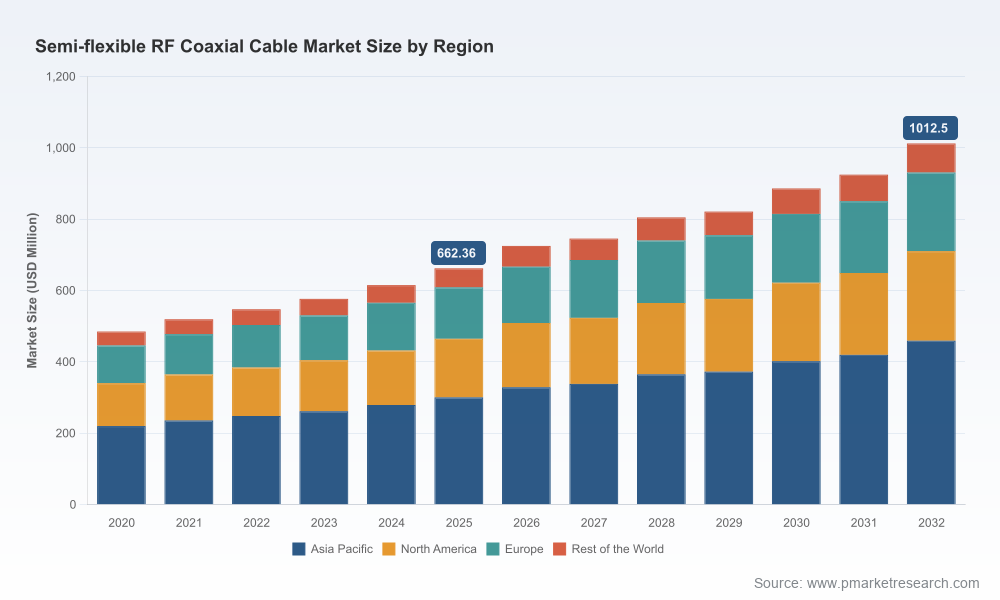
The macro picture is important because it defines the scale of opportunity and the urgency of planning. Recent historical tracking shows a market that has moved from in the high hundreds of millions in 2020 toward a substantially larger base by 2025, and the forward path continues to reflect steady expansion. The forecast interval through 2032 is anchored by a compound annual growth rate of 6.25 percent, pointing to a market that is not merely recurring but compounding as new deployments and replacement cycles reinforce each other.
Semi-flexible RF Coaxial Cable Market
What makes this trajectory strategically meaningful is not the headline figure alone, but the consistency of the climb across multiple application and material environments. The growth pattern suggests that semi-flexible coaxial cables are becoming embedded in longer-term capital planning rather than treated as short-cycle consumables. That has implications for capacity commitments, supplier qualification timelines, inventory strategy, and the way organizations model risk in high-frequency RF programs. Decision-makers who treat the category as a stable, growing input stream can position themselves ahead of price volatility, qualification delays, and regional supply disruptions.
The revenue roadmap depicted in our study spans from the current base year through the early 2030s, with each forecast step reflecting the interplay of new infrastructure rollouts, sustained aerospace and defense programs, and expanding test and measurement requirements. Because growth is distributed across multiple end-use environments and material types, the market reward does not concentrate in a single corridor. Instead, it rewards firms that can align product capabilities with the specific constraints of each vertical while managing the cost structure of conductors, dielectrics, and assembly labor.
What the Study Delivers: Operational Intelligence, Not Generic Overviews
This report is built for practitioners who need to make investment, sourcing, and product roadmap decisions with confidence. The research framework covers the full commercial anatomy of the semi-flexible RF coaxial cable market, with detailed attention to how material selections, connector compatibility, and form-factor conventions influence purchasing behavior and engineering adoption. Rather than stopping at market sizing, the study translates quantitative structure into operational implications.
The sections are organized to support both strategic framing and execution-level analysis. Readers will find a breakdown of how market value is distributed across major geographic territories and across the leading product types, followed by an application-level view that highlights where deployment pressure is strongest. The study also examines market concentration, competitive positioning, and the operational consequences of material cost dynamics and specification-driven demand. Where relevant, the analysis ties technical characteristics to commercial outcomes, helping teams understand not just what is happening, but why it matters for cost, lead time, and qualification risk.
In addition to structural analysis, the report includes forward-looking assessments that connect near-term industry activity to multi-year planning. The forecasting approach is anchored in historical behavior while accounting for the kinds of disruptions that can alter regional pricing, material availability, and competitive intensity. The result is a research asset that can be used to benchmark internal assumptions, challenge overly optimistic or conservative forecasts, and prioritize which segments deserve the closest monitoring in 2026 and beyond.
Competitive Landscape: Established Players, Regional Specialists, and the New Flexibility Premium
The competitive set in semi-flexible RF coaxial cables is shaped by a mix of established interconnect specialists, broad-line RF manufacturers, and regionally concentrated suppliers. What distinguishes the leaders is not simply brand visibility, but the ability to align product architecture with application pressure points such as low passive intermodulation performance, hand-formability, high-frequency consistency, and compatibility with standard connector families.
Times Microwave Systems continues to emphasize semi-flexible options as practical drop-in alternatives for applications where traditional semi-rigid cables introduce installation or routing constraints. Their TFlex-focused messaging highlights low-loss and low-PIM characteristics for aerospace, defense, telecom, and harsh-environment use, with compatibility for standard solder-on semi-rigid connectors. That positioning matters because it directly addresses a recurring engineering trade-off: preserving RF performance while reducing the mechanical fragility and installation complexity associated with fully rigid assemblies.
Rosenberger offers a broader cable assembly portfolio that includes semi-flexible cables alongside flexible, semi-rigid, and corrugated types, supporting signal transmission up to 110 GHz across telecom, industrial, aerospace, and test applications. This breadth gives the company a multi-application vantage point, allowing it to serve customers who need one supplier relationship across varying mechanical and frequency requirements. In a market where interoperability and qualification efficiency often influence purchasing decisions, that breadth is strategically relevant.
HUBER+SUHNER contributes with hand-formable semi-flexible options such as the Habia Flexiform series, targeting high-performance microwave and RF interconnects in defense, telecom, and industrial contexts. Hand-formable designs are especially important where field routing must be precise but the installation environment cannot accommodate the tooling or bending limitations of more rigid solutions. The company's emphasis on high-performance interconnect reliability aligns with the needs of programs where rework is costly and signal degradation is unacceptable.
Amphenol RF manufactures cable assemblies using semi-flexible, conformable, and hand-formable coaxial cables, including common form factors used in high-frequency military, broadband, instrumentation, and automotive applications. Their footprint in multiple industries gives them exposure to both volume-oriented and specification-intensive demand, which helps stabilize revenue patterns across different procurement cycles. For buyers, this means access to a supplier whose catalog can span both high-specification and broader commercial use cases.
TE Connectivity contributes precision high-frequency interconnects through products such as EPC-086 and other semi-flex and semi-rigid/conformable coaxial cables. The company's scale and engineering breadth make it relevant for programs that require repeatable performance, standardized interfaces, and documented qualification paths. In markets where system integration depends on predictable behavior across connector and cable transitions, that kind of documentation and consistency becomes commercially valuable.
Regional manufacturing also plays an important role in shaping price, availability, and lead-time dynamics. Jiangsu Elesun Cable specializes in high-temperature PTFE insulation semi-flexible coaxial cables, including series that correspond to common RF cable conventions, along with low-PIM variants. Hangzhou Hongsen Cable focuses on 0.141 inch semi-flexible coaxial cables and related RF products for general signal transmission. EZ Form Cable Corporation offers hand-formable semi-flexible options such as the EZ-FLEX series as alternatives to semi-rigid types for RF and microwave assemblies.
This mix of global specialists and regional manufacturers creates a competitive environment in which technical differentiation, specification support, and cost control all compete for influence. Buyers increasingly evaluate not only electrical performance, but also whether a supplier can support installation flexibility, maintain consistency across batches, and respond to material cost or regulatory pressures without disrupting program timelines.
Industry Dynamics: Material Cost Pressure, Specification Barriers, and Installation-Driven Demand
Several dynamics are shaping how the market behaves in 2026 and how firms should interpret near-term risks and opportunities. One of the most immediate is raw material cost behavior. Copper, a primary conductor material in semi-flexible RF coaxial cables, has traded at elevated levels driven by infrastructure and data center demand. At the same time, PTFE and fluoropolymer dielectrics and jackets remain central to high-temperature semi-flexible designs, with supply chain costs influenced by upstream chemical and energy factors. These input pressures do not simply influence unit pricing; they affect margin management, quoting confidence, and the timing of supplier negotiations.
Regulatory and standards-driven requirements add another layer of structure to the market. Semi-flexible RF coaxial cables commonly comply with military and defense specifications such as MIL-C-17 and MIL-DTL for applications requiring proven performance in harsh environments. Compliance is not just a technical checkbox; it influences qualification lead times, documented traceability, and the commercial credibility of suppliers serving defense and aerospace programs. In practice, this means that the market does not reward all cost competitiveness equally. Suppliers that can maintain specification integrity while controlling cost have a structural advantage.
Demand side drivers are equally important. The need for easier installation and routing in 5G infrastructure, aerospace, defense, and high-frequency test systems continues to support adoption of semi-flexible and hand-formable alternatives versus more rigid options. The commercial appeal lies in reducing installation friction without sacrificing RF integrity, especially where enclosures, rack layouts, or field conditions make rigid cable handling difficult. That practical advantage helps explain why the category is growing in environments where both performance and deployability matter.
Geopolitical and trade-related factors are also entering planning assumptions. Tariff changes affecting raw materials and semi-finished products have influenced supply chain costs for PTFE-insulated semi-flex coaxial cables in the U.S. market. For procurement and supply chain leaders, this creates a reason to examine not only supplier price lists but also country-of-origin exposure, tariff sensitivity, and the resilience of alternate sourcing paths. The firms that treat tariff and trade risk as part of their design-to-cost process are better positioned to avoid margin surprises.
Recent Developments: Signals of Momentum and Product Re-Positioning
Recent industry activity reinforces the idea that semi-flexible RF coaxial cables are being actively repositioned rather than passively maintained. In late 2025, Times Microwave Systems promoted TFlex coaxial cables as a flexible, low-loss, low-PIM alternative to semi-rigid coax for mission-critical aerospace and defense platforms, emphasizing easier installation without complex bending. This is a strong indication that the value proposition is shifting from "acceptable compromise" to "purposeful choice," especially where platform integration teams want to reduce installation complexity while maintaining stringent RF requirements.
Around the same period, Insulated Wire introduced Re-Flex hand-formable coax cable assemblies as a solution for applications requiring semi-rigid performance with greater flexibility. That launch language highlights a common industry theme: customers want the electrical predictability associated with rigid designs, but with installation freedom that rigid cables cannot provide. The emergence of such offerings suggests continued product innovation aimed at closing the gap between performance and handling convenience.
Earlier in 2025, S-Conn Enterprise Co., Ltd. previewed participation in 2026 exhibitions to highlight semi-flexible cable capabilities alongside RF connectors and assemblies. Exhibition positioning matters because it signals how suppliers intend to communicate with buyers in the near term: not merely as component vendors, but as solution partners for interconnect integration. For market watchers, these activities indicate that semi-flexible cables are increasingly presented as part of a broader system-level value proposition.
Taken together, these developments point to a category that is being actively refined in response to practical deployment constraints. The interest is not limited to price competition; it extends to ease of installation, compatibility with standard connector infrastructure, signal integrity assurance, and reduced rework risk. These are precisely the variables that influence specification decisions in expensive or hard-to-access RF environments.
Why This Research Matters for 2026 Decision-Making
For organizations planning in 2026, the strategic question is not whether semi-flexible RF coaxial cables are relevant, but how to position around their growth with discipline. The market's steady expansion, material cost sensitivity, and specification-driven purchasing patterns create a landscape where assumptions need to be tested against evidence. This research is intended to support that process by providing a structured view of market size, growth trajectory, competitive behavior, and the operational forces that shape outcomes.
The study helps decision-makers evaluate where demand is likely to concentrate, how material and supply chain pressures may influence cost planning, and which competitive strengths are most likely to persist. It also supports more informed conversations about supplier selection, qualification strategy, and regional sourcing risk. For product teams, it provides context for roadmap prioritization by showing where installation flexibility and performance reliability are being valued most highly. For commercial and procurement teams, it offers a framework for understanding why certain offerings command premium positioning and how market concentration influences negotiation leverage.
Importantly, the report is designed to remain practically useful rather than purely descriptive. It connects market structure to the kinds of choices organizations face when balancing performance, cost, and supply continuity. Because the market spans multiple regions, materials, and applications, the research gives readers a way to compare assumptions across segments without losing sight of the overall growth narrative.
Conclusion: A Market to Watch with Discipline, Not Generalizations
The semi-flexible RF coaxial cable market is best understood as a category where engineering practicality and commercial momentum reinforce one another. Demand is being shaped by the need for installation flexibility in high-frequency, high-stakes environments; supply is being shaped by material cost dynamics, standards compliance, and a competitive field that mixes global specialists with regional manufacturers. The result is a market with clear growth visibility and meaningful strategic complexity.
Our full market research report provides the detailed quantitative framework, segment-level structure, and competitive analysis needed to move from broad awareness to decision-ready insight. The macro trajectory, application distribution, material type splits, and concentration patterns are all examined in greater depth within the study, along with the operational implications that matter for sourcing, planning, and product strategy. For teams preparing for 2026 commitments and multi-year RF programs, the complete report offers the level of detail required to act with confidence.
For detailed analysis of this topic, please visit the official page:Semi-flexible RF Coaxial Cable Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek