
The Wax 3D Printer Market: Strategic Intelligence for 2026 Decision Makers
The wax three-dimensional printing sector stands at a critical inflection point. Over the past half-decade, cumulative market revenue has climbed from under one hundred million dollars in 2020 to approximately one hundred ninety-eight million dollars in 2025, reflecting sustained adoption across precision casting workflows. This trajectory is not merely a continuation of additive manufacturing growth but a structural shift driven by workflow consolidation, material science breakthroughs, and an increasingly competitive vendor landscape. For enterprise leaders, supply chain strategists, and technology buyers, navigating this environment requires more than headline figures. Comprehensive market intelligence becomes the difference between reactive capital allocation and disciplined, forward-looking investment. Our latest Wax 3D Printer Market research delivers precisely that intelligence, equipping organizations with actionable frameworks to evaluate technology roadmaps, benchmark competitive positioning, and anticipate demand shifts through the end of the decade.
Wax 3D Printer Market
The Strategic Imperative of 2026 Market Intelligence
Why does a dedicated market study matter now? The wax printing ecosystem has matured rapidly, transitioning from niche prototyping tools to integrated production assets within jewelry casting houses, dental laboratories, and industrial foundries. Buyers face an expanding array of hardware architectures, material formulations, and regional pricing dynamics. Competing vendors are releasing systems with differentiated post-processing requirements, cybersecurity capabilities, and throughput claims that directly impact total cost of ownership. Without structured intelligence, procurement and strategy teams risk misaligned capital deployment, vendor lock-in, or delayed adoption of technologies that reshape unit economics. The 2026 edition of our market research is designed to cut through fragmented supplier messaging and provide a unified analytical lens. By grounding observations in verified revenue histories, forward-looking projections, and granular vendor tracking, the study transforms raw market signals into decision-ready intelligence. Readers gain clarity on which technological pathways show durable commercial momentum, how regional adoption cycles differ, and where consolidation pressure is most likely to reshape buyer leverage.
Wax 3D Printer Market
Decoding the Revenue Trajectory: A Macro View of Growth Dynamics
The historical and projected revenue curve tells a story of accelerating adoption punctuated by expanding use-case diversity. From 2020 through 2025, cumulative market revenue progressed from ninety-eight million dollars to one hundred ninety-eight million dollars, a growth pattern that underscores both early-phase market expansion and increasing purchasing confidence among mid-tier and enterprise casting operations. Looking ahead, the forecast period extends through 2032, with projected revenue climbing toward four hundred fifty-one million dollars. This forward trajectory is anchored by a compound annual growth rate of twelve point four five percent, a figure that captures the combined effect of incremental capacity additions, rising material throughput, and broadening application penetration. Rather than treating these numbers as static targets, strategic readers should interpret them as indicators of where pricing pressure, volume scaling, and technology refresh cycles intersect. The growth rate reflects more than unit shipment volume; it signals the economic weight of workflow integration, material substitution, and the gradual migration of traditional cast-wax production lines toward digital pattern generation. Organizations that internalize the pace and composition of this expansion can better time capital expenditures, align service-level agreements, and structure vendor negotiations to match realistic demand curves rather than speculative peaks.
Wax 3D Printer Market
Mapping the Competitive Arena: Key Players and Strategic Positioning
The vendor landscape is defined by a mix of established pioneers, diversified additive manufacturing majors, and rapidly scaling regional manufacturers. Each category brings distinct value propositions, pricing philosophies, and go-to-market tactics that influence buyer choices and competitive intensity.
Established Pioneers and Specialized Innovators
Solidscape, headquartered in Merrimack, New Hampshire, has operated as a pioneer in wax additive manufacturing since 1994. Its portfolio centers on one hundred percent wax drop-on-demand printers, including the Muse and S3Duo platforms, alongside dedicated castable materials engineered specifically for high-precision jewelry investment casting patterns. The company's long operating history positions it as a reference point for durability, repeatability, and application-specific material performance. In the broader ecosystem, DWS Systems from Vicenza, Italy, contributes digital wax stereolithography systems complemented by Fusia castable materials optimized for lost-wax investment casting, reinforcing Italy's continued relevance in precision jewelry manufacturing workflows.
Platform Scaling and Workflow Integration
3D Systems, based in Rock Hill, South Carolina, continues to expand its multi-jet printing wax portfolio with systems such as the MJP 300W Plus, which targets jewelry manufacturing through high-resolution pattern generation, dissolvable support structures, and VisiJet one hundred percent wax materials. Strategic moves from this segment increasingly emphasize surface enhancement, reduced post-processing burden, and enterprise-grade security alignment. Flashforge, operating from Jinhua, Zhejiang, China, has built a substantial presence through its WaxJet series, which spans multi-jet wax systems marketed for both industrial and desktop jewelry casting applications. The lineup features dual-wax technology designed to print model wax and support wax simultaneously, a configuration that shortens handling steps and improves pattern fidelity for complex geometries. Recent commercial momentum has placed the WaxJet series among the highest-volume platforms in recent global sales assessments, while newer triple-printhead configurations target higher throughput for scaling production environments.
Regional Expansion and Cost-Performance Positioning
Chinese manufacturers have increasingly shaped price-performance expectations across the market. 3DPTEK offers laser-based wax platforms through its LaserCore series, aimed at cost-effective industrial jewelry and investment casting production. SuperbMelt provides jewelry-oriented wax systems utilizing castable resin formulations designed for direct lost-wax casting with a focus on precision manufacturing outcomes. Eplus3D produces wax and sand selective laser sintering equipment, including the EP-C5050 platform, which targets faster production cycles across both engine-related casting components and jewelry patterns. iFun 3D contributes industrial wax jetting and digital light processing wax systems engineered for high-precision investment casting with ash-free burnout characteristics. Together, these entrants illustrate how regional manufacturing ecosystems are competing not only on unit price but on throughput, material compatibility, and workflow minimization.
Competitive Concentration and Buyer Implications
The market remains moderately concentrated, with an estimated three-firm revenue concentration near fifty-eight point seven percent and a five-firm concentration approaching seventy-two point four percent. This structure indicates that a relatively small group of vendors captures a meaningful share of total revenue, which can influence pricing discipline, feature roadmaps, and after-sales service expectations. For buyers, concentration carries both advantages and risks: it can streamline evaluation and support ecosystems, but it also elevates the importance of comparative benchmarking, contract flexibility, and awareness of emerging challengers that may shift negotiating leverage over time.
Technology Segmentation and Workflow Realities
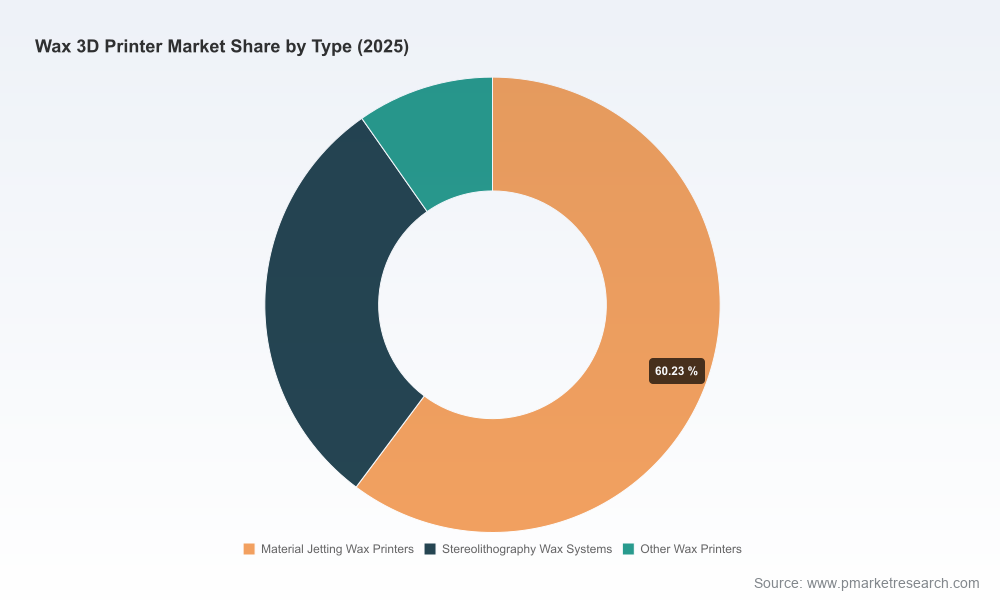
Understanding the hardware and material architecture behind revenue growth is essential for realistic planning. The market segments across three primary technology families, each carrying distinct trade-offs in resolution, support management, material handling, and post-processing requirements. Material jetting wax platforms represent the largest share of segment activity, reflecting their compatibility with intricate jewelry casting patterns and their ability to deliver fine feature reproduction with controlled material deposition. Stereolithography-based wax systems form a significant secondary pathway, offering strong surface quality and material consistency for applications where pattern integrity and predictable burnout behavior are paramount. Additional wax printer categories round out the landscape, serving specialized use cases and incremental capacity needs where form factor, footprint, or integration constraints influence selection.
Material formulation remains equally critical. Modern castable wax systems increasingly emphasize zero ash content and controlled volumetric shrinkage, both of which directly influence defect-free casting outcomes. Dual-wax configurations, in which model wax and support wax are printed concurrently, represent a practical response to labor intensity and handling variability, particularly in jewelry pattern production where geometry complexity can multiply finishing time. Meanwhile, enterprise-grade considerations are extending beyond print quality: newer systems are being designed with cybersecurity alignment in mind, including preparation for regional regulatory expectations around industrial control systems and connected device resilience. This convergence of print performance, material reliability, and operational security is reshaping how procurement teams evaluate total value rather than headline specifications alone.
Application Zones: Where Demand Is Materializing
The commercial pull behind wax printer adoption is distributed across multiple application domains, each with its own performance priorities and purchasing cycles. Jewelry casting remains the central demand anchor, driven by the need for intricate pattern fidelity, reproducible burnout behavior, and workflow efficiency in precious metal production. Dental applications constitute a substantial secondary zone, where precision, regulatory compatibility, and repeatable output influence system selection for laboratory and clinic environments. Industrial investment casting provides a third growth vector, as foundries and component manufacturers turn to digital wax generation to reduce manual pattern-making effort, improve consistency, and support higher-mix production runs. A broader set of additional applications rounds out the demand base, encompassing specialized casting workflows that benefit from customized resolution, material handling, or throughput characteristics.
These application zones do not evolve uniformly. Jewelry demand often responds quickly to design complexity trends and seasonal production cycles. Dental adoption typically hinges on laboratory scale, regulatory considerations, and integration with existing digital impression and milling workflows. Industrial casting investment decisions are more sensitive to total throughput, downtime, and the economics of pattern consolidation across part families. Recognizing these distinct buying rhythms helps organizations align internal evaluation criteria with real operational priorities rather than generic performance claims.
Forces Shaping the Market Trajectory
Several interacting dynamics will determine how the forecast period unfolds. Material innovation continues to act as a primary enabler, with castable formulations increasingly optimized for low residue, predictable shrinkage, and compatibility across multiple printer architectures. Such advances reduce defect rates and simplify downstream casting steps, which in turn strengthens the business case for digital wax adoption. On the regulatory and IT side, connected manufacturing equipment is facing heightened expectations around cybersecurity resilience and industrial control protection, prompting system designers to incorporate compliance-oriented features earlier in the product lifecycle. These requirements can influence procurement timelines, integration costs, and the attractiveness of platforms that already anticipate regional standards.
Commercial activity also signals where momentum is building. Recent product introductions have emphasized surface enhancement, speed improvements, and reduced post-processing requirements, while specific desktop-oriented industrial systems have expanded the addressable user base for jewelry pattern generation. High-volume sales rankings and recurring trade-show demonstrations further indicate that vendor attention is intensifying around jewelry manufacturing channels, where pattern quality and throughput translate directly into revenue impact. Taken together, these forces suggest a market that is not only expanding in size but also maturing in how value is measured, negotiated, and sustained.
Why the Full Study Is Essential for 2026 Strategy
The macroeconomic arc, competitive concentration, technology segmentation, and application demand described here provide a necessary foundation, but they do not reveal the full operational picture. To make confident capital and sourcing decisions, strategy teams need visibility into regional demand intensity, segment-level revenue composition, application-level sizing, vendor-specific positioning nuances, and the evolving implications of material, regulatory, and workflow shifts. These layers of intelligence determine how buyers benchmark total cost of ownership, how suppliers allocate development resources, and how incumbents defend or expand their share against new entrants. A market study that stops at aggregate figures leaves too many strategic questions unanswered.
The complete Wax 3D Printer Market research goes further by assembling a structured, decision-oriented architecture that links historical performance to forward forecasts and competitive behavior. It evaluates vendor activity across product launches, sales milestones, material strategies, and channel presence, connecting these events to revenue implications and buyer considerations. The study also situates technology choices within application-specific workflows, helping readers translate performance attributes into operational outcomes. By avoiding fragmented or oversimplified conclusions, the report supports scenario planning, vendor shortlisting, negotiation preparation, and capacity timing with a consistent evidentiary base.
Accessing the Full Intelligence Suite
For organizations preparing for 2026 procurement cycles, technology roadmapping, or market entry assessments, the full study provides the depth required to act with confidence. The complete report details regional market intensity, segment and application-level structures, competitive profiling, material and workflow considerations, and forward-looking demand signals that aggregate summaries cannot capture. Readers who engage with the full intelligence suite gain a clearer view of where growth is concentrated, which vendor strategies are most likely to influence pricing and availability, and how application-specific priorities will shape purchasing decisions over the forecast period. In a market defined by accelerating revenue, rising competitive intensity, and increasingly differentiated technology claims, structured intelligence is not optional. It is the foundation for disciplined strategy.
Discover the complete dataset, segmentation architecture, and competitive analysis by accessing the full Wax 3D Printer Market report.
For detailed analysis of this topic, please visit the official page:Wax 3D Printer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek