
Navigating the Transition: Strategic Intelligence for the Global Hybrid Dual-Clutch Transmission Market (2026–2032)
By PW Consulting – Senior Strategic Advisor & Chief Industry Analyst
Worldwide Hybrid Dual-Clutch Transmission Market
The automotive powertrain landscape is undergoing one of the most complex architectural shifts in modern industrial history. As original equipment manufacturers navigate tightening emissions architecture, evolving consumer expectations, and the relentless pursuit of thermal efficiency, hybrid dual-clutch transmissions (HDTs) have emerged as a critical bridge technology. Our latest Worldwide Hybrid Dual-Clutch Transmission Market research offers a comprehensive, decision-ready blueprint for stakeholders operating at the intersection of mechanical engineering, electrification strategy, and global supply chain optimization. Covering historical trajectories from 2020 through a detailed forecast window extending to 2032, this study translates macroeconomic momentum, technological inflection points, and competitive maneuvering into actionable intelligence tailored for 2026 enterprise planning.
Worldwide Hybrid Dual-Clutch Transmission Market
For executives, procurement leaders, R&D directors, and investment analysts, the hybrid dual-clutch segment represents more than a transitional component. It is a strategic lever that balances performance retention, cost discipline, and regulatory compliance. The market has demonstrated remarkable resilience and acceleration, with global revenue climbing steadily from just over 5.1 billion USD in 2020 to approximately 11.45 billion USD in 2025. This trajectory reflects sustained OEM commitments to mild hybrid (MHEV) and plug-in hybrid (PHEV) architectures, as well as the manufacturing scalability achieved by tier-one suppliers over the past half-decade. Looking ahead, our forecast models project continued expansion, with the market expected to surpass 13.3 billion USD in 2026 and advance toward an estimated 33.35 billion USD by 2032. The compound annual growth rate across the forecast horizon settles at 16.5 percent, signaling an environment where technological differentiation, regional deployment pacing, and supply chain agility will dictate competitive positioning.
Worldwide Hybrid Dual-Clutch Transmission Market
This report does not merely catalog historical figures. It decodes the structural forces driving them, maps the competitive terrain, and isolates the operational levers that will separate market leaders from followers. Below is a strategic overview of what the research delivers, why it matters for 2026 decision cycles, and how organizations can leverage its insights to navigate an increasingly fragmented and fast-evolving segment.
Market Trajectory and Structural Drivers
The expansion of the hybrid dual-clutch transmission market cannot be reduced to a single catalyst. Rather, it is the result of overlapping regulatory pressures, engineering optimization cycles, and platform consolidation strategies that collectively favor compact, efficient, and mechanically robust hybrid architectures. Dual-clutch configurations offer a compelling compromise: they retain the responsiveness and packaging advantages of conventional DCTs while integrating electrified drive components that meet modern efficiency mandates. This has made them particularly attractive for MHEV and PHEV applications where seamless power blending, reduced drivetrain drag, and optimized inertia characteristics are paramount.
Our historical analysis from 2020 through 2025 highlights a consistent upward curve that accelerated as OEMs scaled hybrid program volumes and suppliers matured their hybrid-compatible tooling and control software. The jump from 8.19 billion USD in 2023 to 9.96 billion USD in 2024, followed by the 11.45 billion USD mark in 2025, underscores how quickly hybrid DCT platforms have transitioned from niche engineering projects to mainstream powertrain elements. This growth is further reinforced by the ongoing integration of advanced clutch control algorithms, reduced-friction assembly designs, and modular gearset architectures that allow manufacturers to scale across vehicle segments without compromising thermal or mechanical performance.
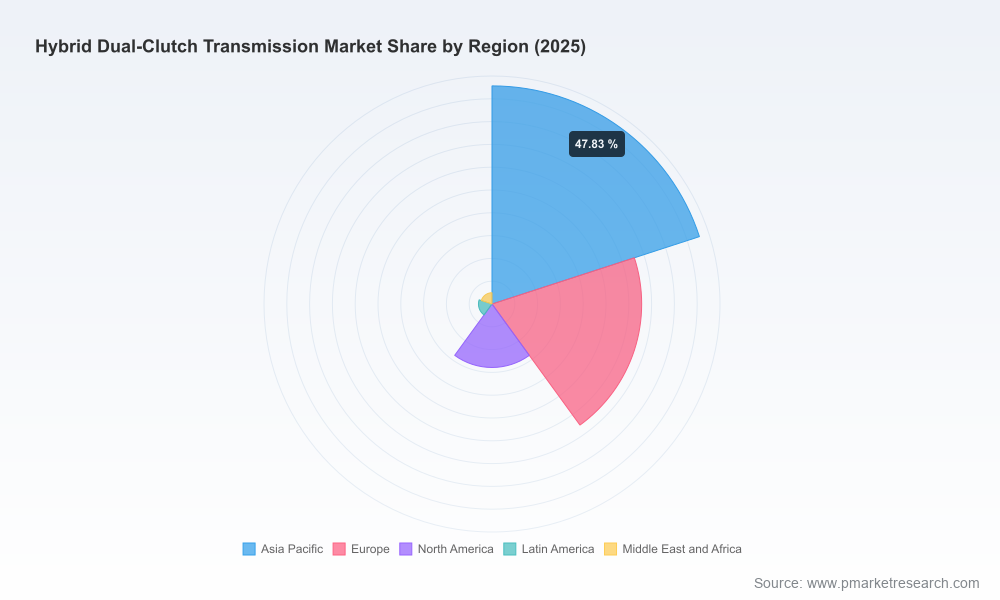
The forecast period from 2026 to 2032 reveals a market that will not simply grow in absolute terms but will also evolve in composition. Revenue progression from 13.33 billion USD in 2026 to 33.35 billion USD in 2032 reflects the compounding effect of new platform launches, expanded production capacity in key manufacturing regions, and the continued migration of ICE-derived architectures toward electrified variants. Importantly, this expansion is not uniform. Regional deployment strategies, OEM sourcing preferences, and localized content requirements will create distinct demand pockets, each demanding tailored pricing, sourcing, and capacity-planning approaches. The report unpacks these patterns without exposing proprietary segmentation figures, instead focusing on the strategic implications of geographic concentration, volume pacing, and cross-region supply chain resilience.
The Architecture of the Report: What Decision-Makers Will Access
PW Consulting’s research is structured to serve multiple functional teams simultaneously. Rather than offering a single-layer market snapshot, the study is organized into interoperable modules that can be deployed across strategic planning, procurement, engineering roadmap development, and competitive intelligence workflows. The core deliverable encompasses:
- Baseline and Forecast Modeling: A rigorous historical reconstruction from 2020 to 2025 paired with a granular 2026–2032 projection framework. The modeling isolates volume-velocity drivers, pricing evolution patterns, and the impact of platform adoption curves on revenue trajectories.
- Technology and Configuration Mapping: A detailed examination of wet and dry hybrid dual-clutch architectures, including performance trade-offs, thermal management considerations, lubrication strategies, and the engineering rationale behind P2/P2.5 versus P1/P3 layout choices. The analysis explains how architecture selection influences packaging, torque routing, electrification integration, and ultimately, vehicle segment targeting.
- Competitive Positioning and Capability Profiles: In-depth evaluations of leading suppliers and integrated manufacturers, covering their technological footprints, production readiness, program pipelines, and strategic alliances. The profiling extends beyond corporate narratives to assess real-world execution capacity, modularity, and compatibility with next-generation hybrid platforms.
- Industry Dynamics and Inflection Points: A synthesis of regulatory pressures, technology transitions, and manufacturing milestones that are actively reshaping demand signals. This includes the role of integrated motor-clutch modules, the push toward reduced inertia and drag torque, the scaling of dedicated hybrid transmission families, and the strategic implications of in-house versus outsourced DCT production.
- Strategic Playbooks for 2026 and Beyond: Actionable recommendations for capacity planning, supplier selection, platform risk mitigation, and regional deployment sequencing. The report identifies where early-mover advantages are forming, where consolidation pressures are intensifying, and how organizations can structure their roadmaps to capture value without overcommitting to legacy architectures.
Throughout the document, macro-level indicators are presented with precision, while granular breakdowns remain reserved for the full dataset. This deliberate framing ensures that readers gain enough technical and market context to validate the study’s analytical rigor, while preserving the proprietary granularity that justifies direct engagement with the complete research package. For organizations requiring detailed regional splits, exact type and architecture revenue distributions, or precise concentration metrics, the full report delivers the structured data necessary for investment committee reviews, sourcing negotiations, and long-range capacity planning.
Competitive Landscape: Who Is Shaping the Next Phase
The hybrid dual-clutch transmission market is characterized by a concentrated yet highly dynamic competitive environment. At the top tier, a limited group of multinational suppliers and integrated automotive manufacturers commands a substantial share of global volume, while a broader field of specialized engineers, regional players, and platform-focused consortia competes on differentiation, cost structure, and localized program execution. Our analysis places the competitive field within a clear hierarchy of capability, scale, and strategic ambition.
German engineering organizations continue to anchor much of the high-performance and efficiency-driven segment. ZF Friedrichshafen AG has built a recognizable footprint in hybrid-compatible dual-clutch solutions and electrified drive systems, with an emphasis on mild and plug-in hybrid applications where integration density and efficiency are critical. Schaeffler AG has reinforced its position through systematic expansion of hybrid transmission systems and component portfolios, most notably through its 2026 launch of mass production at its Taicang facility in China—a milestone that directly aligns with global electrified vehicle demand and signals a commitment to cost-optimized, high-volume deployment. Continental AG and Aisin Corporation further round out the tier-one ecosystem, providing integrated transmission modules, control systems, and hybrid-compatible DCT platforms that support broader passenger vehicle powertrain strategies.
North American and transatlantic suppliers are equally active in shaping the segment. BorgWarner Inc. has secured multiple program wins, including a seven-year extension for a DCT clutch assembly with a German OEM applicable to mild hybrid models and a new program supporting Chinese OEM SUVs and sedans targeting mass production by the end of 2025. These agreements reflect a clear strategic focus on reduced inertia, minimized friction losses, and lower drag torque—an engineering philosophy that directly supports overall powertrain efficiency. Magna International Inc., including its Getrag heritage, has positioned itself through scalable Eco Family DCT platforms and next-generation hybrid dual-clutch transmissions, securing supply contracts for Mercedes-Benz compact and mid-size vehicles launching in 2025 while transitioning its DCT Eco solutions from ICE to hybrid applications. Dana Incorporated, through its Graziano engineering lineage, has pushed into modular high-performance hybrid 8-speed dual-clutch transmissions capable of supporting high-torque hybrid applications up to 1,000+ horsepower. The recognition of this modular HDCT with the Automotive News PACE Award in April 2025 highlights how transverse layouts and optimized power density are becoming central to vehicle dynamics and weight distribution in hybrid powertrains.
European specialists and integrated automakers add further layers of strategic complexity. Punch Powertrain has built a diversified hybrid transmission portfolio encompassing mild hybrid DCT, plug-in hybrid DCT, and dedicated hybrid transmission solutions, while also drawing on prior eDCT joint venture experience. Stellantis N.V. represents a distinct model: rather than relying solely on external sourcing, the company has pursued in-house production of electrified dual-clutch transmissions integrating a 21-kW electric motor for mild and plug-in hybrid vehicles across multiple European plants. Its full acquisition of the eDCT joint venture previously associated with Punch Powertrain, alongside the announcement of a 300,000-unit annual production target at the Termoli plant starting in 2026, illustrates a broader industry trend toward vertical control of critical electrified powertrain assets. The expansion of production hubs in Metz and Mirafiori further underscores how OEMs are building redundancy, regional flexibility, and platform scale to support hybrid product line growth.
Asia-Pacific and broader global participants continue to expand their relevance. Hyundai Transys Inc. leverages its parent group’s hybrid vehicle platforms to deliver cost-effective hybrid-compatible DCT solutions, while Aisin Corporation and Jatco Ltd. maintain strong positions in passenger vehicle DCT systems with hybrid compatibility integrated into wider powertrain offerings. Eaton Corporation and Valeo contribute through transmission technologies and hybrid powertrain components, including clutch and control elements tailored for DCT environments. Together, these players illustrate a market where scale, regional sourcing advantages, and engineering specialization are converging to redefine competitive boundaries.
Market concentration metrics reinforce the strategic significance of this landscape. The top three players account for approximately 48.35 percent of global revenue, while the top five extend their collective share to roughly 64.12 percent. This concentration does not imply stagnation; rather, it highlights the importance of execution speed, program win rates, and architectural versatility. Suppliers that can combine modular platform design, scalable production, and rapid adaptation to OEM electrification roadmaps are best positioned to capture incremental share, while those reliant on single-architecture dependence or rigid sourcing models face mounting pressure as hybrid DCT demand diversifies across vehicle classes and regions.
Industry Dynamics: Technology, Regulation, and Manufacturing Reality
The hybrid dual-clutch transmission segment is being reshaped by a triad of forces: regulatory efficiency mandates, technology integration requirements, and manufacturing scalability constraints. Each force influences the other, creating a feedback loop that rewards organizations capable of aligning engineering design with compliance strategy and production readiness.
On the regulatory and efficiency front, hybrid DCT systems are increasingly evaluated not just on gearshift quality or packaging, but on their contribution to overall powertrain efficiency targets. The integration of a 21-kW electric motor into dual-clutch transmissions for mild and plug-in hybrid applications demonstrates how OEMs are using electrified DCT architectures to meet emissions and efficiency compliance needs without abandoning the mechanical responsiveness that drivers and engineering teams value. Simultaneously, supplier-level innovations are emphasizing reduced rotational inertia, minimized friction losses, and lower drag torque in clutch assemblies. These improvements are not incremental in name only; they directly influence energy recapture, idle drag, and real-world consumption figures, making them central to competitive differentiation in hybrid DCT design.
From a technology and architecture perspective, modularity is becoming a defining principle. Scalable 6-speed dual-clutch bases with virtual gear strategies and hybrid integration options for 48V, HEV, and PHEV applications allow platforms to span multiple vehicle segments without requiring complete redesign cycles. High-performance hybrid 8-speed DCTs with transverse layouts are similarly gaining traction for their ability to optimize weight distribution and support high-torque applications. These architecture choices are not purely engineering decisions; they dictate manufacturing complexity, tooling investment, supplier qualification pathways, and ultimately, time-to-market. Organizations that can balance modularity with performance integrity will be better positioned to absorb program volatility and adapt to shifting OEM volume commitments.
Manufacturing and supply chain dynamics add another layer of strategic importance. The 2026 launch of mass production for new hybrid transmission systems at Schaeffler’s Taicang facility, the expansion of Stellantis’ eDCT production footprint across European plants, and the securing of long-duration DCT program contracts by major suppliers all point to a market that is transitioning from pilot-scale validation to high-volume execution. This shift places a premium on capacity planning, quality consistency, regional content alignment, and the ability to synchronize component supply with platform launch schedules. For procurement and operations leaders, the implications are clear: sourcing strategies must account not only for unit pricing but also for production readiness, engineering support, and the resilience of supplier networks under multi-program load.
Why This Research Matters for 2026 Decision-Making
Enterprise decisions made in 2026 will set the trajectory for hybrid powertrain portfolios, supplier partnerships, and capacity investments through the end of the decade. The hybrid dual-clutch transmission market is no longer a peripheral consideration; it is a core component of platform strategy, cost architecture, and competitive positioning. Our research is designed to support those decisions with structured analysis, defensible forecasting, and practical strategic guidance.
For executive leadership and corporate strategy teams, the study provides a clear view of market momentum, growth concentration, and the timing of potential inflection points. Understanding how revenue is projected to scale from 13.33 billion USD in 2026 toward 33.35 billion USD in 2032 helps organizations align long-range planning with realistic demand scenarios rather than speculative narratives. For procurement and sourcing professionals, the competitive profiling and capability assessments offer a framework for evaluating supplier readiness, modular platform compatibility, and regional manufacturing strength. For engineering and product planning teams, the architecture and technology mapping clarifies the trade-offs between wet and dry hybrid DCT configurations, P2/P2.5 and P1/P3 layout choices, and the implications of integrated motor-clutch systems for future vehicle programs.
Equally important, the report addresses the strategic risks embedded in rapid market evolution. Concentration patterns, program dependency, and the push toward vertical integration all create scenarios where early commitment can yield advantage, but misjudged platform bets can impose long-term cost penalties. By mapping recent developments—including award-winning modular HDCT designs, multi-year DCT program extensions, eDCT production expansions, and the acquisition of joint venture control by major automakers—the study highlights the kinds of moves that are reshaping competitive positioning in real time. Decision-makers who understand these signals can better anticipate where capacity will tighten, where platform overlap will increase, and where differentiated value will be captured.
Conclusion: Turning Market Intelligence into Strategic Advantage
The Worldwide Hybrid Dual-Clutch Transmission Market report is built for organizations that require more than a high-level summary. It delivers a rigorous, forward-looking analysis of a segment defined by rapid technological integration, concentrated competition, and accelerating production scale. By combining historical reconstruction, forecast modeling, architecture-level evaluation, and competitive intelligence, the study equips stakeholders with the context needed to make confident 2026 decisions and the discipline to plan through 2032.
The macro trajectory is unmistakable: sustained double-digit growth, expanding hybrid DCT adoption across MHEV and PHEV platforms, and a competitive field where engineering versatility and manufacturing execution increasingly determine market share. Yet the most valuable insights—the detailed regional demand distributions, exact type and architecture revenue splits, program-level supply dynamics, and proprietary concentration breakdowns—reside within the full research dataset. Organizations that access the complete report will gain the granular intelligence necessary to refine sourcing strategies, prioritize platform investments, and position themselves advantageously in a market where speed, precision, and strategic foresight will define the next generation of hybrid powertrain leadership.
For teams preparing for 2026 planning cycles, this research offers a clear pathway from market awareness to execution readiness. The hybrid dual-clutch transmission segment will continue to reward those who can align technology strategy with regulatory reality, supplier capability with production scale, and regional demand signals with disciplined capacity planning. PW Consulting’s analysis provides the foundation to do exactly that.
For detailed analysis of this topic, please visit the official page:Worldwide Hybrid Dual-Clutch Transmission Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Portuguese (Brazil)
 Greek