
Strategic Intelligence for the Forward-Looking Enterprise: Why the Worldwide Organic Grassfed Milk Market Demands Your Attention in 2026
The global dairy landscape is undergoing a structural realignment. Consumer preferences are shifting decisively toward transparency, regenerative agriculture, and production systems that align with both personal health and environmental stewardship. Within this transformation, organic grassfed milk has emerged as one of the most strategically significant categories for food and beverage executives, supply chain leaders, and investment professionals. Yet, meaningful participation in this market requires more than surface-level trend awareness. It demands precise, forward-looking intelligence grounded in historical performance, regulatory realities, and competitive dynamics.
Worldwide Organic Grassfed Milk Market
This article serves as a strategic preview of PW Consulting's latest comprehensive study: the Worldwide Organic Grassfed Milk Market report. Designed for decision-makers operating across the 2026–2032 horizon, this research translates complex market signals into actionable intelligence. Below, we outline the macro trajectory, the structural dimensions of the market, the competitive architecture shaping the category, and the operational realities that will define success in the coming years. The full report contains granular segmentation, detailed company benchmarking, and scenario models that executives need to stress-test their strategies.
Worldwide Organic Grassfed Milk Market
The Macro Trajectory: Reading the Numbers as Strategic Signals
Understanding where the market has been is essential to anticipating where it is headed. The historical record from 2020 through 2025 reveals a consistent expansion pattern that has accelerated beyond the broader organic dairy segment. The global market for organic grassfed milk has demonstrated robust year-over-year growth, with valuation rising from approximately 1,452.12 million USD in 2020 to 2,286.0 million USD by 2025. This trajectory reflects not merely a post-pandemic recovery effect but a durable shift in consumer willingness to pay a premium for pasture-raised, grassfed-certified dairy products.
Worldwide Organic Grassfed Milk Market
Looking ahead, the forecast period spanning 2026 to 2032 projects continued momentum. The market is expected to reach 2,415.48 million USD in 2026, followed by steady expansion toward 4,497.47 million USD by 2032. This growth pathway corresponds to a compound annual growth rate of 10.15 percent over the forecast horizon. For strategic planners, a double-digit CAGR is not simply a statistic to cite in investor presentations. It is a signal that the category is entering a phase where scale, distribution density, and supply chain resilience will determine which organizations capture disproportionate value. Companies that treat this growth as a guaranteed tailwind without investing in structural readiness risk being outmaneuvered by competitors who are already positioning for the next inflection point.
The sheer magnitude of the expansion—from a sub-1.5 billion USD ecosystem in 2020 to a projected near-4.5 billion USD market by 2032—also implies that the competitive landscape will evolve rapidly. New entrants, private label expansion, international brand cross-border strategies, and consolidation among established players are all plausible outcomes within this growth corridor. Decision-makers must evaluate whether their current product portfolios, manufacturing footprints, and channel partnerships are configured to absorb this kind of market velocity.
Beyond the Top-Line Figure: Structural Dimensions of the Market
A macro valuation tells only part of the story. The real strategic value of comprehensive market research lies in its ability to dissect the topology of demand, supply, and distribution. The Worldwide Organic Grassfed Milk Market study maps the category across multiple structural axes, enabling readers to identify where growth is most concentrated, where margins are most protected, and where operational bottlenecks are likely to emerge.
Product Type Architecture
The market is fundamentally segmented by product formulation, with whole milk and reduced fat milk representing the two primary categories driving revenue. Whole milk continues to command strong consumer loyalty, particularly among demographics that prioritize full-fat dairy for culinary applications, nutritional preferences, and sensory satisfaction. Reduced fat milk, meanwhile, serves a parallel demand stream from health-conscious consumers who seek the grassfed organic designation without the full-fat profile. The report examines how these two product archetypes perform relative to one another, including their respective contributions to overall market revenue, the pricing dynamics that differentiate them, and the manufacturing considerations that influence production planning. Understanding the balance between these segments is critical for brands deciding whether to expand SKU breadth, focus on hero products, or develop tiered offerings that capture multiple consumer sensibilities.
Distribution Channel Dynamics
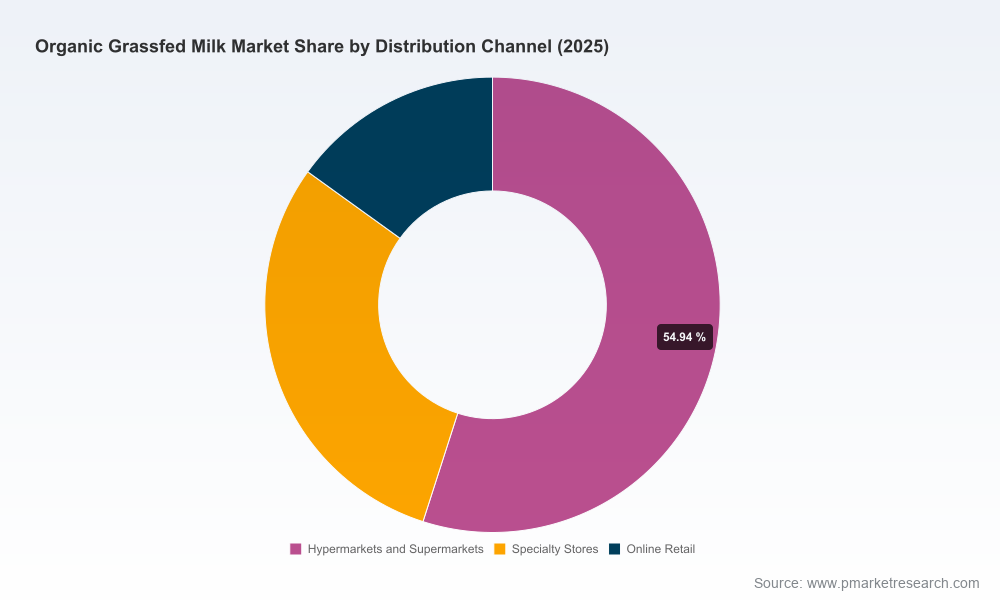
Where consumers purchase organic grassfed milk is as strategically important as what they purchase. The channel landscape spans hypermarkets and supermarkets, specialty stores, and online retail environments. Each channel carries distinct implications for brand positioning, margin structure, logistics complexity, and consumer reach. Mass retail channels offer volume and visibility but often demand aggressive slotting cooperation, pricing discipline, and competitive shelf management. Specialty stores provide a curated environment where premium positioning and storytelling can command stronger brand affinity, though they typically require a more deliberate path to scale. Online retail has matured into a meaningful channel for dairy products, driven by subscription models, home delivery infrastructure, and the convenience-seeking behavior of urban and suburban consumers. The report evaluates how these channels interact, where growth is most pronounced, and what operational capabilities are required to serve each effectively.
Geographic Distribution and Regional Intelligence
Demand for organic grassfed milk is not evenly distributed across the globe. Regional markets differ substantially in terms of consumer awareness, regulatory frameworks, pasture-based farming traditions, and retail infrastructure. The study provides a regional breakdown that illuminates which geographies are currently driving the largest revenue contributions, how growth patterns vary by region, and what localization strategies are necessary for brands seeking international expansion. North American markets benefit from established organic certification infrastructure, a deep culture of pasture-based dairy farming, and robust retail demand. European markets bring their own regulatory nuances, strong heritage dairy traditions, and increasing consumer emphasis on animal welfare and environmental sustainability. Asia Pacific and other emerging regions represent markets where organic grassfed dairy is still building awareness but where urban middle-class growth and premiumization trends create long-term opportunity. The full report details the regional landscape without oversimplifying the complexities of cross-border entry, local certification requirements, and channel-specific execution.
The Competitive Architecture: Who Is Shaping the Category and How
No strategic assessment of the organic grassfed milk market is complete without a rigorous examination of the competitive field. The category features a diverse mix of cooperative models, family farm networks, large-scale organic producers, private label suppliers, and international dairy groups. Together, these players define the pricing benchmarks, product innovation pace, and consumer trust dynamics that shape the market. The study profiles the leading organizations and analyzes how their operating models, product strategies, and recent moves position them within the broader competitive structure.
Among the notable participants, Organic Valley (CROPP Cooperative), headquartered in La Farge, Wisconsin, stands out for its Grassmilk line of 100 percent organic grass-fed milk products sourced from pasture-raised cows with no grain supplementation. The cooperative model gives it a distinctive supply chain structure, and its product range spans whole milk, reduced fat milk, and half & half variants. Maple Hill Creamery, based in New York, has built its identity around 100 percent grass-fed organic milk sourced from a network of small family farms, offering whole and reduced fat options alongside other grass-fed dairy products. Its recent expansion activity underscores the strategic importance of scaling farmer networks while preserving the family farm narrative that resonates with consumers.
Horizon Organic, operating under Danone North America and headquartered in Broomfield, Colorado, produces USDA Organic grass-fed milk lines, including whole and reduced fat variants from pasture-raised cows, with additional grass-fed certifications that reinforce its positioning. Aurora Organic Dairy, based in Boulder, Colorado, operates at a larger production scale, supplying both private label and branded fluid milk, creamers, and related dairy products, including grass-fed options. Straus Family Creamery in Petaluma, California, represents the family farm, pasture-based system approach, offering organic grass-fed milk and dairy products that align with a sustainability-forward brand identity. Alexandre Family Farm in Crescent City, California, focuses on organic A2 grass-fed milk from regenerative pasture-raised herds, illustrating how nutritional differentiation and regenerative agriculture narratives can intersect. Kalona SuperNatural, located in Kalona, Iowa, emphasizes organic, grass-fed milk and cream-top whole milk from small family farms, reinforcing the appeal of small-scale, authenticity-driven production.
On the international side, Arla Foods, headquartered in Viby, Denmark, offers organic dairy lines that include grass-fed milk variants in European and international markets, demonstrating how global dairy cooperatives are extending grass-fed organic offerings beyond domestic boundaries. Traders Point Creamery in Zionsville, Indiana, rounds out the competitive picture with its 100 percent grass-fed organic fluid milk, cheese, and other dairy products derived from biodynamic farming practices, highlighting the role of certified biodynamic and regenerative approaches in building brand distinction.
The market structure also reflects meaningful concentration. Current data indicates that the top three firms hold approximately 36.4 percent of market revenue, while the top five firms account for roughly 51.25 percent. This concentration pattern suggests that although the category has room for differentiated niche players, a significant share of total revenue flows through a relatively compact set of established organizations. For new entrants and smaller brands, this implies that scaling will require either a compelling differentiation strategy, a channel-specific focus, or partnerships that provide access to broader distribution and supply chain capabilities. For incumbents, it underscores the importance of defending share through product excellence, consumer trust, and operational efficiency.
The Operational Reality: Regulation, Production Economics, and Supply Signals
Market growth does not occur in a vacuum. The economics of producing grass-fed organic milk are shaped by labor intensity, forage management, pasture access, and certification requirements that differ from conventional organic production. Academic and industry production cost analyses indicate that the average cost of production for grass-fed organic milk can reach approximately 45.91 USD per hundredweight, reflecting the higher operational demands of pasture-based systems. Meanwhile, pay prices for grass-fed organic certified dairies have ranged from 36 USD to 52 USD per hundredweight in recent reporting periods, highlighting the persistent cost premium relative to conventional organic production and the sensitivity of producer economics to market conditions.
Regulatory complexity adds another layer of strategic consideration. The USDA does not currently maintain a federal definition for grass-fed milk, which means that third-party certifications have become the primary mechanism for signaling grass-fed claims to consumers. Standards from organizations such as the American Grassfed Association and the Organic Plus Trust commonly require minimum pasture dry matter intake of 60 percent or higher during the grazing season, with stricter labels mandating no grain supplementation. For brands, this landscape creates both opportunity and risk. Opportunity exists for credible certifications to command consumer trust and justify premium positioning. Risk arises from inconsistent label definitions, potential consumer confusion, and the need to ensure that marketing claims align with verifiable production practices. Companies that invest in transparent certification, robust traceability, and clear consumer education are better positioned to navigate this fragmented regulatory environment.
Supply-side dynamics are equally critical. In early 2026, organic milk shortages in the United States contributed to higher mailbox prices for producers, with grass-fed certified milk experiencing increases in the range of 8 to 15 USD per hundredweight. These supply constraints illustrate how tightly balanced the market can become and how quickly input economics can shift. For brands and retailers, such conditions can affect SKU availability, promotional flexibility, and margin planning. The study incorporates these kinds of supply-demand signals into its forward analysis, enabling readers to anticipate scenario outcomes rather than simply react to them.
Recent Market Moves That Matter for Strategic Planning
Recent events across the competitive field provide a real-time window into the operational and strategic pressures shaping the category. In July 2025, Maple Hill Creamery expanded its farm network by adding 14 new farms in Central Pennsylvania, bringing its total network to 120 small family farms dedicated to 100 percent grass-fed organic dairy production. This move highlights a deliberate scaling strategy that seeks to grow supply capacity while preserving the small family farm positioning that underpins its brand identity. It also demonstrates the logistical challenge of integrating new farms into a consistent quality and certification system, a challenge that any organization attempting to scale grass-fed supply chains must manage carefully.
In the pricing arena, adjustments have been made to reflect supply considerations. During the period from March through August 2026, a pricing adjustment increased the over price to match the base price of 45.36 USD per hundredweight for Maple Hill producers, driven by organic milk supply considerations. Such adjustments reveal how pricing mechanics in the grass-fed organic sector are responsive to supply tightness and how producer economics can shift within a single season. For buyers, brand managers, and supply chain planners, these dynamics carry direct implications for cost planning, contract structures, and inventory strategy.
Quality and safety events also influence market confidence. In December 2024, Horizon Organic Dairy, LLC initiated a voluntary Class II recall of approximately 19,688 cases of Horizon Organic Aseptic Plain Whole Milk 8 oz 12-packs due to the potential for premature spoilage, affecting best-before dates in early March 2025. While recalls are an inherent risk in any food category, the episode serves as a reminder of the operational precision required in aseptic processing, distribution temperature control, and quality assurance systems. In a market where consumers pay a premium for trust and purity, quality incidents can have amplified reputational effects, making robust quality management a strategic imperative rather than a back-office function.
On the consumer trust front, independent laboratory analysis reported in November 2024 tested Organic Valley's Grassmilk Half & Half and found it clean for heavy metals. In a category where consumers are increasingly attentive to contaminant risks and ingredient purity, such testing outcomes can reinforce brand credibility. At the same time, they reflect a broader industry trend in which transparency, third-party verification, and proactive testing are becoming important differentiators in a crowded premium dairy market.
What the Full Report Delivers: From Insight to Execution
The executive overview provided here is intended to communicate the depth and relevance of the full study, but it is by design a strategic preview rather than a complete data package. The Worldwide Organic Grassfed Milk Market report is built to support decision-making across multiple functional areas, including product strategy, supply chain planning, competitive positioning, and investment analysis.
Inside the report, readers will find:
- A detailed historical and forecast revenue analysis covering the 2020–2032 period, with breakdowns that reveal growth pacing and inflection points across the market's structural segments.
- Segment-level intelligence across product type, distribution channel, and region, enabling readers to identify where demand is strongest, where channel shift is occurring, and where geographic expansion may offer the most favorable risk-adjusted returns.
- A competitive landscape assessment that profiles leading companies, examines operating models, and evaluates how recent expansions, pricing adjustments, product recalls, and testing outcomes affect relative market positioning.
- An analysis of market concentration and its implications for entry strategy, share defense, partnership opportunities, and consolidation risk.
- Contextual coverage of production economics, certification standards, regulatory gaps, and supply-demand signals that shape margin potential, sourcing strategy, and brand messaging.
- Practical scenario considerations that help executives stress-test assumptions around supply availability, pricing volatility, channel mix shifts, and consumer trust dynamics.
The report is structured to serve strategists who need more than high-level trend commentary. It is designed for teams that are evaluating new product launches, assessing private label opportunities, planning geographic entry, renegotiating supplier contracts, or seeking to understand where competitive vulnerabilities and advantages are likely to emerge over the next several years.
Why 2026 Is a Defining Year for Strategic Positioning
The forecast period begins in 2026, and the market conditions entering this year already reflect a convergence of forces: sustained consumer demand for organic and grass-fed products, supply constraints that are influencing producer economics, regulatory ambiguity around grass-fed labeling, and competitive activity that ranges from farm network expansion to pricing adjustments and quality management scrutiny. Together, these forces create a market environment in which preparation matters more than ever.
Organizations that enter 2026 with a clear understanding of market size trajectory, segment composition, channel dynamics, competitive behavior, and operational cost structures will be better equipped to make informed decisions about capacity, pricing, marketing investment, and partnership strategy. Those that rely on anecdotal signals or outdated segmentation models risk misreading the pace of growth, overestimating margin headroom, or underestimating the operational complexity of scaling grass-fed supply chains.
The 10.15 percent compound annual growth rate projected for the 2026–2032 period is an invitation to act, but it is also a warning that growth of this magnitude attracts attention, competition, and operational strain. The organizations that capture durable value will be those that combine strategic ambition with operational discipline, consumer trust with supply chain resilience, and product differentiation with credible certification and transparency.
Next Steps: Accessing the Full Strategic Intelligence
This article has outlined the strategic contours of the worldwide organic grassfed milk market and highlighted why the 2026–2032 horizon is a critical window for decision-making. The macro growth trajectory, the segmentation architecture, the competitive field, and the operational realities described here provide a foundation for understanding the opportunity and the challenges. However, the full report contains the detailed segmentation data, regional breakdowns, company-specific analysis, and scenario frameworks that executives need to move from general awareness to concrete action.
To access the complete market intelligence, including the granular segmentation splits, in-depth competitive profiles, regulatory and supply-side context, and forward-looking forecast models, we invite you to visit the source page for the Worldwide Organic Grassfed Milk Market study. The full research package is designed to support strategy development, investment evaluation, and operational planning with the level of precision that high-stakes decisions demand.
In a category defined by premium positioning, supply complexity, and evolving consumer expectations, informed strategy is the difference between capturing growth and being overtaken by it. The report is built to provide that informed strategy.
For detailed analysis of this topic, please visit the official page:Worldwide Organic Grassfed Milk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek