
Strategic Intelligence for the Next Era: Inside the Worldwide Surgical Disguised Refrigeration Cryoablation System Market
The landscape of minimally invasive surgical interventions is undergoing a profound transformation, driven by an aging global population, the rising prevalence of chronic diseases, and a relentless push toward procedures that reduce recovery times and hospital stays. At the forefront of this shift is the surgical disguised refrigeration cryoablation system market. As medical technology converges with advanced thermodynamic principles, cryoablation has evolved from a niche dermatologic tool to a cornerstone therapy in oncology and cardiology. For stakeholders navigating the complexities of 2026, understanding the trajectory of this market is not merely an academic exercise; it is a critical component of strategic planning, capital allocation, and competitive positioning.
Worldwide Surgical Disguised Refrigeration Cryoablation System Market
This article serves as a comprehensive overview of the dynamics shaping this sector, drawing upon recent industry analysis to highlight the opportunities and challenges that define the Worldwide Surgical Disguised Refrigeration Cryoablation System Market. By examining historical growth patterns, regulatory milestones, and the evolving competitive landscape, we aim to provide decision-makers with the context needed to anticipate market movements through the end of the decade.
Worldwide Surgical Disguised Refrigeration Cryoablation System Market
Market Trajectory and Growth Dynamics
The momentum within the surgical cryoablation sector is underscored by a compelling growth narrative. Historical data from 2020 through 2025 reveals a consistent upward trend, with the total market revenue expanding from approximately 458.2 million USD in 2020 to an estimated 742.5 million USD in 2025. This progression reflects not only the adoption of established technologies but also the successful integration of cryoablation into broader treatment protocols across multiple medical specialties.
Worldwide Surgical Disguised Refrigeration Cryoablation System Market
Looking ahead, the forecast period from 2026 to 2032 suggests continued robust expansion. Projections indicate that the market will reach an estimated value of 788.76 million USD in 2026, accelerating toward 1,437.73 million USD by 2032. This trajectory corresponds to a compound annual growth rate (CAGR) of approximately 9.91 percent, a figure that signals strong investor confidence and sustained clinical demand. Such growth rates are rarely sustained over multi-year horizons without fundamental drivers, suggesting that the underlying value proposition of cryoablation systems is gaining traction among healthcare providers and payers alike.
Several macro-level factors contribute to this optimistic outlook. The shift toward outpatient and ambulatory surgical centers creates demand for compact, efficient, and versatile ablation systems. Additionally, the emphasis on reducing the burden of chronic conditions such as cardiac arrhythmias and solid tumors aligns perfectly with the minimally invasive nature of cryoablation. As reimbursement frameworks continue to evolve to support these procedures, the economic viability of adopting advanced cryoablation platforms becomes increasingly attractive for hospital networks and independent surgical facilities.
Segmentation Insights: Technology and Application Vectors
The market is not monolithic; rather, it is defined by distinct technology platforms and application areas that cater to specific clinical needs. Understanding the relative positioning of these segments is essential for manufacturers and investors seeking to identify high-value opportunities.
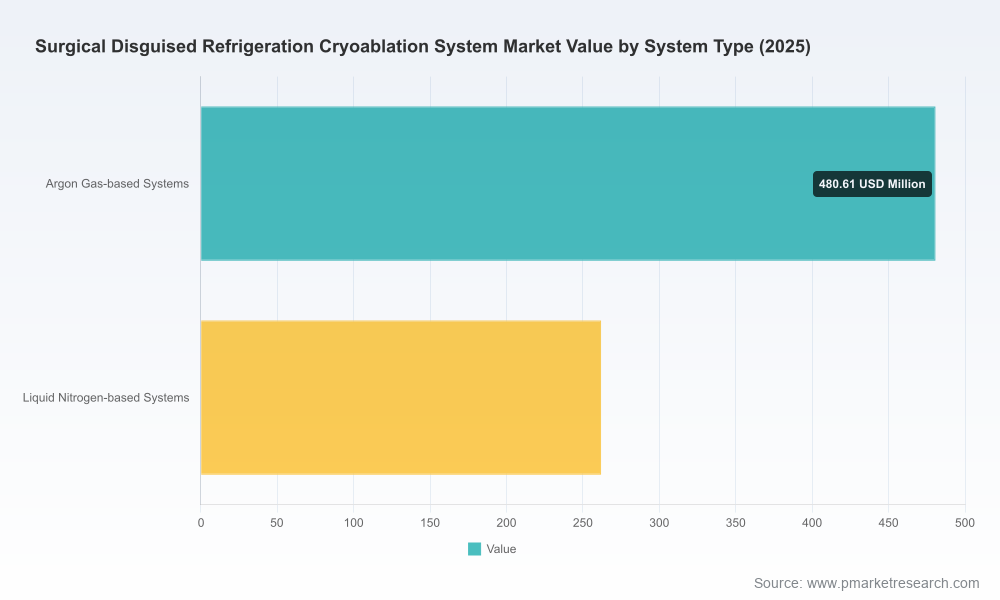
From a technological standpoint, the market is primarily divided between systems utilizing argon gas-based mechanisms and those relying on liquid nitrogen-based systems. Argon gas-based systems have historically held a significant share, leveraging the Joule-Thomson effect to achieve precise temperature control during procedures. These systems are widely recognized in cardiac applications, where rapid freezing and defrosting cycles are critical for isolating pulmonary veins and treating arrhythmias. Conversely, liquid nitrogen-based systems offer distinct advantages in certain oncology contexts. By utilizing refillable dewars, these systems can operate without the need for on-site gas lines or the management of hazardous waste associated with some gas-based alternatives. This logistical flexibility has driven adoption in percutaneous tumor ablation scenarios where portability and simplicity are paramount.
In terms of clinical application, oncology and cardiology represent the dominant forces driving market volume. Oncology applications encompass a broad range of solid tumors, including those in the liver, kidney, lung, and breast. The ability to destroy tissue with minimal damage to surrounding structures makes cryoablation an appealing option for patients who may not be candidates for traditional resection. Cardiology, meanwhile, continues to be a high-growth area, particularly in the management of atrial fibrillation and other arrhythmias. The precision required for cardiac procedures has spurred innovation in catheter design and console functionality, reinforcing the sector's reliance on specialized cryoablation platforms. Additional applications in dermatology and gynecology, while smaller in relative volume, contribute to the diversification of the market and provide entry points for new technologies targeting specific indications.
Regional distribution of market activity also reveals important patterns regarding healthcare infrastructure and adoption rates. North America remains a substantial contributor to global revenue, supported by a mature healthcare system, high per-capita spending on medical devices, and a proactive regulatory environment that facilitates the introduction of innovative devices. Europe follows as a significant secondary market, characterized by diverse healthcare systems and a strong emphasis on evidence-based adoption. The Asia Pacific region represents a dynamic growth engine, where expanding healthcare access, rising medical tourism, and increasing investment in advanced surgical technologies are creating new avenues for market penetration. Latin America and the Middle East and Africa, while currently representing smaller shares of total revenue, offer long-term potential as healthcare infrastructure develops and awareness of minimally invasive options grows.
Competitive Landscape and Strategic Positioning
The competitive environment within the worldwide surgical disguised refrigeration cryoablation system market is characterized by a mix of established medical device giants and specialized innovators. The market exhibits a notable degree of concentration, with the top three companies accounting for a significant portion of total revenue, while the top five firms collectively represent an even larger share. This concentration suggests that scale, regulatory expertise, and established clinical relationships play crucial roles in securing market position.
Medtronic, headquartered in Dublin, Ireland, stands as a prominent player with its CryoConsole cardiac cryoablation system. Utilizing nitrous oxide refrigerant, the CryoConsole powers and regulates approved cryoablation catheters used in heart arrhythmia procedures. The Arctic Front family of devices, designed for pulmonary vein isolation, exemplifies the company's focus on cardiac applications where reliability and clinical outcomes are paramount. Medtronic's extensive distribution network and deep integration into cardiac care protocols provide a formidable moat in this segment.
Boston Scientific, based in Marlborough, Massachusetts, offers a diversified portfolio that spans interventional oncology and cardiac ablation. Its ICEfx system, an argon-only compact design, is utilized for percutaneous tumor ablation across general surgery, oncology, urology, and other fields. The Visual ICE system adds MRI compatibility options, enhancing its utility in environments where advanced imaging is critical. In the cardiac space, the POLARx system provides an alternative for cryoablation procedures, demonstrating Boston Scientific's ability to compete across multiple therapeutic areas.
AtriCure, located in Mason, Ohio, specializes in the cryoICE cryoablation probes, which also employ nitrous oxide. These probes are marketed for concomitant surgical ablation in cardiac arrhythmias, emphasizing quick freeze times, high heat absorption, and active defrost capabilities. AtriCure's focus on surgical concomitant ablation positions it uniquely within the cardiac surgery ecosystem, where integration with other surgical workflows is essential.
IceCure Medical, based in Caesarea, Israel, has made significant strides with its ProSense cryoablation system, which is powered by liquid nitrogen. The system is designed for minimally invasive tumor destruction in breast, kidney, lung, liver, and other applications. IceCure's recent regulatory achievements highlight the growing acceptance of cryoablation in oncology. In October 2025, the FDA granted marketing authorization for the ProSense system for the local treatment of low-risk breast cancer in women aged 70 and older when combined with adjuvant endocrine therapy. Building on this, in March 2026, the FDA approved the study design for the post-marketing ChoICE Trial, with patient enrollment expected to commence in the second half of 2026 across 30 U.S. sites. These milestones underscore the potential for expanded indications and broader adoption in breast cancer care.
HealthTronics (Endocare), headquartered in Austin, Texas, supplies cryoablation systems and precision cryoprobes, including the Percryo and V-Probe. The company's rental and service models provide flexible access to healthcare facilities, enabling adoption without substantial upfront capital expenditure. This approach is particularly relevant for clinics and smaller hospitals seeking to offer cryoablation services while managing financial risk. HealthTronics' focus on prostate, kidney, liver metastases, and other tumors reflects the diverse oncological applications of its technology.
Hygea Medical Technology, based in Beijing, China, introduces an innovative approach with the AI EPIC Co-Ablation System. This platform combines ultra-low-temperature cryoablation at -196°C with controlled heating at +85°C, offering a dual-modality approach to tumor management within a single minimally invasive platform. In January 2025, Hygea received FDA 510(k) clearance for its Co-Ablation System with Sterile Co-Ablation Probe, recognizing it as substantially equivalent to predicates for cryosurgical destruction of solid tumors. This clearance opens the door for the system's use in the U.S. market and demonstrates the potential for hybrid ablation technologies to gain regulatory acceptance.
Varian Medical Systems, now part of Siemens Healthineers and headquartered in Palo Alto, California, contributes to the competitive landscape with the CryoCare Touch cryoablation system. Featuring a touch-screen interface, the system is designed for minimally invasive ablation of renal and prostate tissue. Varian's integration into the broader Siemens Healthineers ecosystem may offer advantages in terms of imaging integration and data management, aligning with the industry's trend toward connected surgical environments.
Beyond these core companies, recent regulatory developments highlight the dynamic nature of the market. Adagio Medical Holdings, for example, received FDA Breakthrough Device designation in April 2025 for its vCLAS cryoablation system, which utilizes ultra-low temperature cryoablation for the treatment of drug-refractory recurrent sustained monomorphic ventricular tachycardia. This designation reflects the unmet need in cardiac arrhythmia management and the potential for advanced cryoablation technologies to address complex clinical scenarios.
Regulatory Environment and Reimbursement Landscape
Navigating the regulatory and reimbursement environment is a critical aspect of market participation. In the United States, cryosurgical units and accessories, including cryoablation systems, are regulated by the FDA under 21 CFR 878.4350 as Class II devices with product code GEH. This classification requires manufacturers to demonstrate substantial equivalence to predicate devices through the 510(k) pathway or pursue more rigorous premarket approval processes for higher-risk indications. The regulatory pathway shapes product development timelines and influences the competitive dynamics, as companies with established regulatory expertise can bring innovations to market more efficiently.
Recent regulatory milestones illustrate the ongoing evolution of the sector. The ICEfx Cryoablation System received FDA 510(k) clearance in March 2024 as substantially equivalent to the Visual-ICE predicate for cryoablative destruction of tissue in general surgery, dermatology, oncology, and urology. Such clearances expand the addressable market for manufacturers and provide clinicians with additional tools for patient care. Furthermore, the absence of active product recalls for major cryoablation consoles or probes from listed manufacturers as of early 2026 suggests a maturing safety profile for these devices. Historical recalls, such as specific HealthTronics probes in 2013, have been terminated, indicating that quality management systems have improved over time.
Reimbursement remains a key enabler of market growth. Current Procedural Terminology (CPT) codes exist for cryoablation procedures in various applications, including cardiac arrhythmias and tumor ablation. These codes support hospital and outpatient utilization of systems like ProSense and ICEfx, ensuring that providers can recoup costs and maintain financial sustainability. As payers continue to evaluate the value of minimally invasive therapies, favorable reimbursement policies will likely reinforce the adoption of cryoablation systems. The alignment of clinical evidence with coding structures is therefore a strategic priority for companies seeking to expand their footprint.
Technology Trends and Future Directions
The technological evolution of surgical disguised refrigeration cryoablation systems is driven by the need for greater precision, efficiency, and integration. Refrigerant types continue to influence system design and clinical application. Argon-based systems rely on the Joule-Thomson effect to achieve rapid cooling, making them well-suited for applications requiring fast cycle times. Nitrous oxide systems, used by Medtronic and AtriCure, offer effective freezing capabilities with specific thermodynamic properties that support cardiac procedures. Liquid nitrogen systems, exemplified by IceCure's ProSense, provide the advantage of refillable dewars, eliminating the need for on-site gas lines and reducing hazardous waste concerns. These distinctions influence procurement decisions, as healthcare facilities weigh the operational implications of each technology type.
Hybrid and combination therapies represent an emerging trend. Hygea Medical Technology's co-ablation system, which pairs cryoablation with controlled heating, illustrates the potential for multimodal approaches to enhance tissue destruction while preserving adjacent structures. Such innovations may broaden the scope of treatable lesions and improve patient outcomes. Additionally, the integration of imaging compatibility, as seen with Boston Scientific's Visual ICE system, reflects the growing importance of real-time visualization during ablation procedures. As imaging technologies advance, cryoablation systems that seamlessly interface with MRI, ultrasound, or CT platforms will likely gain preference in complex clinical settings.
User interface and workflow optimization also play a role in technology differentiation. Touch-screen interfaces, automated parameter settings, and data connectivity features are becoming standard expectations rather than differentiators. Manufacturers that prioritize intuitive design and seamless integration into the surgical workflow will be better positioned to meet the needs of busy clinical environments. Furthermore, the shift toward rental and service models, as demonstrated by HealthTronics, suggests that flexibility in procurement is becoming a competitive factor, particularly for smaller institutions or those testing new technologies before committing to capital purchases.
Strategic Implications for Stakeholders in 2026 and Beyond
For manufacturers, the market signals a need for continued investment in clinical evidence generation and regulatory compliance. As indications expand and new technologies emerge, demonstrating safety and efficacy across diverse patient populations will be essential for securing reimbursement and clinician adoption. Companies should also consider strategic partnerships or acquisitions to broaden their portfolios, enhance distribution capabilities, or access complementary technologies such as advanced imaging or data analytics.
Healthcare providers and hospital administrators face decisions regarding technology adoption, inventory management, and staff training. The choice between argon-based, nitrous oxide-based, and liquid nitrogen-based systems depends on clinical priorities, facility infrastructure, and financial considerations. Evaluating total cost of ownership, including consumables, maintenance, and service support, will help institutions make informed procurement decisions. Additionally, staying abreast of regulatory updates and reimbursement changes will enable providers to optimize their surgical offerings and respond to evolving patient needs.
Investors and market analysts should monitor the convergence of technological innovation, regulatory progress, and clinical adoption as key indicators of long-term growth. The concentration of market share among leading companies suggests that scale and reputation matter, but emerging players with differentiated technologies or niche indications may present attractive opportunities. Tracking clinical trial outcomes, regulatory clearances, and reimbursement developments will provide valuable signals regarding which companies and technologies are poised to capture market share in the coming years.
Conclusion
The Worldwide Surgical Disguised Refrigeration Cryoablation System Market stands at an inflection point, propelled by technological advancement, regulatory milestones, and growing clinical acceptance. With a projected CAGR of 9.91 percent and a market trajectory moving toward 1,437.73 million USD by 2032, the sector offers substantial opportunities for those who can navigate its complexities. From the dominance of established players to the innovation of specialized firms, the competitive landscape reflects a market that is both mature and dynamic. As stakeholders prepare for the years ahead, access to comprehensive, data-driven intelligence will be indispensable for making informed strategic decisions.
For detailed analysis of this topic, please visit the official page:Worldwide Surgical Disguised Refrigeration Cryoablation System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek