
Executive Brief: The Strategic Landscape of the Worldwide Metal Dental Restoration Product Market (2026–2032)
The global dental restorative sector stands at a critical inflection point. As we move through 2026, the convergence of regulatory pressure, material science innovation, and shifting reimbursement frameworks is reshaping how manufacturers, distributors, and dental laboratories approach metal-based restorations. Our latest Worldwide Metal Dental Restoration Product Market study provides a comprehensive, data-rich roadmap for navigating this transformation. This executive brief previews the strategic intelligence embedded in the full report, designed specifically to inform enterprise decision-making in the 2026 fiscal year and beyond.
Worldwide Metal Dental Restoration Product Market
The market has demonstrated steady, resilient expansion over the past half-decade, with total revenue climbing from approximately USD 4.12 billion in 2020 to an estimated USD 5.42 billion in 2025. Looking forward, the trajectory remains upward, with projected valuations advancing through the late 2020s and reaching new thresholds by 2032. The compound annual growth rate across the full forecast horizon sits at 5.15 percent, reflecting a moderate but structurally sound expansion pace. This growth is not merely a function of population demographics or general dental utilization; it is being actively re-architected by regulatory phase-downs of mercury-containing materials, the maturation of digital workflow alternatives, and the persistent clinical demand for durable, cost-effective fixed prosthetics. Understanding where growth concentrates, which material categories are gaining or losing share, and how competitive dynamics are shifting requires the granular, scenario-tested analysis that our full report delivers.
Worldwide Metal Dental Restoration Product Market
Macro Trajectory and the 2026 Decision Context
Historical data from 2020 through 2025 reveals a market that has consistently added revenue year over year, even as regulatory headwinds and material substitution debates intensified. The pace of expansion has been measured rather than explosive, which underscores a key strategic reality: this is a mature market where incremental share shifts, product repositioning, and geographic rebalancing matter more than headline growth figures. The forecast window extending to 2032 projects continued revenue ascent, with year-over-year increments reflecting both underlying demand and the market's adaptation to mercury phase-down timelines.
Worldwide Metal Dental Restoration Product Market
For executives planning 2026 budgets, capacity allocation, and product portfolio strategies, the macro trajectory raises several questions that only a structured, segment-level breakdown can answer. Which material categories are absorbing demand as certain legacy products face phase-out schedules? How are regional revenue pools shifting in response to divergent regulatory calendars and reimbursement structures? Which application segments remain anchored by clinical necessity while others face substitution pressure from digital alternatives? The full report maps these dynamics across the entire forecast period, providing the baseline figures and growth vectors that strategy teams need to stress-test their assumptions.
Importantly, the market's concentration profile indicates a landscape where a relatively small group of players commands a meaningful share of total revenue, while a longer tail of regional manufacturers, distributors, and laboratory-focused suppliers competes on specialization, compliance readiness, and service integration. This concentration dynamic has direct implications for pricing power, channel access, and the speed at which regulatory or reimbursement changes propagate through the value chain. The report quantifies these concentration metrics and unpacks what they mean for partnership strategy, market entry timing, and competitive positioning.
Material, Application, and Regional Architecture
The market's internal architecture is defined by three primary segmentation dimensions: material type, clinical application, and geographic region. Each dimension tells a distinct story about demand durability, regulatory exposure, and strategic opportunity.
Material Type Dynamics
The material landscape splits into base metal alloys, noble metal alloys, and titanium alloys. Base metal alloys continue to serve as a volume-driving category, particularly where cost efficiency and mechanical durability are prioritized in fixed prosthetics and large-scale restorative workflows. Noble metal alloys retain a strong clinical reputation for biocompatibility and longevity, especially in porcelain-fused-to-metal frameworks and high-value cast restorations, though their revenue contribution is shaped by precious metal pricing dynamics and the gradual shift toward selective use cases. Titanium alloys occupy a specialized but strategically important position, anchored by implant-adjacent restorative applications and scenarios where corrosion resistance and osseointegration compatibility are decisive.
The strategic question for 2026 is not simply which material category is largest, but how the revenue mix is evolving as manufacturers respond to mercury phase-down mandates, as laboratories re-balance their alloy purchasing toward digital-compatible and CAD/CAM-friendly formulations, and as clinicians navigate reimbursement limitations that influence material selection at the chairside. The full report provides the segment-level revenue baselines and growth trajectories that allow product managers to model portfolio shifts with precision.
Application Segmentation
Across clinical applications, crowns and bridges represent the dominant revenue anchor, reflecting the enduring need for fixed prosthetic solutions that restore function and aesthetics. Dental implants contribute a substantial secondary stream, with restorative components and metal-framework-compatible abutments linking implant platforms to the broader metal restoration ecosystem. Inlays and onlays capture a more targeted but clinically important share, often selected for conservative tooth preparation and longevity in specific cavity configurations. A residual category encompasses specialized restorative indications that vary by region and practice type.
Application-level strategy in 2026 must account for the interplay between material choice, laboratory workflow compatibility, and reimbursement coding structures. Certain CDT coding frameworks continue to define restoration coverage by surface count and time-limited replacement rules, which influence how practitioners and payers evaluate the cost-effectiveness of different metal restoration types. The report integrates these reimbursement dynamics with application-level demand patterns to show where volume is structurally supported and where it is more sensitive to policy or coding adjustments.
Regional Distribution
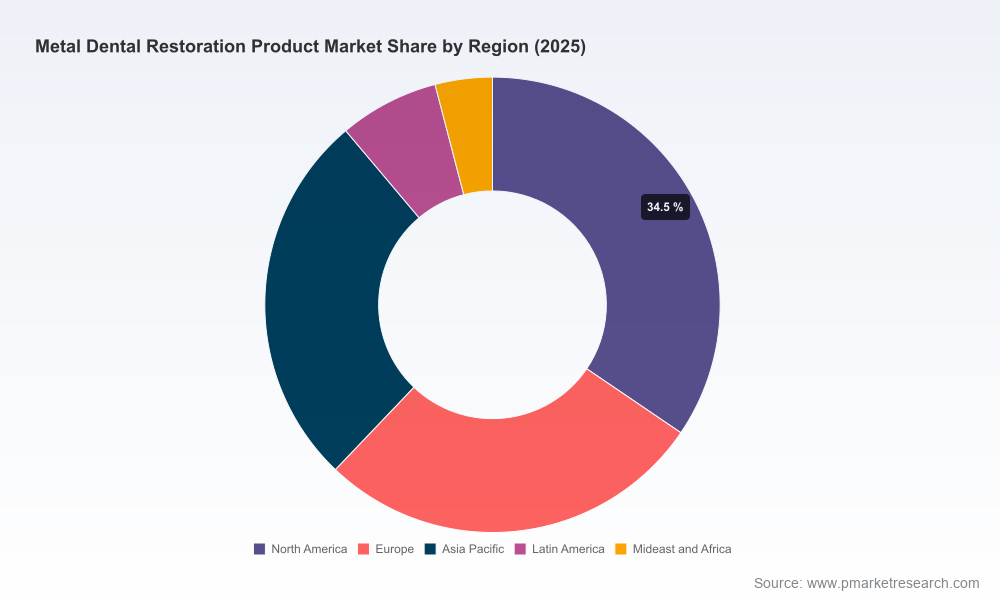
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a distinct combination of regulatory maturity, reimbursement infrastructure, laboratory capacity, and clinical preference patterns. North America and Europe reflect markets where regulatory frameworks around mercury-containing materials are advancing most rapidly, influencing both product availability and manufacturer compliance strategies. Asia Pacific represents a region of significant volume potential, shaped by growing dental utilization, expanding laboratory networks, and a mix of cost-sensitive and premium restorative demand. Latin America and the Middle East and Africa contribute smaller but strategically relevant revenue pools, often characterized by different import dynamics, distributor relationships, and price-point considerations.
The report's regional analysis avoids simplistic rankings and instead focuses on how revenue pools are distributed, how growth rates differ by region, and what that implies for market entry, distribution partnerships, and regulatory compliance investment. Detailed regional figures and share breakdowns are provided in the full study to support geographic resource allocation decisions.
Regulatory and Reimbursement Currents Reshaping the Market
Regulatory developments are no longer peripheral concerns; they are central drivers of product roadmaps, supply chain decisions, and competitive positioning. The revised EU Mercury Regulation has already prompted multiple manufacturers to cease amalgam exports outside the EU from early 2025, while others have stopped production entirely or announced phase-out schedules extending into 2027. These actions are part of a broader global phase-down trajectory aligned with the Minamata Convention's targeted phase-out timeline toward 2034, which is steadily narrowing the permissible use cases for mercury-containing dental amalgam.
In the United States, the FDA continues to classify dental amalgam as Class II with special controls, but a 2025 petition has sought reclassification to Class III or a full ban based on mercury exposure risk arguments. The outcome of such regulatory reviews will influence product availability, labeling requirements, and clinician perception, particularly in markets where amalgam has historically been a high-volume, low-cost restorative option. Meanwhile, institutional policies such as the Indian Health Service's announced phase-out of mercury-containing amalgam in its facilities by 2027 illustrate how public-sector procurement decisions can accelerate material substitution even before broader regulatory mandates take effect.
Reimbursement frameworks add another layer of strategic complexity. CDT coding structures continue to define amalgam restoration coverage by surface count, with limits such as one restoration per tooth surface per twelve-month period. These coding constraints influence the economic calculus for both practitioners and patients, shaping demand for alternative metal restorations and mercury-free materials. For manufacturers and distributors, understanding how reimbursement codes interact with material pricing, laboratory costs, and clinical indications is essential for accurate market sizing and sales forecasting.
The full report synthesizes these regulatory and reimbursement currents into a coherent dynamics section, mapping how policy timelines, compliance requirements, and coding structures are likely to affect demand, product mix, and competitive behavior across the forecast period.
Competitive Landscape: Established Players and Strategic Shifts
The competitive field in metal dental restoration products is characterized by a mix of global manufacturers, regional specialists, distributors, and laboratory-focused suppliers. Several companies stand out for their scale, product breadth, and strategic positioning as the market adapts to regulatory and technological change.
Southern Dental Industries, headquartered in Australia, remains a globally recognized leader in dental amalgam production, with established product lines and worldwide capsule distribution. Its strategy reflects a dual trajectory: maintaining amalgam offerings in markets where they remain permitted while actively transitioning toward mercury-free alternatives. This balanced approach illustrates how incumbent players are managing regulatory risk without abruptly abandoning volume-serving product lines. Silmet Dental, based in Israel, and Nordiska Dental, from Sweden, both operate as manufacturers of dental amalgam alloys and metal restorative alloys for crowns, bridges, and fillings, supplying global distributors and regional laboratories. Wykle Research, in the United States, focuses on dental amalgam products for restorative applications, representing the U.S.-based manufacturing segment that navigates evolving regulatory expectations while serving domestic demand.
On the casting alloys and precious metal side, Cookson Industrial, operating from the United Kingdom, supplies dental casting alloys, amalgam, and precious metal solders for crowns, bridges, and prosthetic metal restorations, with compliance aligned to MDR requirements. Henry Schein, in the United States, functions as a major distributor of dental alloys and amalgam from leading manufacturers, offering metal restoration products that meet recognized quality standards. Dentsply Sirona, also U.S.-based, offers metal restorative materials including alloys for porcelain-fused-to-metal restorations and has historically maintained amalgam lines in certain regions while phasing out others. Ivoclar Vivadent, headquartered in Liechtenstein, produces Valiant amalgam alongside metal alloys for cast restorations and PFM frameworks; notably, the company stopped worldwide production of dental amalgam in October 2025 and plans to discontinue marketing and sales of its Valiant amalgam line by the end of the first quarter of 2027, a move that signals the accelerating pace of phase-out decisions among major manufacturers.
3M Company, in the United States, supplies metal restorative materials and alloys used in dental crowns, bridges, and indirect restorations, maintaining a presence across multiple restorative categories. GC Corporation, from Japan, provides dental alloys and metal-based restorative products for fixed prosthetics, supporting both regional and international demand. Heraeus Kulzer, based in Germany, manufactures dental alloys for PFM and cast metal restorations, contributing to the European and global supply of high-performance alloy options. Glidewell Dental, a U.S.-based dental laboratory, produces Obsidian fused to metal and full-cast gold restorations alongside PFM options, illustrating how laboratory manufacturers are integrating material expertise with digital workflow capabilities. Continental Dental Laboratories, also U.S.-based, specializes in PFM crowns using high noble, semi-precious, and non-precious alloys, reflecting the continuing relevance of alloy selection in laboratory-driven restorative production.
Recent developments underscore how quickly strategic postures are evolving. In addition to Ivoclar's production stop and phased marketing discontinuation, Cavex Holland announced the discontinuation of dental amalgam exports outside the EU effective January 1, 2025, driven by revised EU Mercury Regulation requirements. On the technology substitution front, 3D Systems released a fully cleared denture solution using its NextDent 300 printer in mid-2025, supporting digital metal-alternative workflows for restorations and signaling how additive manufacturing and digital materials are expanding the competitive perimeter. Straumann, through its Neodent division, released a 2025 product catalog featuring updated implant packaging and an e-IFU platform, including restorative components compatible with metal frameworks, highlighting how implant-restorative integration continues to create cross-category demand.
The competitive analysis in the full report goes beyond company profiles to examine positioning strategies, compliance readiness, channel relationships, and the ways in which phase-out timelines and digital substitution are reshaping share dynamics. For executives evaluating partnerships, acquisitions, or competitive responses, these insights provide the context needed to anticipate where advantage will be created in 2026 and beyond.
What the Full Study Delivers for 2026 Strategy
This market research is built to translate complex, interlinked trends into actionable intelligence. The complete study provides a structured, multi-dimensional view of the worldwide metal dental restoration product market, enabling strategy teams to move from high-level awareness to precise planning.
Within the report, readers will find:
- A full historical revenue series from 2020 through the base year, establishing a verified baseline for trend analysis and scenario modeling.
- A detailed forecast trajectory extending through the end of the forecast period, with year-by-year revenue projections that reflect regulatory phase-down pacing, material substitution patterns, and regional growth differentials.
- Segment-level revenue breakdowns by material type, clinical application, and region, enabling portfolio benchmarking, target segment evaluation, and geographic resource allocation.
- Market concentration metrics that clarify the balance between leading players and the broader supplier base, supporting competitive positioning and partnership strategy.
- A dedicated dynamics section that integrates regulatory timelines, reimbursement coding structures, compliance requirements, and technology substitution trends into a cohesive view of market drivers and constraints.
- Company profiles and recent development tracking for key manufacturers, distributors, and laboratory suppliers, with attention to phase-out decisions, product launches, regulatory clearances, and catalog updates that signal shifting strategic priorities.
- Practical guidance on how to interpret the data for product roadmap planning, distribution strategy, compliance investment, and market entry or expansion decisions.
The report is designed for executives, product leaders, commercial strategy teams, and market intelligence professionals who need more than headline figures. It provides the depth required to assess where growth is structurally supported, where regulatory and reimbursement factors are reallocating demand, and where competitive advantage will be won through compliance readiness, material innovation, and workflow integration.
How to Use This Intelligence in 2026 Planning
For organizations operating in or adjacent to the metal dental restoration market, the 2026 planning cycle benefits from a clear-eyed view of both continuity and change. The market is not collapsing; it is restructuring. Mercury-containing products are being narrowed by regulation and institutional policy, but the underlying demand for durable, affordable fixed prosthetics remains robust. Material categories are being re-weighted as manufacturers and laboratories adapt to phase-down timelines and digital workflow expectations. Regional revenue pools are shifting at different speeds, creating opportunities for those who can align compliance, distribution, and pricing strategies with local regulatory calendars and reimbursement realities.
The strategic actions that matter most in 2026 include portfolio re-balancing across material types, anticipating phase-out milestones for legacy products, assessing where mercury-free or low-mercury alternatives can capture share without sacrificing clinical acceptability, and evaluating digital workflow compatibility as a competitive differentiator in laboratory and restorative supply chains. Distribution and partnership strategies also require re-examination, particularly in regions where export restrictions, regulatory reclassification debates, and reimbursement coding constraints are altering the economics of specific product categories.
The full report provides the data foundation and analytical structure to support these decisions. Segment baselines, forecast trajectories, concentration metrics, and competitive profiles are all integrated to help teams build scenarios, test assumptions, and prioritize investments with confidence.
Next Steps
This executive brief has outlined the strategic contours of the worldwide metal dental restoration product market and previewed the analytical depth available in the complete study. To access the full historical series, forecast detail, segment-level revenue breakdowns, concentration analysis, regulatory and reimbursement integration, and comprehensive company profiles, please visit the source page for the Worldwide Metal Dental Restoration Product Market research. The complete report is structured to serve as a working reference for 2026 strategy development, enabling your team to move from market awareness to precise, data-informed action.
For detailed analysis of this topic, please visit the official page:Worldwide Metal Dental Restoration Product Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek