
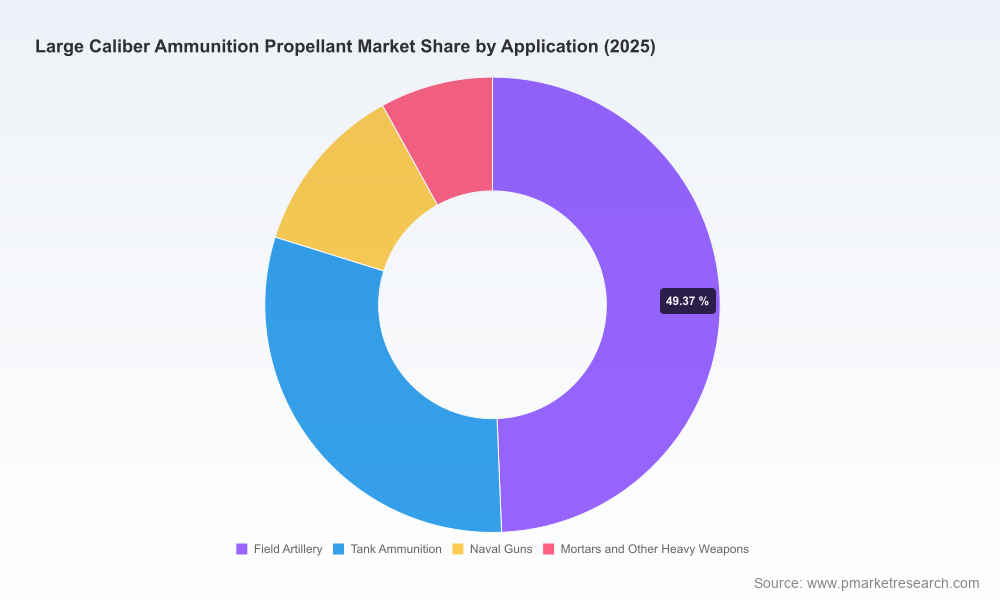
**The Strategic Imperative: Navigating the Large Caliber Ammunition Propellant Market Through 2032** The global defense industry stands at a pivotal inflection point. Geopolitical tensions, accelerated modernization programs, and the urgent need for sustained firepower dominance have transformed large caliber ammunition propellant from a commodity input into a critical strategic enabler. For executives and decision-makers charting corporate strategy through 2026 and beyond, understanding the nuances of this specialized market is no longer optional — it is foundational to maintaining competitive advantage, securing supply chains, and capitalizing on multi-year growth opportunities. Recent market analysis reveals a robust expansion trajectory. The Large Caliber Ammunition Propellant Market, valued at approximately USD 4.55 billion in 2025, is projected to grow at a compound annual growth rate of 6.78% through the forecast period ending in 2032. This sustained momentum reflects the convergence of rising global defense budgets, the resurgence of conventional artillery in peer-state conflict scenarios, and technological upgrades across land and naval platforms. What distinguishes this market, however, is not merely its size but the complex interplay of technological innovation, regulatory pressure, raw material dependencies, and concentrated industrial capabilities that define its competitive landscape. **Understanding the Underlying Market Dynamics** The demand for large caliber propellants is inextricably linked to the evolving character of modern warfare. Recent conflicts have demonstrated the enduring relevance of indirect fire systems, with massed artillery barrages and precision-guided munitions playing decisive roles. This reality has prompted nations across NATO, the Indo-Pacific, and the Middle East to reassess stockpiles and accelerate replenishment programs. Consequently, both legacy platforms and next-generation systems require advanced propellant solutions that deliver higher energy, reduced barrel erosion, improved temperature stability, and enhanced safety characteristics. Regulatory and environmental considerations are reshaping formulation strategies. The drive toward REACH-compliant formulations and the development of propellants with reduced toxic signatures have become competitive differentiators. Notably, leading manufacturers are actively pursuing propellant chemistries that minimize or eliminate traditional dependencies on nitrocellulose and nitroglycerine. These innovations promise not only environmental benefits but also improved supply chain resilience by reducing vulnerability to upstream chemical feedstock disruptions. Supply chain vulnerabilities have emerged as a central concern for defense primes and government customers alike. Reliance on single-source or foreign-sourced critical energetics has been identified as a strategic risk, particularly in long-range artillery applications. This has spurred investment in domestic production capacity and the qualification of alternative suppliers — trends that are expected to intensify through 2026 and create both challenges and opportunities for established players and agile newcomers. **Segment Overview and Application Landscape** The Large Caliber Ammunition Propellant Market encompasses a range of propellant technologies, each optimized for specific performance requirements. Single-base, double-base, triple-base, and advanced composite formulations including LOVA (Low Vulnerability Ammunition) propellants serve distinct roles across the application spectrum. These technologies are critical for field artillery systems, main battle tank ammunition, naval gun systems, mortars, and other heavy weapons platforms. From a strategic perspective, the market’s application split underscores the primacy of ground-based artillery and armored warfare capabilities. Naval modernization programs, while smaller in volume, are increasingly demanding high-energy, low-erosion propellants capable of supporting extended-range precision fires from surface combatants. The technical requirements across these segments continue to evolve, driving R&D investment in burn rate modifiers, energetic plasticizers, and advanced grain geometries. **Competitive Landscape: Concentration and Capability** The competitive environment is characterized by significant market concentration. The top three players account for nearly half the global market, while the top five control approximately two-thirds, reflecting the enormous barriers to entry, stringent qualification requirements, and the strategic sensitivity of propellant manufacturing. **General Dynamics Ordnance and Tactical Systems (St. Marks Powder)** remains a cornerstone supplier, particularly through its proprietary BALL POWDER® technology. The company’s portfolio spans mortar systems and offers high-density propelling charges (HDPC) alongside REACH-compliant formulations, positioning it strongly in both U.S. and allied markets. **American Rheinmetall Munitions**, leveraging the propellant expertise of Nitrochemie, has positioned itself as a key advocate for advanced energetics. Its ECL® (Extruded Composite Low-sensitivity) and EI® (Extruded Increments) technologies, combined with extended shelf-life formulations, directly address identified gaps in the U.S. industrial base for long-range artillery propellants. Recent advocacy efforts highlight the company’s strategic intent to reduce American dependence on non-domestic sources. **BAE Systems**, through its operation of the Radford Army Ammunition Plant, maintains a commanding position in nitrocellulose-based single- and double-base propellant production. The company’s April 2025 announcement regarding synthetic propellant formulations represents a potential paradigm shift. By developing manufacturing processes that eliminate nitrocellulose and nitroglycerine dependency across calibers from small arms to large caliber systems, BAE is targeting first industrial production by the end of 2026 following substantial investment in UK facilities. This development could significantly alter the raw material risk profile for the entire industry. **EURENCO** has moved decisively to strengthen European strategic autonomy. The French company’s 2025 capacity expansion for large-caliber propellants, coupled with the relocation of key operations to France, reflects broader European efforts to reduce external dependencies and bolster defense industrial sovereignty. Other significant participants include **Nitrochemie** (the Rheinmetall/RUAG joint venture), renowned for its high-caloric triple-base and double-base propellants optimized for 100–155mm systems with low barrel erosion characteristics; **Northrop Grumman**, with deep expertise in 105mm and 120mm tank ammunition; **Day & Zimmermann**, a specialist in propellant charge bags and MACS igniter systems; **Brixtel Defense**; and **American Ordnance LLC**, which brings extensive load, assemble, and pack (LAP) experience for medium and large caliber munitions. This concentration creates both stability and vulnerability. While established players possess deep technical knowledge, qualified manufacturing processes, and long-term government contracts, the limited supplier base amplifies the impact of any single point of failure — whether from regulatory action, raw material shortages, or capacity constraints. **Strategic Value of the 2026 Market Intelligence** For corporate strategists, business development leaders, and investment professionals, the forthcoming PW Consulting Large Caliber Ammunition Propellant Market research delivers actionable intelligence calibrated precisely for 2026 decision cycles. The report provides a comprehensive evaluation of market sizing and growth projections built on detailed modeling of defense spending trends, platform procurement forecasts, and propellant consumption rates across major military powers. More importantly, it translates these macro trends into granular, application-specific insights that enable precise targeting of growth pockets without exposing readers to the full dataset in this overview. Competitive benchmarking forms a core component of the analysis. Beyond public profiles, the research delivers nuanced assessment of each major player’s technology roadmaps, manufacturing capacity expansion plans, qualification status with key customers, and strategic positioning regarding next-generation propellant chemistries. Special attention is given to how recent developments — from BAE’s synthetic propellant breakthrough to American Rheinmetall’s advocacy for domestic energetics production and EURENCO’s European capacity build-out — are likely to reshape competitive dynamics through the latter half of the decade. The study further examines supply chain architecture, identifying critical nodes of vulnerability and emerging opportunities for vertical integration or strategic partnering. Raw material dynamics, particularly around nitrocellulose and alternative energetic materials, receive focused treatment, equipping readers to anticipate potential disruptions and formulate appropriate risk mitigation strategies. Technology and innovation trends are analyzed through a strategic lens. The research evaluates the commercial readiness of low-vulnerability, reduced-erosion, and environmentally optimized propellant formulations, while assessing the probability and timeline of disruptive shifts such as fully synthetic propellants moving from demonstration to series production. Regional dynamics are explored with emphasis on how differing threat perceptions, industrial policies, and alliance structures are driving divergent demand patterns and localization requirements. This analysis proves particularly valuable for companies navigating export controls, offset obligations, andfriend-shoring initiatives. **Conclusion: From Intelligence to Decisive Action** The Large Caliber Ammunition Propellant Market in 2026 represents far more than a niche defense subsector. It embodies the convergence of traditional industrial base challenges with cutting-edge materials science, regulatory evolution, and great-power competition. Organizations that treat propellant supply as a purely tactical procurement matter risk strategic disadvantage. Those that approach it with sophisticated, data-driven insight will be better positioned to secure long-term contracts, guide R&D investment, optimize manufacturing footprints, and identify attractive M&A or partnership opportunities. This market study has been deliberately structured to provide both immediate strategic context and a clear pathway to deeper intelligence. While this introduction highlights the scale, direction, and competitive dynamics shaping the industry, the complete research contains the detailed segmentation breakdowns, company-specific financial and operational metrics, scenario modeling, and forward-looking recommendations necessary for high-stakes decision making. Decision-makers seeking to transform this market intelligence into tangible competitive advantage are encouraged to access the full PW Consulting Large Caliber Ammunition Propellant Market report. In an environment where margins for error continue to narrow and technological cycles accelerate, timely and authoritative intelligence is not merely helpful — it is a decisive strategic asset. (Word count: 1,378)
For detailed analysis of this topic, please visit the official page:Large Caliber Ammunition Propellant Market
Large Caliber Ammunition Propellant Market
Large Caliber Ammunition Propellant Market
Large Caliber Ammunition Propellant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek