
Strategic Foresight: Navigating the Global Textile Staples Market in 2026 and Beyond
The Imperative for Strategic Realignment
The global textile industry stands at a critical inflection point. As we move through 2026, supply chain resilience, sustainability mandates, and rapid shifts in consumer demand are reshaping the foundational landscape of textile staples. For executives, procurement leaders, and investors, the margin for error has never been narrower. Understanding the trajectory of staple fibers is no longer merely an operational concern; it is a core strategic necessity that dictates competitive advantage in apparel, home furnishing, and technical applications.
Worldwide Textile Staples Market
PW Consulting is pleased to introduce our latest comprehensive study: The Worldwide Textile Staples Market Research. This report is designed to cut through the noise of daily commodity fluctuations and provide a robust, data-driven framework for decision-making over the next half-decade. By analyzing historical performance from 2020 through 2025 and projecting forward to 2032, this study offers the clarity needed to navigate an increasingly complex market environment.
Worldwide Textile Staples Market
The textile staples sector is characterized by its cyclical nature, sensitivity to raw material costs, and growing regulatory pressure regarding environmental impact. Companies that fail to anticipate these shifts risk supply disruptions, margin compression, and reputational damage. Conversely, those who leverage accurate market intelligence can optimize inventory strategies, identify high-growth segments, and align their portfolios with emerging sustainability standards. This report serves as the compass for that journey.
Worldwide Textile Staples Market
Market Trajectory and Growth Dynamics
Our analysis reveals a market defined by steady expansion and significant value creation. The global demand for textile staples has demonstrated resilience despite geopolitical tensions and economic volatility. Starting from a baseline of approximately 132.45 billion USD in 2020, the market has shown consistent upward momentum. By 2025, the revenue scale reached 170.16 billion USD, reflecting a compound annual growth rate that underscores the sector's fundamental health.
Looking ahead, the forecast period from 2026 to 2032 indicates continued growth, projected at a CAGR of 5.01 percent. This trajectory suggests that the market will expand from 177.04 billion USD in 2026 to nearly 239.43 billion USD by 2032. Such growth is not uniform across all segments or geographies. It is driven by specific structural factors, including the rise of fast fashion in emerging economies, the demand for high-performance technical textiles, and the global transition toward recycled and sustainable fiber solutions.
Understanding the magnitude of this opportunity requires more than headline numbers. It demands a granular understanding of how value is distributed across product types, application sectors, and regional boundaries. Our report dissects these variables to reveal where the highest value creation is occurring and where future bottlenecks may emerge. For instance, while the total market size provides a macro view, the strategic insight lies in understanding the interplay between supply constraints in key manufacturing hubs and demand surges in specific consumer segments.
Segmentation Dynamics: Type, Application, and Region
The market is composed of diverse material categories, each with distinct cost structures, performance characteristics, and end-user demands. Our research provides a detailed breakdown of these segments without overwhelming stakeholders with unnecessary noise. The primary material categories include polyester staple fiber, cotton staple, viscose and rayon staple, nylon staple, and other specialized staples. Among these, polyester remains a dominant force due to its versatility and cost efficiency, while cellulosic fibers like viscose and rayon are gaining traction driven by sustainability narratives.
In terms of application, the market serves a wide array of industries. The apparel sector remains the largest consumer of textile staples, reflecting the global demand for clothing and fashion items. However, significant growth is also observed in home furnishing, where softness and durability are paramount. Furthermore, the technical textiles sector is expanding rapidly, utilizing staples for automotive components, filtration systems, and insulation materials. This diversification is critical for risk management; companies overly reliant on a single application segment face greater exposure to sector-specific downturns.
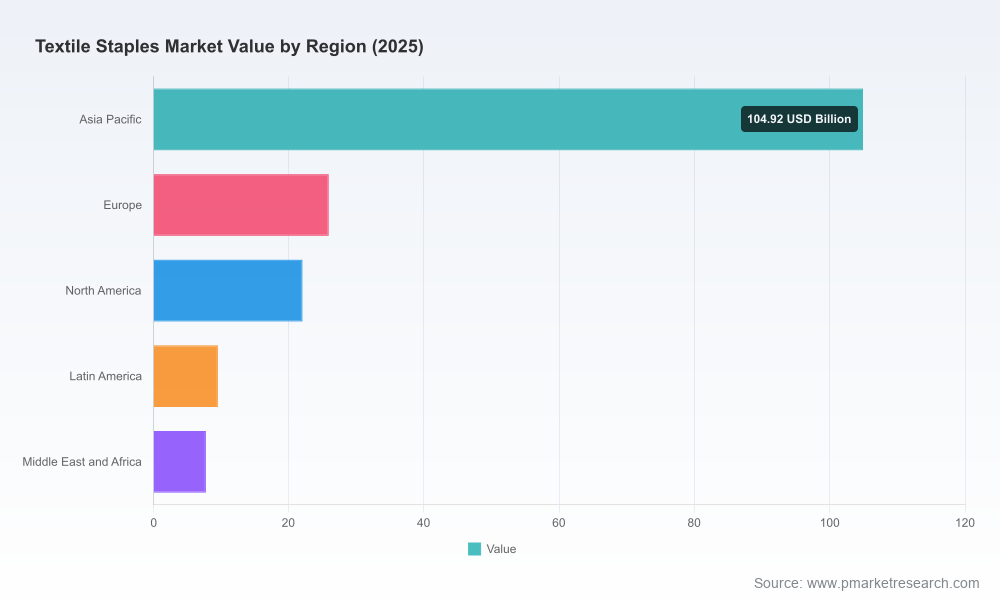
Regional dynamics further complicate the landscape. The Asia Pacific region continues to hold a substantial share of global production and consumption, driven by robust manufacturing infrastructure and large domestic populations. Europe and North America represent mature markets with a stronger focus on premium, sustainable, and specialized fiber solutions. Meanwhile, Latin America and the Middle East and Africa are emerging as important nodes in both supply and demand, influenced by developing industrial capabilities and shifting trade flows. Our report analyzes these regional nuances to help clients identify the right markets for expansion or sourcing optimization.
Crucially, we examine market concentration to understand competitive density. The data indicates a moderately fragmented landscape where no single entity dominates the entire value chain. This structure creates opportunities for strategic partnerships and niche specialization. By understanding the concentration levels, firms can better assess the bargaining power of suppliers and the competitive intensity they might face in specific regions or segments.
Competitive Landscape and Strategic Positioning
The playing field for textile staples is contested by a mix of global conglomerates and specialized producers. Our report profiles key companies that are shaping the industry through capacity expansions, technological innovations, and sustainability initiatives. These players range from major integrated petrochemical groups to specialty fiber manufacturers focused on high-performance applications.
Leading the pack are entities such as Indorama Ventures Public Company Limited, Reliance Industries Limited, and Toray Industries Inc. These companies leverage massive scale and integrated upstream operations to maintain competitive pricing and supply reliability. Indorama Ventures, headquartered in Bangkok, remains a major global producer of polyester staple fiber, with significant capacity in Asia and integrated operations covering apparel, home textiles, and nonwovens. Similarly, Reliance Industries, based in Mumbai, stands as a leading integrated polyester producer supplying both virgin and recycled PSF for diverse textile applications.
In the specialty and sustainability segment, companies like Lenzing AG, Grasim Industries Limited, and Teijin Frontier Co., Ltd. are pivotal. Lenzing, based in Austria, is recognized as a premier producer of cellulosic viscose staple fibers, offering premium sustainable solutions from wood pulp. Grasim Industries, part of the Aditya Birla Group, is a key manufacturer of viscose staple fiber supplying the global industry for blended yarns and fabrics. Teijin Frontier focuses on specialty synthetic staple fibers, including polyester for technical textiles, automotive, and performance apparel.
Other significant players include Alpek S.A.B. de C.V., which produces polyester staple fiber through integrated PTA/PET operations serving North American and international markets; Far Eastern New Century (FENC), a significant Asian producer including recycled grades; and W. Barnet GmbH & Co. KG, specializing in synthetic staple fibers for nonwovens and technical applications. Additionally, large-scale Chinese producers like Sinopec Yizheng Chemical Fibre Company and Korean manufacturer Huvis Corporation play crucial roles in global supply chains.
Strategic moves by these companies define the market rhythm. In May 2025, Indorama Ventures expanded its dejaTM fiber and filament yarn portfolio to enhance sustainability offerings in recycled polyester staple fibers. In October 2025, Teijin Frontier launched THERMOFRONT, a new master brand for sheet insulation combining environmental responsibility with high thermal performance using specialty staple fibers. More recently, in February 2026, Aksa Akrilik Kimya Sanayii A.S. commissioned an expanded production line adding 30,000 MT annual acrylic staple fiber capacity with advanced solvent recovery and energy efficiency upgrades for technical textiles. In January 2026, Pasupati Acrylon Limited announced capacity expansion at its Samba manufacturing facility in India for increased acrylic staple fiber supply to domestic yarn spinning and knitwear clusters.
Raw Material Dynamics and Supply Chain Vulnerabilities
Profitability in the textile staples market is inextricably linked to raw material costs. The price volatility of feedstocks such as PTA and MEG, key upstream inputs for polyester, creates a volatile cost environment for manufacturers. In March 2026, PTA and MEG prices in India experienced sharp fluctuations, rising then partially correcting by Rs. 14-20 per kg. Such volatility requires agile procurement strategies and hedging mechanisms to protect margins.
Downstream price pressures are equally significant. Domestic Chinese polyester staple fiber (1.4D*38mm) average market price reached 8,160 RMB/ton as of March 20, 2026, marking a 23.44 percent increase from the start of the month due to upstream PTA cost surges. Meanwhile, polyester staple fiber prices in China rose slightly to 8263 CNY per ton since mid-April 2026, supported by favorable upstream cost factors. These regional price displacements highlight the importance of geographic diversification in sourcing strategies.
Viscose staple fibre prices also reflect tight supply conditions. In February 2026, prices were recorded at 1848/MT in China and 1941/MT in India, influenced by tight supply and low inventories. Such data points underscore the need for real-time visibility into supply chain constraints. Our report aggregates these market signals to provide a holistic view of cost pressures, enabling clients to anticipate price movements and adjust their procurement schedules accordingly.
Regulatory Pressures and the Sustainability Shift
Beyond economics, the regulatory environment is becoming a primary driver of market structure. Sustainability mandates in North America and Europe continue to favor closed-loop and low-emission viscose staple fiber technologies amid broader textile environmental regulations. Compliance is no longer optional; it is a license to operate in premium markets.
This shift impacts material selection across the value chain. Companies are increasingly pressured to reduce carbon footprints, minimize waste, and utilize recycled content. The rise of recycled polyester staple fibers, as seen in recent portfolio expansions by major players, is a direct response to these pressures. However, navigating the complex web of certifications, standards, and reporting requirements demands specialized knowledge. Our research outlines the regulatory landscape, helping firms understand where the compliance risks lie and how they can turn sustainability into a competitive differentiator rather than a cost burden.
The intersection of regulation and technology is also creating new opportunities. Advanced solvent recovery systems, energy efficiency upgrades, and new master brands focused on environmental responsibility are becoming standard expectations for leading manufacturers. Firms that invest in these areas early will be better positioned to meet future standards and capture the growing segment of eco-conscious consumers and business buyers.
Actionable Intelligence for 2026 and Beyond
The value of this research lies in its applicability. We do not merely present data; we contextualize it for strategic action. The report includes detailed profiles of key companies, allowing readers to benchmark their own capabilities against industry leaders. It provides an analysis of recent capacity expansions and product launches, offering signals about where competitors are directing their capital and innovation resources.
Our segmentation analysis helps identify white spaces for growth. Whether a company is looking to enter a new geographic market, launch a specialized product line, or optimize its current supply chain, the granular data within this study supports evidence-based decision-making. The forecast models are constructed to account for various scenarios, ensuring that strategic plans are robust against potential disruptions.
Furthermore, the report addresses the operational realities of the market. By integrating recent price trends and raw material fluctuations, we provide a realistic view of the cost environment. This allows procurement managers to set realistic budgets and negotiating positions. For investors, the market concentration and growth rate data offer a clear picture of the sector's investment potential and risk profile.
In a market as dynamic as the Worldwide Textile Staples Market, information is the ultimate asset. The ability to distinguish between temporary noise and structural trends is what separates successful organizations from those that struggle to adapt. This report is designed to enhance that ability, providing the depth and breadth of insight required to navigate the complexities of 2026 and the forecasted years ahead.
We invite industry leaders, strategic planners, and market analysts to explore the full findings of this study. The complete data sets, detailed company profiles, and comprehensive forecast models are available to provide the precise intelligence needed to secure a competitive edge. Understanding the full scope of the market is the first step toward mastering it.
For detailed analysis of this topic, please visit the official page:Worldwide Textile Staples Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Portuguese (Brazil)
 Greek