
Global Exhibition Stand Market Strategic Outlook 2026: Navigating Growth, Complexity, and Experience Economy
The physical exhibition floor has evolved from a transactional space for lead generation into a sophisticated arena for brand storytelling, relationship building, and experiential commerce. As enterprises plan their 2026 capital allocation and go-to-market strategies, the worldwide exhibition stand market has emerged as a critical lens through which to evaluate brand visibility, customer engagement, and operational resilience. PW Consulting’s newly released Worldwide Exhibition Stand Market research provides decision-makers with a structured, data-driven roadmap to navigate this shifting landscape. This overview outlines the strategic value of the report, previews its core analytical dimensions, and clarifies why a disciplined, evidence-based approach to exhibition stand investment will separate market leaders from reactive followers in the years ahead.
Worldwide Exhibition Stand Market
Why 2026 Demands a New Strategic Lens
For executive teams and event marketing leaders, 2026 is not merely another planning cycle. It is a convergence point where post-pandemic exhibition volumes have stabilized, macroeconomic uncertainty continues to pressure discretionary spend, and attendee expectations for immersive, digitally integrated, and sustainably responsible experiences have reset the baseline for what a booth must deliver. Companies that treat exhibition stands as tactical line items risk underinvesting in high-ROI activations or overspending on poorly differentiated assets. Those that approach the market with rigorous segmentation, cost-structure clarity, and competitive benchmarking can unlock disproportionate share of voice, accelerate pipeline velocity, and strengthen brand equity across multiple verticals.
Worldwide Exhibition Stand Market
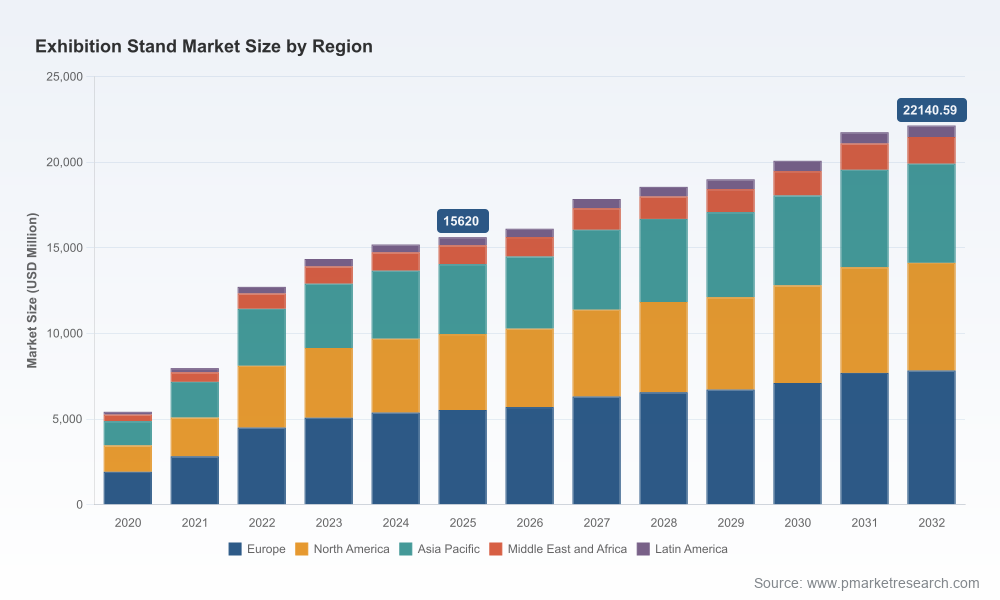
The global market trajectory reflects both resilience and disciplined growth. Following a period of rapid expansion from 2020 through 2025, the worldwide exhibition stand market has entered a phase of measured, compounding growth projected to extend through 2032. This forward base makes 2026 an inflection year for strategic planning: early movers who calibrate their stand strategies now can lock in supply-chain advantages, secure preferred contractor partnerships, and shape category standards before pricing and capacity pressures intensify. The research equips leaders to distinguish between cyclical noise and structural opportunity, ensuring that budget allocation, vendor selection, and design prioritization are anchored in evidence rather than convention.
Worldwide Exhibition Stand Market
Market Trajectory: From Recovery to Structural Growth
A disciplined reading of the macroeconomic picture is essential for 2026 planning. The data series reveals a pronounced acceleration phase between 2020 and 2025, after which the market enters a sustained expansion path. By anchoring planning assumptions to a forward-looking compound annual growth rate of approximately 5.11 percent through 2032, executive teams can model revenue scenarios, capacity planning, and capital deployment with greater confidence. Importantly, the growth is not uniform across all customer segments or geographies, which is precisely why the report prioritizes segmentation clarity over headline numbers.
Strategic leaders should note three structural implications embedded in the trajectory. First, the maturing expansion phase suggests that standalone volume growth will increasingly depend on value-added services, experiential differentiation, and repeat exhibitor loyalty rather than market tailwinds alone. Second, the progression toward a more concentrated but still fragmented supplier landscape creates both procurement leverage and execution risk; companies must balance consolidation for efficiency against diversification for resilience. Third, the upward curve through the end of the decade signals that exhibition infrastructure will remain a contested resource, reinforcing the need for early booking, standardized modular capabilities, and clear total-cost-of-ownership modeling.
What This Means for Capital Planning
For CFOs and marketing operations directors, the planning environment of 2026 calls for a shift from episodic budget approvals to program-level investment frameworks. That means treating exhibition stands as multi-year assets with defined lifecycle costs, measuring contribution not only to booth traffic but to qualified pipeline, partnership origination, and brand lift. The research supports this transition by mapping market size progression, growth velocity, and category dynamics into actionable planning assumptions that can be folded into annual operating plans and multi-year brand roadmaps.
Segmentation Logic: Designing Strategy Around Stand Types, Verticals, and Regional Realities
One of the most valuable contributions of the report is its structured segmentation architecture. Rather than presenting an undifferentiated market, the analysis disentangles the stand ecosystem into type-based categories, industry-vertical demand patterns, and regional dynamics. For strategists, this segmentation is the bridge between abstract growth figures and concrete allocation decisions. It reveals where customization premium is sustainable, where modular and portable systems deliver speed and cost advantages, and where specific vertical sectors are intensifying their demand for engineered, compliant, and reusable stand solutions.
Stand-type segmentation matters because each category carries distinct cost profiles, deployment timelines, and brand-expression capabilities. Custom exhibition structures enable highly differentiated brand environments but require longer lead times, specialized fabrication, and iterative approvals. Modular systems offer repeatability, faster assembly, and inventory flexibility, which becomes increasingly valuable as event calendars compress and travel logistics remain sensitive. Portable displays and compact configurations address the needs of agile teams, pop-up activations, and space-constrained venues. Double-decker stand concepts introduce vertical density and visibility optimization for high-traffic halls. The report evaluates how these categories compete, complement, and cannibalize each other across exhibitor segments, helping teams match form factor to strategic intent rather than defaulting to legacy preferences.
Industry-vertical segmentation is equally critical for prioritization. Different sectors bring different procurement cycles, compliance requirements, technical integration needs, and brand-audience expectations. Technology and electronics exhibitors often emphasize interactive demos, data capture, and rapid iteration. Automotive and aerospace participants require high-impact structural presence, large-scale visuals, and engineering-grade build quality. Healthcare and pharmaceutical exhibitors navigate stringent regulatory environments, data-privacy considerations, and controlled messaging standards. Consumer goods and retail brands lean toward experiential storytelling, product tactile engagement, and social-media-generating moments. Industrial and manufacturing companies prioritize durability, repeatability, and operational clarity. By mapping these vertical dynamics against market size and growth contribution, the research helps brand teams and event managers align stand investment with the practical realities of their audience, compliance posture, and sales cycle.
Regional Layering Without Overgeneralization
Geography shapes everything from venue availability and labor dynamics to material logistics and cultural expectations for booth experience. The report provides a regional framework that supports deliberate geographic prioritization rather than blanket international rollouts. For global enterprises, this means deciding where to standardize versus localize, which markets warrant full custom build-outs, and where modular inventory can be pre-positioned to reduce cost and lead time. For regional players, it clarifies where competitive intensity is rising and where white space for differentiated service models remains underexplored. The macro-level regional mapping in the report is designed to inform allocation strategy while preserving the confidentiality of the granular figures that would otherwise enable reverse engineering of sensitive revenue splits.
Competitive Landscape: Benchmarking Capability, Scale, and Execution Models
The exhibition stand supplier market is characterized by a mix of full-service global providers, regionally entrenched builders, modular-system specialists, and experiential marketing organizations that blur the line between stand construction and brand activation. The report profiles a representative set of leading players to help procurement teams, event directors, and strategy leaders understand the spectrum of competitive models, service depth, and geographic footprints that shape vendor selection.
Global full-service organizations such as Freeman and GES have built reputations around end-to-end program management, large-scale fabrication, logistics coordination, and experiential activation for major international events. Their strength lies in integrating design, production, installation, and on-site operations at scale, which can reduce coordination risk for multinational exhibitors managing multiple markets simultaneously. Skyline Exhibits and Triumfo International contribute strong modular and custom execution capabilities, with emphasis on repeatable systems, dealer networks, and pan-European or transatlantic deployment. Pico Group and GPJ illustrate the convergence of stand construction with brand strategy and experiential design, positioning the stand not just as a physical shell but as a campaign environment with measurable engagement objectives.
Engineering-focused and premium-quality builders such as NUSSLI Group, Messe Masters, and T3 Systems highlight the importance of structural complexity, tool-free assembly, and sustainability-oriented design in mature European markets. Their capabilities matter particularly for exhibitors who need to manage strict venue rules, tight erection windows, and elevated expectations around reusability and environmental accountability. In parallel, specialist providers across the United States and Europe, including Metro Exhibits, Stallgrip Exhibits Solutions, Verlux Stands, Adam Expo Stand, Hind Exhibit, and Expo Display Service, demonstrate how differentiated positioning around custom craftsmanship, luxury aesthetics, modular flexibility, or regional service depth can coexist within a highly contested market.
Selection Criteria That Matter in 2026
Competitive benchmarking in the report is organized around decision-relevant dimensions rather than brand recognition alone. These include the ability to deliver custom and modular solutions at scale, speed of deployment under compressed timelines, compliance readiness for union labor and venue certification requirements, data-security and privacy safeguards for digital interactions on the stand, and alignment with sustainability frameworks for materials and waste management. The research also examines how concentration dynamics shape procurement leverage. With a moderately concentrated supplier base, large exhibitors can negotiate meaningful efficiencies through multi-event agreements, while smaller organizations must compete on agility, niche expertise, and localized responsiveness. The bottom line for 2026 procurement strategy is that vendor selection should be treated as a capability-mapping exercise, not a price-shopping exercise.
Operational Dynamics and Risk Factors Shaping Execution
Even the most effective strategic plan can falter if operational realities on the ground are underestimated. The exhibition stand market in 2026 is shaped by several interconnected dynamics that influence cost, schedule certainty, and compliance posture. Labor cost pressures have reshaped the economics of stand construction. Compared with pre-2020 baselines, labor costs for exhibition stand construction have risen materially, driven by inflation, capacity constraints, and collective bargaining environments in many venues. At the same time, display labor rates in recent U.S. surveys have shown more moderated increases, illustrating that the cost story is nuanced and segment-specific. For planners, this means labor assumptions must be built from current benchmarks rather than historical averages, and labor sensitivity should be explicitly modeled in total stand cost estimates.
Modularization has emerged as a direct operational response to these pressures. Tool-free assembly mechanisms and standardized modular components enable smaller, less specialized crews to complete stand erection efficiently, reducing dependency on scarce skilled labor, shortening venue access windows, and improving repeatability across events. This has strategic implications for organizations that run recurring exhibition programs across multiple cities or regions: modular capability can convert a variable, event-by-event labor burden into a more predictable and scalable operating model.
Regulatory and venue governance requirements add another layer of complexity. Union labor rules in many U.S. venues require compliance for installation, dismantling, and display work, and exhibitors or their appointed contractors frequently must present certificates of insurance and secure advance approval. These requirements affect lead times, risk allocation, and vendor eligibility. Simultaneously, data privacy regulations increasingly influence how exhibitors design attendee interaction points, capture information, and operate digital features within the stand environment. Secure data management is no longer a back-office concern; it is part of stand design and vendor selection. The report integrates these dynamics into the planning framework so that compliance is treated as a design parameter rather than a retrospective fix.
Sustainability has also moved from aspiration to structured accountability. The introduction of shared guidance for responsible design, construction, and waste management in the exhibitions sector provides a common language for exhibitors, builders, and venues. As self-scoring models and versioned guidance evolve, organizations that internalize these principles early can reduce compliance friction, improve stakeholder perception, and future-proof stand programs against tightening environmental expectations. The research situates sustainability within competitive positioning and procurement credibility, showing how responsible stand design can support both brand narrative and operational efficiency when executed with discipline.
Recent Industry Pulse: What the Latest Signals Imply for 2026 Planning
Market intelligence is most useful when it connects macro indicators to operational behavior. Several recent industry releases reinforce the planning themes embedded in the report. Global exhibition industry statistics released in early 2026 underscored the scale of the broader exhibition ecosystem, reflecting millions of exhibiting companies, substantial booth space, and hundreds of millions of visitors across tens of thousands of exhibitions. For stand strategists, these figures confirm that the physical exhibition channel remains a meaningful investment environment, but they also highlight the importance of prioritizing venues, formats, and stand concepts that maximize return within that large and heterogeneous space.
The exhibition barometer sentiment indicates that a meaningful share of companies expect rented space growth, with certain regions leading in available exhibition space. This points to a market where demand ambition and space supply are both expanding, creating opportunities for brands that can differentiate quickly and efficiently. At the same time, recent rate benchmarking across major U.S. cities shows that some operational cost categories are stabilizing at moderate increments while others remain under pressure. The implication for stand budgeting is clear: aggregate cost inflation should not be assumed uniform. Teams should decompose stand economics into materials, fabrication, labor, logistics, venue services, and digital components, then prioritize levers that genuinely move the needle.
Finally, the emergence of sustainability guidance and the continued development of scoring frameworks signal that environmental accountability is becoming an organizing principle for the sector. Companies that proactively align stand design, material selection, reuse logic, and waste management with these frameworks will face fewer institutional frictions and be better positioned for multi-event standardization. The report incorporates these developments as planning inputs, helping organizations convert industry signals into procurement, design, and program-management decisions.
What the Report Delivers for Decision-Makers
This research is designed to move beyond descriptive market commentary and provide an operational toolkit for 2026 strategy development. It connects market sizing and growth trajectory to segmentation choices, competitive benchmarking, procurement criteria, and execution risk management in a single coherent framework. The report examines stand types, industry verticals, and regional dynamics with enough structure to support prioritization, while preserving the strategic confidentiality that enables decision-makers to act on the intelligence without exposing sensitive splits prematurely.
Executive readers will find value in the way the analysis ties quantitative context to qualitative judgment. The report does not simply state that the market is growing; it explains why growth patterns differ across stand categories and verticals, how supplier models vary in capability and geography, and which operational factors are likely to determine cost and schedule outcomes in 2026 and beyond. It also places competitive profiling in a decision-useful context, showing how different providers fit into the procurement equation depending on scale, customization needs, modular flexibility, engineering complexity, and sustainability alignment.
For cross-functional teams, the research supports a more disciplined planning cascade. Strategy and marketing leaders can use it to define experience objectives and prioritization criteria. Procurement and operations teams can use it to structure vendor evaluation, total-cost modeling, and contract strategy. Finance can use it to anchor multi-year investment assumptions to credible growth and cost dynamics. And for organizations expanding internationally, the regional framework supports deliberate sequencing, balancing standardization with localization and identifying where stand investment can be scaled efficiently.
How to Use This Intelligence in 2026 Planning Cycles
The most effective way to deploy this report is as a central reference point for cross-functional alignment. Rather than allowing exhibition stand decisions to be made in silos by individual event managers or regional teams, organizations can use the segmentation and competitive insights to establish shared standards for stand type selection, vendor qualification, compliance readiness, and sustainability integration. This creates consistency across events while preserving the flexibility needed to adapt to local venue rules, audience expectations, and brand objectives.
A practical planning sequence might begin with an audit of current stand assets and event programs against the segmentation logic in the report. Teams can then identify where custom investment is justified by differentiation needs, where modular and portable systems can improve speed and cost efficiency, and where vertical-specific compliance or technical requirements demand specialized execution. From there, procurement can translate the competitive benchmarking into a structured vendor shortlist, with evaluation criteria that include capability fit, geographic coverage, union and venue compliance readiness, data-security practices, and sustainability alignment. Finally, finance and operations can build scenario models that reflect current labor, logistics, and material realities instead of legacy cost structures.
Conclusion: Strategic Clarity Before the Next Wave of Expansion
The worldwide exhibition stand market is entering a phase in which growth is real, but advantage will be earned through strategic precision. Volume alone will not guarantee impact; the brands that win in 2026 will be those that match stand type to audience expectations, choose partners for capability and compliance fit rather than familiarity, manage cost with segmented visibility, and treat sustainability and data security as design fundamentals. PW Consulting’s Worldwide Exhibition Stand Market research is built to support that discipline. It offers the strategic context, segmentation logic, competitive framing, and operational insight needed to convert exhibition investment from a recurring expense into a controlled, high-yield brand and demand-generation asset.
For leaders who want to move from general awareness to executable strategy, the full report provides the deeper segmentation detail, market sizing structure, and competitive benchmarks that underpin confident decision-making. The excerpt above establishes the strategic frame; the complete research translates that frame into the specific data and analytical depth required to guide vendor selection, budget allocation, regional prioritization, and stand-program design across the 2026 planning horizon and beyond.
For detailed analysis of this topic, please visit the official page:Worldwide Exhibition Stand Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek