
Strategic Imperatives in Epoxy Resins for Wind Energy: Navigating the 2026 Landscape
The global transition toward renewable energy sources has placed wind power at the forefront of industrial decarbonization efforts. As turbine capacities increase and offshore installations expand, the demand for high-performance epoxy resins has become a critical enabler of structural integrity and efficiency. For stakeholders operating in this sector, understanding the nuanced dynamics of the epoxy resins market is no longer optional—it is a strategic imperative. Our latest research, Worldwide Epoxy Resins in Wind Energy Market, provides a comprehensive analysis of this evolving landscape, offering the intelligence necessary to navigate the complexities of 2026 and beyond.
Worldwide Epoxy Resins in Wind Energy Market
This article serves as an executive overview of the insights contained within the study. It highlights the macro-growth trajectory, competitive pressures, and material dynamics that are shaping decision-making in the wind energy composites space. The data presented herein underscores the urgency for companies to align their supply chain strategies, product portfolios, and pricing models with the realities of a rapidly consolidating and changing market.
Worldwide Epoxy Resins in Wind Energy Market
Market Trajectory and Growth Dynamics
The historical performance of the epoxy resins market in wind energy reveals a sector characterized by steady expansion, punctuated by periods of price volatility and demand surges. Between 2020 and 2025, the industry navigated significant challenges, including supply chain disruptions and fluctuating raw material costs, yet maintained a robust upward trajectory. Revenue figures from this period illustrate the resilience of demand driven by global wind farm installations.
Worldwide Epoxy Resins in Wind Energy Market
As we look toward the forecast period spanning 2026 to 2032, the market is projected to sustain a compelling compound annual growth rate. This growth is underpinned by the continued deployment of larger rotor diameters and the increasing adoption of offshore wind technologies, which often require specialized resin systems capable of withstanding harsher environmental conditions. The projection indicates a significant increase in total revenue over the seven-year forecast horizon, reflecting the compounding effect of capacity expansions and the integration of wind energy into national grids worldwide.
For decision-makers, these macroeconomic trends translate into specific opportunities and risks. Understanding the pace of growth allows organizations to calibrate capital expenditures, plan production capacity, and negotiate long-term supply agreements with greater precision. However, growth is not uniform across all segments. The distribution of demand varies significantly when examined through different lenses, such as resin type, application method, and geographic region. Our full report dissects these variations to reveal where the highest value creation potential lies.
Segment Performance and Material Preferences
The choice of epoxy resin formulation is critical for wind turbine manufacturers. The market is segmented by resin type, with liquid epoxy resins historically dominating the share due to their versatility in infusion processes and hand lay-up applications. Solid resins and bio-based or specialty resins represent emerging niches, driven by specific performance requirements and sustainability mandates. The shift toward bio-based options, in particular, is gaining momentum as OEMs face pressure to reduce the carbon footprint of turbine production and end-of-life recycling challenges.
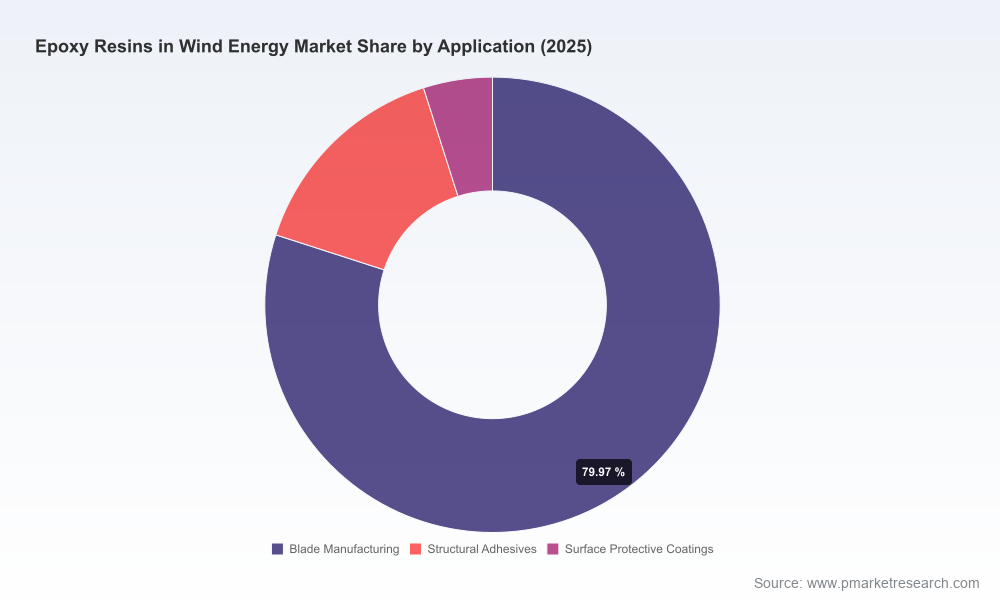
In terms of application, blade manufacturing remains the primary consumption driver. The massive scale of modern rotor blades necessitates resin systems that offer optimal mechanical properties, fatigue resistance, and processing efficiency. Structural adhesives and surface protective coatings occupy smaller but strategically important segments, supporting the assembly and longevity of turbine components. The interplay between these segments influences pricing power and innovation priorities. For instance, the push for faster curing cycles in large blades is driving demand for specialized low-viscosity systems, a trend that is reshaping product development roadmaps for major suppliers.
Geographic Distribution and Supply Chain Considerations
Geographic dynamics play a pivotal role in the epoxy resins market. Production capacities and consumption hubs are distributed across major regions, including Asia Pacific, Europe, and North America. Each region presents unique regulatory environments, logistics challenges, and local market conditions. The concentration of manufacturing activity in Asia Pacific has historically influenced global pricing structures and supply availability. Meanwhile, European and North American markets are increasingly focused on supply chain security and domestic production capabilities, especially in light of recent trade policy shifts.
Understanding the regional flow of materials is essential for mitigating risk. Supply chain bottlenecks or tariff impositions can quickly alter the cost base for manufacturers. The report provides a detailed mapping of these geographic dynamics, analyzing how local policies and production capacities intersect with global demand centers. This geographic intelligence is vital for companies seeking to optimize their sourcing strategies or identify new market entry opportunities.
Competitive Landscape and Strategic Positioning
The epoxy resins market for wind energy is moderately concentrated, with a significant portion of revenue generated by a group of established players. The competitive environment is defined by product differentiation, technological innovation, and strategic partnerships. Leading companies are investing heavily in R&D to develop resins that meet the demanding specifications of next-generation turbines while addressing sustainability concerns.
Key Players and Capabilities
Several multinational corporations and specialized chemical manufacturers hold prominent positions in this space. Westlake Epoxy, formerly known as Hexion, offers a range of specialized epoxy resin infusion systems and tooling solutions tailored for wind turbine blades. Their long-standing experience in large-scale composite rotor blades positions them as a key partner for blade manufacturers seeking proven performance. Olin Corporation provides epoxy systems for wind energy composites, including structural adhesives and resins, and has been actively involved in circularity initiatives aimed at recycling epoxy-based blades in collaboration with OEMs.
Huntsman Corporation supplies ARALDITE and other epoxy laminating resin systems, utilizing amine hardeners formulated for various composite processes such as filament winding and resin transfer molding. BASF SE has developed specific resin systems and hardeners focused on resilience against weather and mechanical stresses, catering to the durability requirements of wind turbine rotor blades. Dow Inc. contributes toughened formulations optimized for large blades and structural applications in both onshore and offshore environments. Sika AG provides composite epoxy resin systems for vacuum infusion and structural bonding, along with repair and surface finishing solutions.
In addition to these global majors, regional players play a significant role in supplying the market. Kukdo Chemical Co., Ltd. in South Korea manufactures epoxy resins for wind turbine blade composites and high-performance applications. Nan Ya Plastics Corporation in Taiwan and Aditya Birla Chemicals in India are also key suppliers of epoxy resins used in wind energy composites. Sinopec, through its subsidiary Baling Petrochemical Company in China, provides epoxy grades for wind power blade applications. Swancor Holding Co., Ltd. in Taiwan has developed specialty epoxy and hybrid resins tailored for wind power blades, while Gurit Holding AG in Switzerland supplies composite materials and epoxy resin systems optimized for blade production.
Innovation and Recent Strategic Moves
The competitive landscape is further shaped by recent product launches and strategic adjustments. Innovation is accelerating in response to the need for efficiency and sustainability. For example, significant developments have been introduced to improve processing speeds and recyclability. Product developments have focused on reducing curing times for large blades, with some new systems enabling faster cycles, thereby increasing throughput for manufacturers. Simultaneously, efforts to enhance recyclability are gaining traction, with hybrid resin technologies being explored to facilitate end-of-life management of turbine blades.
These innovations are not merely technical achievements; they represent strategic moves to capture market share and lock in customers through superior performance and sustainability credentials. Companies that can demonstrate lower lifecycle costs, better mechanical properties, or improved recyclability gain a distinct advantage in bidding for large-scale turbine contracts.
Market Dynamics: Regulation, Raw Materials, and Pricing
The epoxy resins market does not operate in a vacuum. It is heavily influenced by raw material availability, regulatory frameworks, and macroeconomic forces. Understanding these dynamics is crucial for forecasting costs and managing supply chain risk.
Raw Material Cost Sensitivity
The economics of epoxy resin production are closely tied to feedstock prices. Bisphenol A (BPA) and epichlorohydrin are primary inputs, and their costs account for a substantial portion of the total production expense. Fluctuations in these raw material markets can quickly transmit to the final price of epoxy resins. Recent observations have shown volatility in feedstock pricing, influenced by global supply conditions and regional production dynamics. For instance, periodic price adjustments in key feedstock markets can occur, such as declines in specific regions due to ample supply from other manufacturing hubs.
Conversely, demand tightness in specific geographic areas can drive prices upward. Pricing trends in regions like Northeast Asia have shown increases driven by firm demand from wind energy composites and elevated feedstock costs. These price movements highlight the interconnectivity of global markets and the importance of monitoring feedstock indicators as leading signals for resin pricing. For wind energy manufacturers, margin management requires a keen awareness of these input cost trends and the ability to pass through costs or optimize usage.
Regulatory and Trade Environment
Trade policies and regulatory changes are emerging as significant factors influencing the market. The removal of certain epoxy resin classifications from tariff exemption lists can alter the cost structure for imported materials. Such regulatory shifts have prompted domestic price adjustments and forced companies to reevaluate their sourcing strategies. In particular, anti-dumping duties imposed by the European Union on epoxy resin imports from specific countries have reshaped the competitive balance in the European market.
These duties affect the cost competitiveness of imports from different origins, creating incentives for sourcing from regions with favorable tariff treatments. Such trade measures can protect domestic producers but may also increase costs for downstream manufacturers if local supply is insufficient. The report provides a thorough analysis of these regulatory developments, assessing their impact on market entry barriers, pricing dynamics, and competitive positioning across regions.
Strategic Value for 2026 Decision-Making
The insights contained in the Worldwide Epoxy Resins in Wind Energy Market report are designed to empower organizations to make informed, forward-looking decisions. In an environment characterized by technological evolution, regulatory flux, and intense competition, access to granular, reliable intelligence is a competitive differentiator.
Actionable Intelligence for Growth and Risk Management
Our research goes beyond high-level trends to provide actionable intelligence that can be applied directly to business strategy. For product managers and R&D teams, the report offers detailed profiles of material types and applications, highlighting performance benchmarks and innovation gaps. This information can guide the development of next-generation resins that address unmet customer needs, such as faster curing, improved toughness, or enhanced recyclability.
For supply chain and procurement executives, the analysis of raw material dynamics, pricing trends, and regulatory impacts provides the context needed to negotiate contracts, hedge against cost volatility, and diversify sourcing options. The geographic segmentation and trade policy analysis enable companies to assess the risks and opportunities associated with different supply routes and manufacturing locations.
Competitive intelligence is another critical component. By examining the capabilities, recent developments, and strategic moves of key players, organizations can identify potential partnerships, benchmark their own performance, and anticipate competitor actions. The report details the product portfolios, technological strengths, and market approaches of the major suppliers, offering a nuanced view of the competitive landscape that goes beyond simple market share figures.
Navigating the Future of Wind Energy Composites
The wind energy sector is poised for continued expansion, driven by global decarbonization goals and advancements in turbine technology. Epoxy resins will remain an indispensable component of this growth, enabling the production of larger, more efficient, and more durable turbines. However, the path forward is not without challenges. Sustainability pressures, cost constraints, and regulatory uncertainties will require agile and informed responses from all stakeholders.
This research study serves as a strategic compass for navigating this complex terrain. It synthesizes data, expert analysis, and market intelligence into a coherent framework for understanding the drivers and constraints of the epoxy resins market in wind energy. Whether you are looking to expand your product offerings, optimize your supply chain, enter a new geographic market, or simply gain a deeper understanding of the industry dynamics, this report provides the foundational knowledge needed to succeed.
We invite industry leaders, investors, and strategic planners to explore the full findings of the Worldwide Epoxy Resins in Wind Energy Market. The detailed segmentation data, comprehensive competitive analysis, and forward-looking forecasts contained in the complete report offer the depth of insight required to build resilient and profitable strategies in the years ahead. As the market evolves, the ability to anticipate change and act on intelligence will define the winners in the renewable energy composites race.
For detailed analysis of this topic, please visit the official page:Worldwide Epoxy Resins in Wind Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)